AHI Journal

2026 年 9 月 11 日 星期五Friday, September 11, 2026登入Log In訂閱Subscribe
總經與流動性MACRO & LIQUIDITY

煉油裂解利差飆破百美元:能源通膨傳導正鎖定終端消費Refining Crack Spreads Blow Past $100: Energy Inflation Targets End Demand

原油斷供風險退居次席,全球成品油加工產能緊缺與長債殖利率推升,正對亞洲央行貨幣自主性形成包夾。Upstream supply disruption takes a back seat to global product bottlenecks and climbing long-end yields, hemming in policy autonomy across Asian central banks.
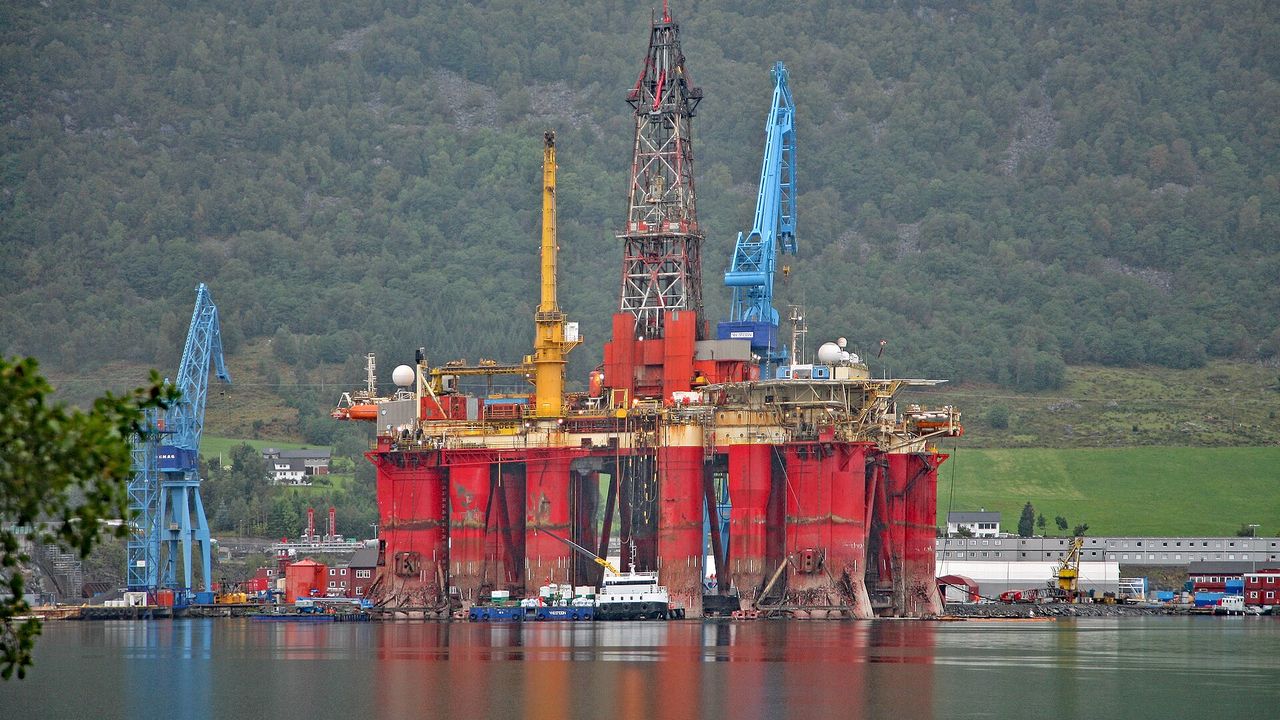
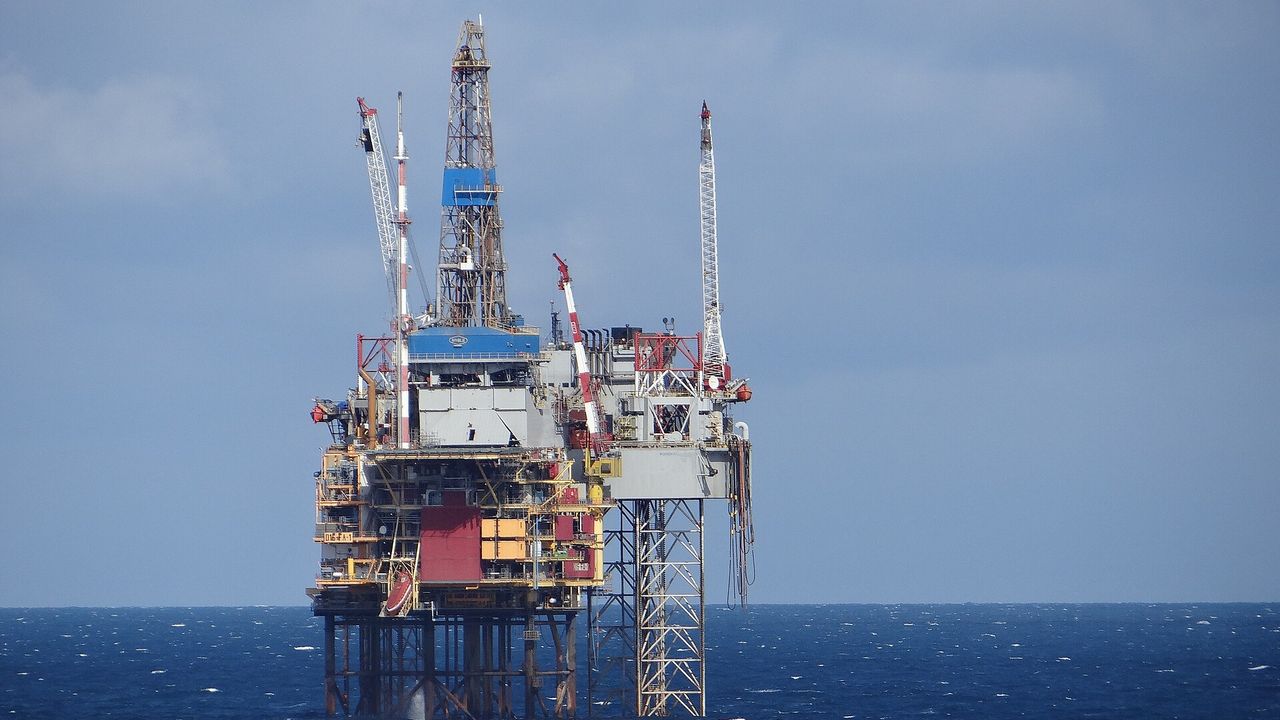
oil(海上石油鑽井平台實景)
圖:Photo: W. Bulach 授權:License: CC BY-SA 4.0 來源:Source: Wikimedia Commons
2026 年 9 月 11 日 星期五Friday, September 11, 2026總經與市場Markets貴金屬與原物料Precious Metals & Commodities免費版Free Edition
下一個可驗證時點Next checkpoint10/10(六)6505 台塑化 9 月營收(10 日前申報)
到時候看What to check9 月營收年增率是否高於前 3 個月平均(前 3 個月平均年增 +25.9%);月增率有沒有延續,累計年增率的方向。

布蘭特原油現貨價格突破 101.25 美元,但這場衝擊的真正核心已自開採端轉移至全球煉油體系。俄羅斯與中東煉油設施受創,推動歐洲柴油裂解價差直逼每桶 100 美元;OECD石油庫存自 2 月底的 30.7 億桶驟降至 8 月底的 25.3 億桶,半年內蒸發逾 5 億桶。不同於過往原油斷供焦慮,非OPEC產油國雖持續增產,石化精煉產能卻已撞上物理極限。這股由精煉瓶頸引爆的成本壓力,正從上游煉廠撲向終端消費,重塑全球市場對能源通膨的防守底線。Brent crude spot prices have broken through $101.25 per barrel, yet the true epicenter of this supply shock has shifted from the wellhead to the global refining complex. Damage to processing infrastructure across Russia and the Middle East has propelled European diesel crack spreads toward $100 a barrel, while OECD petroleum inventories plunged from 3.07 billion barrels at the end of February to 2.53 billion barrels by late August—a drawdown of more than 500 million barrels in six months. Unlike previous upstream supply crunches, non-OPEC producers continue to pump crude, but downstream petrochemical refining capacity has hit a hard physical ceiling. This refinery-driven cost shock is now cascading through the value chain to end consumers, resetting the market's defensive threshold against energy-driven inflation.

裂解利差外溢重創下游成本防線Surging Crack Spreads Breaching Downstream Cost Defenses

供給端的物理極限迅速轉化為產業鏈的成本海嘯。航空燃油報價飆升加劇高耗能機隊除役壓力,塑化基底原料行情也全線調漲。台塑四寶 8 月合併營收合計年增率達 40.7%,其中台塑化單月營收衝上 819.06 億元,顯見上游報價推升之猛烈。表面上,台灣 8 月CPI年增率受政策補貼壓制在 2.04%,看似避開通膨惡化,但進口物價指數持續向上堆疊,已對依賴原料進口的中下游傳統製造業造成慢性失血。原物料暴衝不僅侵蝕毛利,更逐步打破終端商品售價的平衡。Physical limits on the refining side are rapidly turning into an industrial cost tsunami. Soaring jet fuel prices are accelerating the retirement of fuel-inefficient commercial aircraft fleets, while basic petrochemical feedstocks have seen price hikes across the board. The combined August revenue of the Formosa Plastics Group's four core units surged 40.7% year-over-year, led by Formosa Petrochemical's monthly revenue haul of NT$81.906 billion—a clear testament to aggressive upstream price pass-throughs. On the surface, Taiwan's headline August CPI held at 2.04% year-over-year thanks to state energy subsidies, masking the underlying deterioration. However, persistent gains in the import price index represent a chronic margin bleed for downstream traditional manufacturers reliant on imported inputs. Surging raw material costs are not only chewing through gross margins, but also destabilizing final goods pricing.

美債殖利率攀升抽乾風險資產活水Spike in Treasury Yields Drains Liquidity From Risk Assets

與能源風暴同步擴散的,是全球流動性核心的緊縮警報。美國財政部針對 10 至 20 年期公債單次買回上限僅落實 60 億美元,微弱力道無法平息美債總額突破 40 兆美元的拋售恐慌。10 年期公債殖利率盤中觸及 4.857%,居高不下的實質無風險利率瞬間壓抑市場動能,道瓊指數單日回檔 0.77%,那斯達克跌幅達 0.64%。當能源通膨確立了長天期高利率環境,長久支撐資本市場的本益比擴張邏輯宣告受阻,迫使資金加速重估股票資產相對於固定收益的合理溢價。Paralleling the energy squeeze is a liquidity crunch across the global financial core. The U.S. Treasury's capped repurchase of just $6 billion in 10- to 20-year paper did little to soothe debt markets unsettled by total U.S. federal debt breaching $40 trillion. The benchmark 10-year Treasury yield touched 4.857% intraday. Sustained high real risk-free rates quickly sapped momentum across equities, pulling the Dow Jones Industrial Average down 0.77% and the Nasdaq Composite down 0.64%. With energy-driven inflation entrenching a 'higher-for-longer' rate outlook, the multiple expansion that long supported rich valuations has stalled, forcing a swift repricing of equities relative to fixed income.

匯差拉鋸限縮亞洲央行政策空間Foreign Exchange Crosscurrents Box in Asian Central Banks

美債高殖利率與能源進口負擔,正在亞洲外匯市場形成嚴峻包夾。台灣 8 月貿易出超雖錄得 223.0 億美元的強勁表現,新台幣兌美元匯率依然被強勢美元壓制在 31.505 元附近;日圓兌美元則在日銀潛在升息預期與利差拉鋸下,於 153.56 震盪。匯率貶值壓力加劇以美元計價的原物料輸入成本,亞洲央行在捍衛幣值與支撐景氣間陷入兩難。避險情緒升溫下,外資在台指期市場維持 8.39 萬口的龐大淨空單規模,展現機構法人防範現貨資產估值修正的防護姿態。High U.S. yields and mounting fuel import bills have pinned Asian currencies in an uncomfortable corner. Despite Taiwan posting a robust August trade surplus of $22.30 billion, the New Taiwan Dollar remained pinned near 31.505 against a buoyant greenback. The Japanese Yen oscillated around 153.56 per dollar, caught between Bank of Japan rate-hike speculation and wide interest rate differentials. Currency depreciation is exacerbating the landed cost of dollar-denominated raw materials, leaving regional central banks caught between defending their currencies and supporting economic growth. Reflecting this heightened risk aversion, foreign institutional investors held 83,900 net short contracts in Taiwan Index Futures, underscoring their intent to hedge against further equity multiple compression.

成品油加工瓶頸引發的通膨外溢,正逐步瓦解貨幣寬鬆的預期。接下來的觀察重點在於中東地緣局勢對關鍵航道的干擾程度,以及主要央行面對供給端頑固通膨時,是否延續偏鷹基調。一旦政策利率長期居高,位於歷史估值高點的全球成長股勢必面臨新一輪去槓桿調整。Inflationary spillovers stemming from refined-product bottlenecks are steadily dismantling expectations for near-term monetary easing. The focal point now is whether Middle Eastern geopolitical tensions inflict prolonged damage on vital shipping lanes, and whether major central banks maintain a hawkish stance in the face of supply-side stickiness. If policy rates remain pinned at these levels, richly valued global growth equities will face an inevitable phase of valuation deleveraging.

訂閱版深入拆解OECD庫存消長序列、主要石化原料利差變化圖表,以及通膨 2 次傳導下的否證條件。The subscriber edition breaks down OECD inventory trends, petrochemical feedstock spread matrices, and falsification conditions for a secondary inflationary impulse.
閱讀訂閱版Read the subscriber edition

本刊結論:Our verdict: 立場:偏多能源通膨傳導與終端緊縮壓力;信心:高,OECD石油庫存半年驟降逾 5 億桶且煉油裂解利差飆破百美元顯示精煉端供給緊繃;否證:布蘭特原油現貨價格跌破 101.25 美元且歐洲柴油裂解價差脫離每桶近 100 美元水準。

接下來看什麼What to watch next

  1. 10 年期公債殖利率:以 4.857%為門檻,若盤中持續維持或升破 4.857%則緊縮預期成立,若跌破 4.857%則緊縮預期不成立。
  2. 台灣 8 月CPI年增率與新台幣匯率:8 月CPI以 2.04%、匯率以 31.505 元為界,若通膨高於 2.04%且新台幣兌美元貶破 31.505 元則輸入性通膨成立,反之若低於 2.04%且升破 31.505 元則不成立。
  3. OECD石油庫存:以 8 月底 25.3 億桶為基準,若後續期別庫存持續低於 25.3 億桶則精煉及原油供給短缺成立,若回升至 30.7 億桶方向則不成立。

風險燈號Risk Dashboard

總經Macro
布蘭特原油突破 101 美元且長端美債殖利率升至 4.84%,通膨黏性引發央行再緊縮擔憂。Brent crude above $101 and the 10-year Treasury yield at 4.84% revive concerns over persistent inflation and renewed central bank tightening.
流動性Liquidity
外資台指期淨空單擴大至 8.39 萬口極端警戒區,大盤成交量急縮且融資餘額維持高位。Foreign Taiex futures net shorts extended to an extreme 83,918 contracts amid shrinking cash turnover and elevated retail margin debt.
產業敘事Industrial Narrative
CSP資本支出承諾強勁,但北美電網併網審批延遲,記憶體與PCB缺料通膨侵蝕組裝毛利。Robust cloud-capex guidance faces North American grid interconnection delays, while memory and PCB component inflation threatens ODM gross margins.
時間性Timing & Seasonality
時序進入 9 月傳統季節性負月,美國期中選舉監管審查升溫,距FOMC利率決議僅餘數日。Markets head into historically weak September seasonality as U.S. midterm regulatory scrutiny mounts ahead of the FOMC policy decision.

要聞速覽What’s News看完整內容 →full story →

市場Markets

油價破百美債逼近高位Oil Clears $100, Treasuries Near Highs國際油價基準布蘭特合約躍上 101.21 美元大關,同時間美債 10 年期殖利率升抵 4.84%。Brent crude topped $101.21 a barrel as the 10-year Treasury …

外資台指期空單擴至 8 萬口Foreign Futures Shorts Hit 80,000 Contracts外資在集中市場單日調節 383.34 億元,台指期淨空單進一步擴大至 83,918 口。Foreign institutions sold a net NT$38.3 billion in the cash …

台股成交金額連 3 日量縮Taiex Turnover Contracts for Third Day加權指數成交金額滑落至 7,139.72 億元,日KD高檔向下交叉。Main-board volume slid to NT$714.0 billion as daily KD indic…

產業與企業Industry & Companies

台灣 8 月出口寫歷史新猷August Exports Set Record High受資通與視聽產品外銷 331 億美元帶動,8 月份對外貿易總額比去年同期躍增 41.0%,計 824.0 億美元。August outbound shipments grew 41.0% from a year earlier to …

台積電先進晶圓代工市占 72.5%TSMC Advanced Foundry Share Reaches 72.5%晶片委託製造版圖於第 2 季擴張至歷來頂峰的 72.5%,業者亦著手採用 12 吋High NA光罩規格。Second-quarter foundry market share hit an all-time high of …

市場快照Market Snapshot

市場水位與資金流:單位不同、不可同軸比較,改以數值面板呈現市場水位與資金流Levels and Flows單位不同、不可同軸比較,改以數值面板呈現Different units — shown as figures, not bars加權指數TAIEX46940.4946940.49−242.87−242.87集中市場成交金額Main Board Turnover7139.72 億元NT$714.0 billion−1020.04 億元−NT$102.0 billion外資現貨買賣超Foreign Net Buying/Selling−383.34 億元−NT$38.3 billion−592.58 億元−NT$59.3 billion投信現貨買賣超Investment Trust Net Buying/Selling+17.86 億元+NT$1.8 billion−2.99 億元−NT$0.3 billion市場水位與資金流:單位不同、不可同軸比較,改以數值面板呈現市場水位與資金流Levels and Flows單位不同、不可同軸比較,改以數值面板呈現Different units — shown as figures, not bars加權指數TAIEX46940.4946940.49−242.87−242.87集中市場成交金額Main Board Turnover7139.72 億元NT$714.0 billion−1020.04 億元−NT$102.0 billion外資現貨買賣超Foreign Net Buying/Selling−383.34 億元−NT$38.3 billion−592.58 億元−NT$59.3 billion投信現貨買賣超投信現貨買賣超Investment Trust Net Buying/…+17.86 億元+NT$1.8 billion−2.99 億元−NT$0.3 billion

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
頭條深度LEAD ANALYSIS

原油破百美元與出口 800 億交火:台股在武裝態中面臨雙向拉扯Crude Breaks $100 as Exports Hit $80 Billion: Taiwan Equities Caught in Crossfire

外銷連 34 紅難敵期貨 8 萬口空單壓頂,能源通膨黏性正迅速侵蝕高本益比科技股的定價緩衝空間。A 34-month streak of export gains is colliding with an 80,000-contract short overhang in futures, as sticky energy inflation erodes the valuation cushion for high-multiple tech.

2026-09-11總經與市場Markets貴金屬與原物料Precious Metals & Commodities
閱讀 →Read →
AI與產業鏈AI & SUPPLY CHAIN

伺服器月出 1,000 億背後的成本暗湧:記憶體通膨考驗組裝廠韌性Undercurrents Beneath 100-Billion Server Runs: Memory Squeeze Tests ODMs

廣達能見度看至 2028 年與緯創營收飆升,正遭遇關鍵零組件暴漲與散熱升級的雙重擠壓。Quanta's order visibility through 2028 and Wistron's surging revenue face margin compression from soaring component prices and mandatory thermal redesigns.

2026-09-11科技Technology記憶體Memory
閱讀 →Read →
評等動向RATINGS TRACKER

賣方集體上修測試介面與設備:探針卡獲利模型被推向極限Sell Side Hikes Test Interface and Gear: Probe-Card Earnings Models Pushed to Brink

分析師對先進製程與高壓零組件給予最高溢價,傳統消費性電子與建商評等則遭到全面冷凍。Analysts award peak premiums to leading-edge packaging and high-voltage components, while legacy consumer electronics and developers face wholesale freezes.

2026-09-11評等Ratings半導體Semiconductors
閱讀 →Read →
海外連動CROSS-BORDER FLOWS

日經震盪與港股分化:地緣溢價與匯率波動阻斷外資套利Nikkei Stumbles, Hang Seng Splinters: Geopolitical Risk and FX Derail Arbitrage

日圓升破 153 關卡重創汽車外銷,港股科技與餐飲分道揚鑣,全球風險資產正被重新定價。A yen surge past 153 hammers Japanese auto exporters while Hong Kong tech and consumer plays diverge, forcing a broad reset of global risk assets.

2026-09-11海外Global總經與利率Macro & Rates
閱讀 →Read →
風險維度RISK DIMENSIONS

9 月歷史負效應撞上期中選舉:流動性與敘事分歧同步擴大September Slump Meets Midterm Elections: Liquidity and Narrative Fault Lines Widen

8 萬口期貨空單與融資高位形成籌碼堰塞湖,任何低於預期的法說會指引都將引爆估值回調。An 80,000-contract futures short wall alongside elevated retail margin balances leaves markets exposed to severe multiple compression on any earnings miss.

2026-09-11風險Risk台股盤面與籌碼Taiwan Market & Flows
閱讀 →Read →
本刊觀點Editor's View

在武裝態中收縮戰線:警惕百元油價與籌碼背離的共振爆發Shortening the Front Line: Guard Against $100 Oil and Positioning Divergence

市場態:武裝態(年線之上,但外資期貨淨空單處於極端空區且短線動能指標轉弱,應嚴格控管持股水位防範流動性修正)Market State: Armed State (Trading above the 240-day moving average, but foreign index-futures net shorts reside in extreme territory as short-term momentum weakens; portfolio risk must be sharply trimmed against liquidity correction)

2026-09-11本刊觀點Editor's View貴金屬與原物料Precious Metals & Commodities
閱讀 →Read →