AHI Journal
煉油利差逼近百美元,2 次通膨陰影改寫外匯與債市劇本Refining Margins Approach $100 as Secondary Inflation Threatens FX and Bond Markets
荷姆茲海峽航運大減 9 成,能源危機短缺轉向成品油煉製,美債回購失靈推升殖利率,亞洲具備高煉能經濟體築起防禦屏障。With Strait of Hormuz traffic down 90%, the energy bottleneck shifts to refined products; repo-market friction lifts Treasury yields, leaving Asian economies with heavy refining capacity as defensive bright spots.
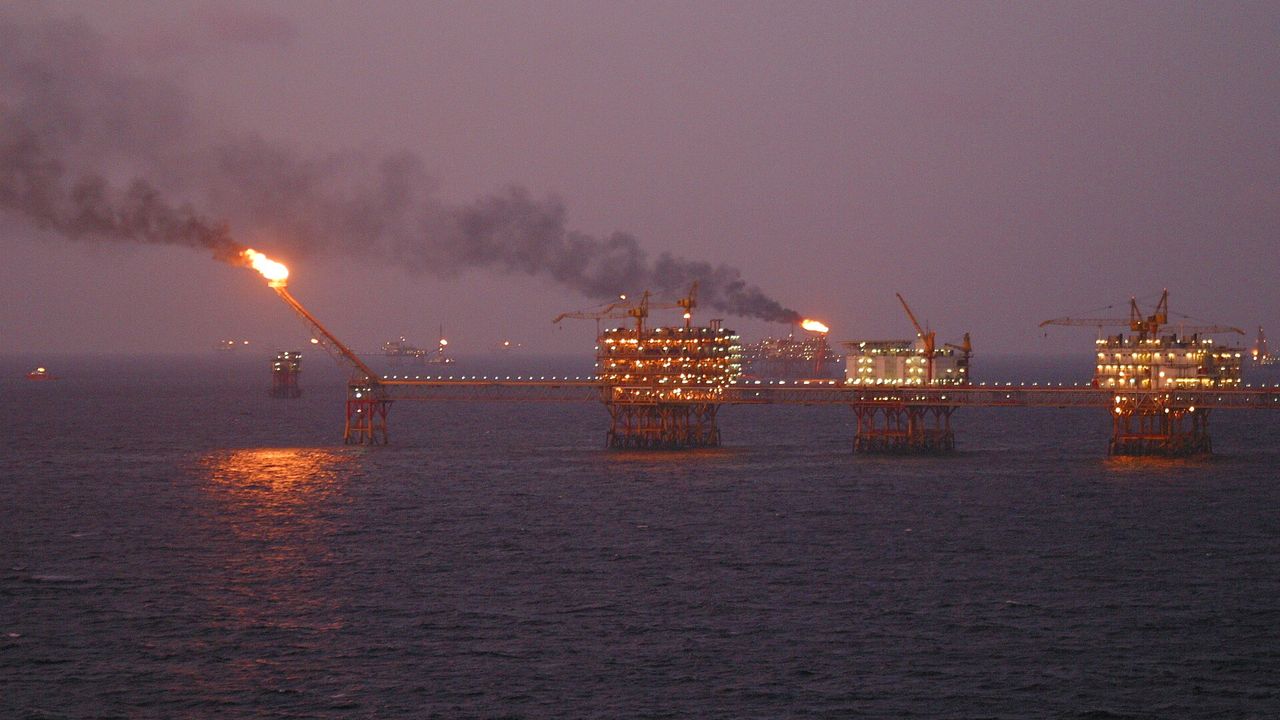
布蘭特原油突破每桶 101.21 美元大關,這場由荷姆茲海峽航運癱瘓引發的能源風暴,正從單純的原油供給缺口轉化為精煉產能的致命瓶頸。歐洲柴油裂解價差逼近 100 美元,反映出全球庫存消耗速度已超出產能修復能力。此一轉變徹底打亂了主要央行對通膨降溫的樂觀預期,使美國 10 年期公債殖利率盤中直逼 4.8528%。能源價格向下游商品外溢的 2 次通膨壓力,正透過主權債券市場的拋售潮,演變為對全球資產定價的嚴峻考驗。Brent crude’s climb past $101.21 a barrel signals that the energy shock sparked by maritime paralysis in the Strait of Hormuz has transformed from a crude supply shortfall into an acute refining bottleneck. European diesel crack spreads have approached $100, underscoring that global stock drawdowns are outstripping refining capacity recovery. This dislocation has dismantled major central banks' disinflation trajectories, pushing the 10-year U.S. Treasury yield to an intraday high of 4.8528%. Secondary inflationary pressures cascading from energy into downstream goods are now triggering sovereign debt selloffs, presenting a critical test for global asset pricing.
航道受阻逼出精煉產能極限Chokepoint Disruptions Push Refining Infrastructure to the Brink
地緣衝突使波斯灣能源運輸動脈陷入停擺,荷姆茲海峽商船通行量較衝突爆發前驟降逾 9 成。原油無法順利出港加上精煉設施頻繁遭受波及,導致OECD商業石油庫存自 2 月底的 30.7 億桶降至 8 月底的 25.3 億桶,半年內蒸發超過 5 億桶儲備。更為棘手的是,實體煉能受損引發成品油供應極度吃緊,歐洲柴油裂解價差快速推升至每桶近百美元水平。這意味著即使產油國釋出儲備,全球工業體系也無法在短時間內將原油轉化為可用燃油,能源通膨正沿著供應鏈逐層向下游擴散。Geopolitical conflict has immobilized the Persian Gulf's central shipping artery, cutting commercial transits through the Strait of Hormuz by more than 90% compared to pre-conflict levels. Strandings of crude cargoes, coupled with recurring disruptions at refining complexes, drove OECD commercial petroleum inventories down from 3.07 billion barrels at the end of February to 2.53 billion barrels by late August—erasing over 500 million barrels of reserves in six months. Compounding this challenge, damaged refining capacity has severely tightened finished fuel output, pushing European diesel crack spreads near $100 per barrel. As a result, even emergency crude reserve releases cannot be promptly processed by industrial refineries, leaving energy inflation to cascade across global supply chains.
美債回購未果加劇流動性緊縮Muted Treasury Buybacks Amplify Liquidity Strains
下游成品油價格失控使得抗通膨戰線全面拉長,直接衝擊財政與貨幣體系的承接能力。美國財政部試圖穩定長端公債市場,但首次啟動的長期國債買回計畫規模僅 60 億美元,規模顯著低於市場期待,難以抵禦龐大的發債供給潮。在通膨頑固預期與債券供應過剩的雙重夾擊下,美國 10 年期公債殖利率強勢拉升至 4.8528%,觸發全面性債券拋售。實質借貸成本長期居高不下,正迅速傳導至美國房市抵押貸款與企業融資管道,實體經濟面臨更深沉的流動性收縮威脅。Unchecked downstream fuel prices have lengthened the inflation battle, directly testing the balance-sheet absorption capacity of fiscal and monetary authorities. The U.S. Treasury’s initial long-term bond buyback operation totaled just $6.0 billion, falling well short of market expectations and providing little relief against relentless sovereign issuance. Sandwiched between sticky inflation expectations and heavy debt supply, the 10-year Treasury yield climbed firmly to 4.8528%, igniting broad-based debt selling. High real borrowing costs are quickly filtering into U.S. mortgage rates and corporate debt channels, posing a growing liquidity challenge to the broader economy.
煉能防線難敵日圓平倉外溢壓力Refining Buffers Falter Against Yen Unwind Pressures
各國經濟體在能源海嘯下的抵禦能力出現顯著斷層。具備大規模精煉基建的亞洲經濟體展現出吸收通膨的能力,台灣一線煉廠受惠於海外煉產受損產生的超額利差,台塑化 8 月營收突破 819.06 億元,年增率高達 5 成,配合南亞 8 月營收站上 306.01 億元,使台灣 8 月通膨率得以守在 2.04%。然而,匯率市場的結構重組帶來新干擾,日本央行升息預期推升日圓升破 153 關卡,日產汽車等出口產業在海外銷量重創,更引發日圓利差交易大規模平倉的恐慌,全球高估值資產面臨拋售。Economic resilience amid the energy shock has diverged along structural lines. Asian economies with extensive downstream refining infrastructure have absorbed price shocks more effectively. Benefiting from windfall refining margins caused by overseas facility disruptions, Taiwan's Formosa Petrochemical (6505) reported August revenue of NT$81.906 billion, up 50% year over year, while Nan Ya Plastics (1303) posted revenue of NT$30.601 billion, helping anchor Taiwan's headline August inflation at 2.04%. However, currency market dislocations introduced fresh volatility. Mounting Bank of Japan rate-hike expectations drove the yen past the 153 per dollar threshold, battering overseas sales for automakers like Nissan and stoking fears of an aggressive unwind in the yen carry trade that weighed on rich tech valuations globally.
全球金融環境正從單純的能源供給震撼,轉向長天期利率與匯率平倉引發的資產重估。本刊判斷,實體精煉瓶頸將使物價回落路徑較市場預期更為漫長,債券殖利率的高原期難言結束。接下來的觀察重點在於美歐核心通膨的黏著度能否有效軟化,以及日圓走強引發的資金去槓桿效應是否進一步波及權值科技股。Global financial conditions are pivoting from a simple energy supply shock to a broader asset repricing driven by higher term yields and currency unwinds. We judge that physical refining bottlenecks will extend the timeline for inflation to normalize, keeping benchmark yields elevated longer than markets anticipate. Key focus areas going forward include whether core inflation in the U.S. and Europe shows signs of softening, and whether a strengthening yen drives deleveraging that further buffets benchmark tech equities.
內含全球煉油利差傳導模型、OECD庫存變動數據表,以及日圓升值對美債流動性衝擊的檢查點。Includes our global refining-margin transmission model, an OECD inventory dashboard, and key tripwires for tracking the yen's spillover into Treasury liquidity.