AHI Journal
重電設備訂單滿載至 2029 年,分析師共識全面轉向物理缺電端Heavy Electrical Backlogs Stretched to 2029 Shift Analysts Toward Hard Bottlenecks
士電在手訂單衝破 600 億元,東元獲機構調升評等至增加持股;研究機構的選股邏輯從模型算法全面撤退,轉向不可替代的實體電力與變壓資產。Shihlin Electric backlogs topped NT$60.0 billion and TECO drew broker upgrades as equity researchers abandoned model-centric logic for irreplaceable grid hardware.
機構資金正在重新錨定人工智慧投資的主軸,將籌碼從無形的演算法模型,全面轉向具備實體物理瓶頸的電力基礎設施。士電在手訂單正式突破 600 億元大關,訂單能見度一路排至 2029 年;傳統機電大廠東元亦獲外資機構調升評等。市場對科技週期的理解正在經歷本質轉變:限制全球運算集群擴張的致命栓塞,不再是半導體先進製程,而是缺乏彈性的高壓電網硬體。當機房因電力不足而延宕點火,手握重電設備產能的製造商便由傳統週期股,躍升為掌握稀缺資產的關鍵定價者,促使資本全面轉進實體資產。Institutional capital is recalibrating the core axis of artificial intelligence investing, shifting wagers away from intangible algorithmic models and squarely toward power infrastructure constrained by physical bottlenecks. Shihlin Electric's order backlog has officially breached the NT$60 billion threshold, offering visibility stretching through 2029, while legacy electrical machinery stalwart TECO Electric & Machinery has secured an equity upgrade from foreign brokerages. Market perceptions of the tech cycle are undergoing a fundamental transformation: the fatal choke point throttling global computing clusters is no longer advanced semiconductor manufacturing, but an inelastic high-voltage grid. As data center energization stalls on power deficits, heavy electrical equipment makers with physical capacity are shedding their cyclical profiles to emerge as decisive price-setters of scarce assets, triggering a broad capital rotation into hard physical infrastructure.
超高壓變壓器擴產撞上物理極限EHV Transformer Expansion Collides with Physical Limits
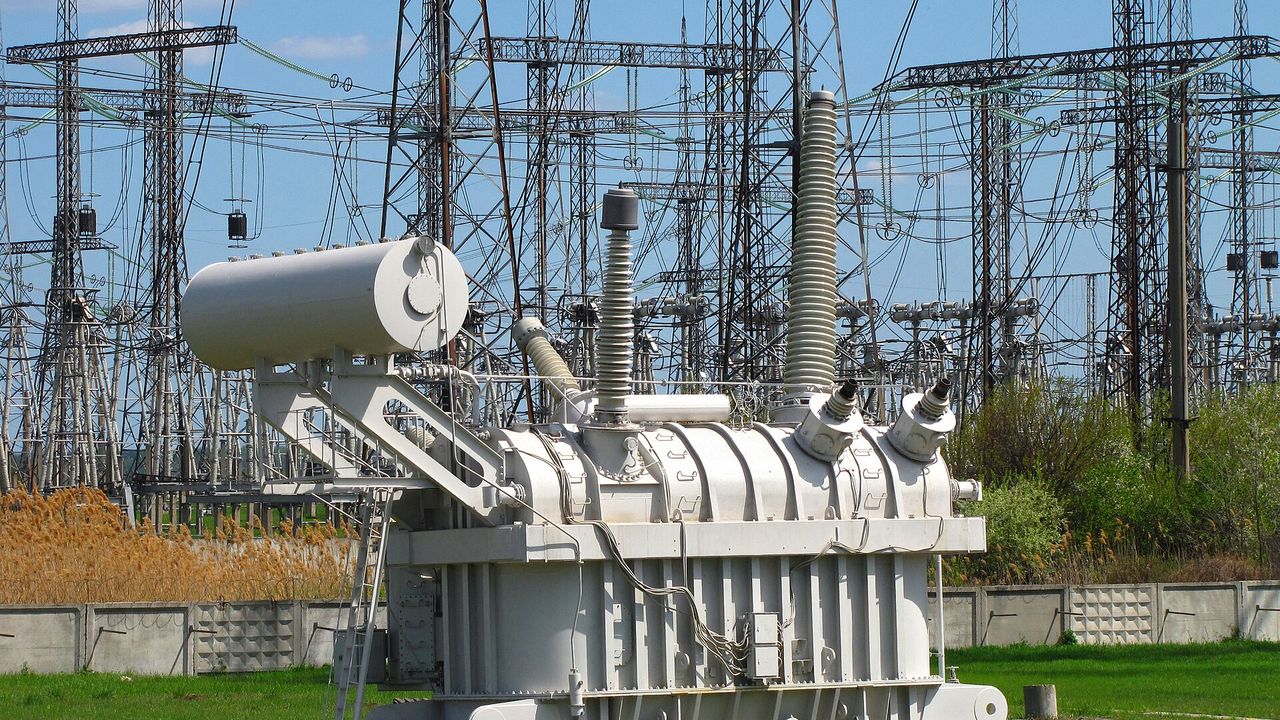
重電設備板塊的稀缺定價權,本質上建立在無法被資金或軟體加速的製造週期之上。以北美電網升級與AI資料中心不可或缺的 500kV級超高壓變壓器為例,單台設備的生產排程與驗證週期長達 2 年,實體工廠的建設節奏成了整個供應鏈的最窄瓶頸。目前士電T3 廠產能利用率長期鎖定在 90%高檔,即便公司著手擴建T4 新廠,預計新增的 3 成產能最快也必須等到 2027 年 9 月才能正式投產。更關鍵的是,這批尚未落地的產線已被北美電力客戶搶先包攬,供需嚴重失衡使設備商在面對原物料銅價走揚時,展現出強勢的成本轉嫁與毛利擴張能力。The heavy electrical equipment sector's scarce pricing power is rooted in manufacturing lead times that cannot be accelerated by capital or code. In the case of 500kV extra-high-voltage (EHV) transformers—vital for North American grid overhauls and AI data centers—the production schedule and testing cycle for a single unit spans two years, turning factory floor buildouts into the supply chain's narrowest bottleneck. Shihlin Electric's T3 facility is running at a persistent 90% utilization rate, and while construction has begun on the new T4 plant, its planned 30% capacity addition will not enter commercial production until September 2027 at the earliest. Crucially, these future lines have already been entirely locked up by North American utilities. This severe supply-demand imbalance has endowed equipment vendors with formidable cost-pass-through power and margin resilience against climbing raw material copper prices.
模組化資料中心重塑傳統機電利潤Modular Data Centers Reshape Legacy Electrical Margins
同樣的估值重估浪潮也迅速蔓延至傳統機電龍頭。市場近期將東元投資評等由「持有」調升至「增加持股」,核心驅動力在於模組化資料中心業務的結構性放量。該業務預計在 2026 年貢獻高達 59.4 億元營收,徹底打破市場過去對機電統包工程利潤薄弱的既定認知。透過提升內部關鍵電力設備的自製比重,東元成功擺脫純施工安裝的低毛利陷阱,轉型為具備高技術壁壘的系統解決方案供應商。在產品組合大幅優化與海外資料中心工程推升下,研究機構預估其 2027 年每股獲利將穩固站上 3.47 元,確立了傳統工業股的盈餘結構蛻變。This valuation re-rating is spreading quickly across traditional industrial champions. Analysts recently lifted TECO Electric & Machinery to Overweight from Hold, pushing its target price to NT$83, driven by the structural scaling of its modular data center operations. That division is projected to generate NT$5.94 billion in revenue by 2026, dismantling the long-held view that electrical EPC contracting yields meager margins. By manufacturing a higher proportion of proprietary critical power components in-house, TECO has broken out of low-margin turnkey installation traps to reposition as a high-barrier systems solution provider. A richer product mix combined with overseas data center builds has prompted research houses to project 2027 earnings per share will firmly cross NT$3.47, solidifying a structural upgrade in the company's earnings power.
算力狂飆與電網增長的交期剪刀差The Lead-Time Scissor Between Compute and Grid Expansion
此波評等集體上修的深層邏輯,源於分析師對AI產業發展盲區的反思。晶片運算效能依照摩爾定律每 18 個月便翻倍成長,然而北美變壓器製造端的年複合擴產速度僅維持在個位數百分比,兩者在時間尺度上的巨大落差,形成了尖銳的交期剪刀差。實體電網的容量極限正直接收緊資料中心運作的空間,迫使雲端服務商接受更長交期與更高報價。當市場追逐算力的狂熱降溫,資本配置自然轉向具備絕對供給剛性的物理節點。這場估值重組反映出,在電力瓶頸未獲根本性解決前,誰擁有能實際通電的硬體資產,誰就能掌握產業價值鏈中最具防禦性的利潤分配權。Underpinning these broad rating upgrades is a reappraisal of an industry blind spot. Chip computing power doubles roughly every 18 months under Moore's Law, yet North American transformer manufacturing capacity expands at a compound annual rate in the mid-single digits. This massive temporal divergence creates a sharp scissor effect in lead times. Physical grid ceilings are directly constraining the addressable footprint for data centers, compelling cloud service providers to accept longer delivery timelines and premium pricing. As speculative fervor surrounding pure compute cools, capital allocations are pivoting to physical infrastructure nodes marked by absolute supply rigidity. This valuation reset demonstrates that until grid bottlenecks are comprehensively broken, the entities holding deployable hardware will command the most defensive slice of the industry's profit pool.
重電板塊的多頭行情已脫離單純題材炒作,進入實質交貨與工程兌現期。本刊判斷,重電製造商的利潤優勢短期內具備強大防禦力,但高估值也壓縮了容錯空間。接下來的觀察核心並非訂單金額的單純膨脹,而是海外公用事業與表後儲能專案的實質併網節奏,任何交貨延遲都將直接考驗市場對高本益比的容忍度。The rally in heavy electrical equipment has moved beyond thematic hype and entered a phase of physical deliveries and project execution. AHI Journal assesses that manufacturers' margin advantages offer sturdy near-term defense, but elevated valuations leave scant room for operational error. The key metric to watch is not the raw expansion of order backlogs, but the pace of actual grid interconnection across overseas utilities and behind-the-meter storage projects; any delivery slippage will directly test institutional tolerance for stretched multiples.
全文提供北美變壓器供需缺口測算、士電與東元產能投產時間表及表後儲能併網檢查點。The full dispatch delivers proprietary sizing of North American transformer supply-demand deficits, capex schedules for Shihlin Electric and TECO, and key grid-interconnection checkpoints for behind-the-meter storage.