AHI Journal

2026 年 9 月 14 日 星期一Monday, September 14, 2026登入Log In訂閱Subscribe
評等Ratings · 評等動向板Ratings Board

本期評等動向 7 檔7 Rating Actions This Issue

同一標的多家動作合併為一列;不含目標價。Multiple actions on the same name merged into one row; no price targets.

2026 年 9 月 14 日 星期一Monday, September 14, 2026評等Ratings綜合General免費版Free Edition

本期評等動向板彙整 7 檔標的的賣方動作。方向分布為偏多 4 檔、偏保守 0 檔、維持或首次覆蓋 3 檔;其中 0 檔在同一週內有 2 家以上機構同向出手,最集中的一檔由 1 家機構同時調整。動作方向與家數是本板唯一記錄的 2 個欄位——本刊不轉載任何機構的目標價與獲利預估,同一標的多家同向的動作會合併為一列,避免把同一則資訊重複計算成多個訊號。This issue's ratings board covers sell-side actions on 7 names: 4 positive, 0 cautious and 3 maintained or newly initiated. 0 of them drew moves in the same direction from two or more houses in a single week, and the most crowded name was adjusted by 1 houses at once. Direction and house count are the only two fields this board records — we reproduce no house's price target or earnings estimate, and multiple same-direction actions on one name are merged into a single row so that one piece of information is not counted as several signals.

本期評等動作方向分布(合計 7)本期評等動作方向分布Distribution合計 7 檔7 names in total43偏多Positive4 · 57%維持或首評Maintain / initiate3 · 43%本期評等動作方向分布(合計 7)本期評等動作方向分布Distribution合計 7 檔7 names in total43偏多Positive4 · 57%維持或首評Maintain / initiate3 · 43%
評等動作的產業分布評等動作的產業分布Breakdown012 檔綜合General2 檔2 names科技巨頭與美股科技巨頭與美股Big Tech & U.S. Equit…1 檔1 names光通訊與 CPOOptical & CPO1 檔1 names半導體Semiconductors1 檔1 names軍工與航太Defense & Aerospace1 檔1 names航運Shipping1 檔1 names評等動作的產業分布評等動作的產業分布Breakdown012 檔綜合General2 檔2 names科技巨頭與美…科技巨頭與美股Big Tech &…1 檔1 names光通訊與 CPO光通訊與 CPOOptical & C…1 檔1 names半導體半導體Semiconduct…1 檔1 names軍工與航太軍工與航太Defense & A…1 檔1 names航運Shipping1 檔1 names

以產業分布看,本期動作集中在綜合 2 檔、科技巨頭與美股 1 檔、光通訊與 CPO 1 檔。產業分布比個別評等更有資訊量:當調整集中在單一產業,通常對應的是該產業的一項共同事件(報價、法說、政策或供應鏈變化),而不是各家對個別公司的獨立判斷;當調整分散在多個不相干產業,較可能是大盤層級的估值重設,個股層面的意義反而低。By industry, this issue's actions cluster in General 2, Big Tech & U.S. Equities 1, Optical & CPO 1. The industry split carries more information than any single rating: when adjustments concentrate in one industry, they usually trace back to one shared event — pricing, an earnings call, policy or a supply-chain shift — rather than to independent judgments on individual companies. When they scatter across unrelated industries, it is more likely a market-level re-rating, and the stock-level meaning is correspondingly thinner.

本刊對「集體上修」保持一貫的懷疑:多家同時調高,可能是基本面真的改變,也可能只是評價年度往後滾動(把估值基準從今年換到明年)而讓目標價機械性變高。這兩者在報告摘要裡看起來一樣,拆開來看卻是完全不同的資訊——前者值得追蹤,後者沒有資訊量。因此本板在訂閱版會逐檔註記上修究竟來自盈餘上調還是倍數擴張,並標出哪些是首次覆蓋(首評天然偏多,不應與既有覆蓋的調升混為一談)。We stay sceptical of the cluster upgrade. When several houses raise at once it may mean the fundamentals genuinely changed — or merely that the valuation year has rolled forward, moving the base from this year to next and lifting price targets mechanically. The two look identical in a report summary and are entirely different pieces of information once separated: the first is worth tracking, the second carries none. The subscriber edition therefore annotates, name by name, whether an upgrade came from earnings or from multiple expansion, and flags which are first-time coverage — initiations skew positive by construction and should not be read alongside upgrades to existing coverage.

使用方式上,評等動向板是研判的起點而不是結論。賣方動作反映的是研究資源的投向與敘事的轉折,與股價的後續表現沒有穩定的正向關係,消息見報時市場多半已經反應過一輪。它真正的用途是提示你哪一條供應鏈正在被重新定價,接著再用營收、法人買賣超與價格位置去驗證那個敘事是否成立。Read the board as a starting point, not a conclusion. Sell-side actions show where research resources are going and where the narrative is turning; they bear no stable positive relationship to what the share price does next, and by the time the news is out the market has usually moved. Their real use is to point out which supply chain is being repriced — after which revenue, institutional flows and price position are what actually test whether the narrative holds.

訂閱版含逐檔代號、動作、家數與理由,以及本刊對「集體上修」是盈餘驅動還是倍數驅動的逐檔拆解。The subscriber edition lists every ticker, action, house count and rationale, plus our stock-by-stock read on whether the cluster of upgrades is earnings-driven or multiple-driven.
閱讀訂閱版Read the subscriber edition

風險燈號Risk Dashboard

總經政策Macro Policy
美國 8 月核心服務通膨黏著推升FOMC升息機率至近 9 成,美債殖利率逼近 5%加大估值折現壓力。Persistent U.S. core services inflation raised September FOMC hike odds near 90%, leaving yields near 5% to pressure equity discount rates.
流動性結構Liquidity Structure
外資期貨淨空單高懸 8.5 萬口歷史極端區,融資餘額逼近 5,900 億元高檔,籌碼分化暗藏踩踏風險。Foreign net futures shorts stood near records at 85,000 contracts against NT$587.9 billion in retail margin debt, heightening unwinding risks.
產業與實體瓶頸Industrial Bottlenecks
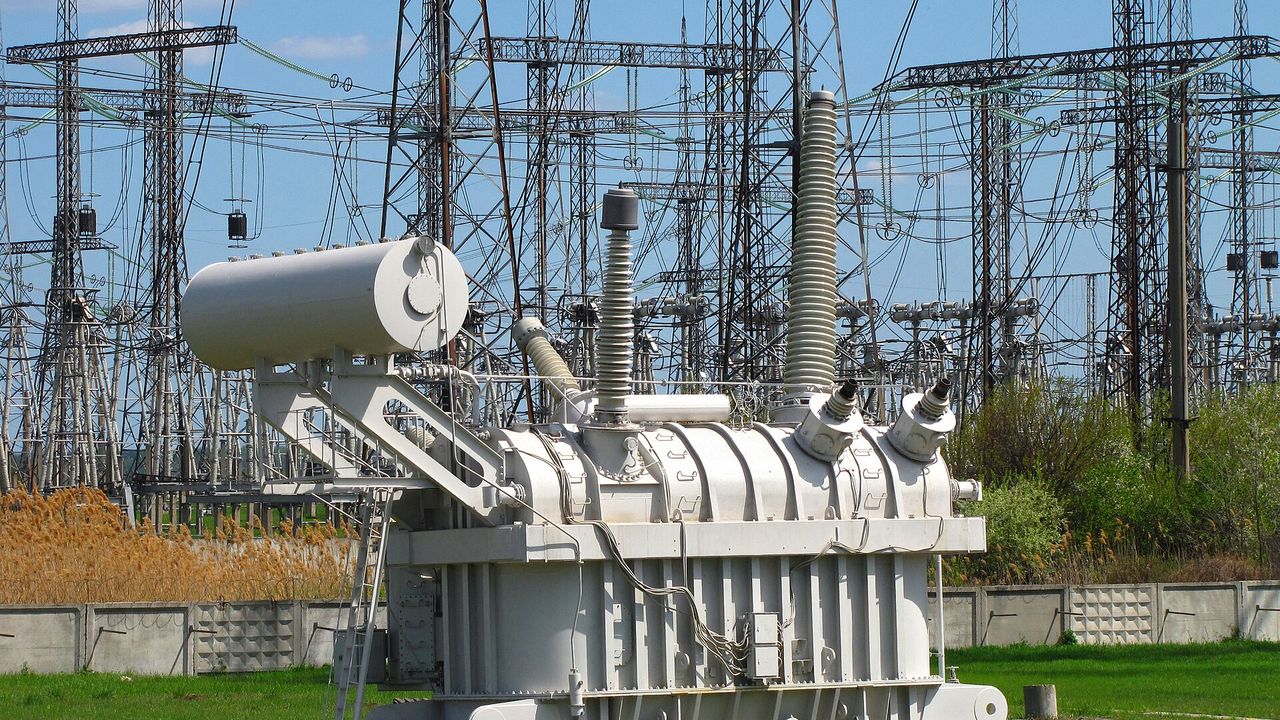
重電變壓器交期長達 2 年且磷化銦基板供給受限,AI強勁需求遭遇實體製造與電網完工瓶頸約束。Power transformer lead times of up to two years and tight InP substrate supplies continue to cap physical data center buildouts.
時間性與季節性Seasonality & Event Risk
9 月歷史負報酬魔咒遭遇美國期中選舉倒數 50 天政治懸崖,12 月中旬政府關門隱憂壓抑風險偏好。September seasonal weakness meets the 50-day countdown to U.S. midterms and mid-December federal shutdown threats, constraining risk tolerance.

要聞速覽What’s News看完整內容 →full story →

市場Markets

金融股逆勢創高撐盤Financials Reach Record Highs玉山金與一家研究機構等多檔金控盤中改寫歷史新高,有效承接外資自電子權值股調節之賣壓。E.Sun Financial and First Financial touched record intraday …

台股ETF總規模破 7.8 兆Taiwan ETF Assets Top NT$7.8 Trillion台股高檔震盪之際,被動投資資金持續流入,0050 今年以來規模激增 1.4 兆元。Passive inflows accelerated through index consolidation, lif…

美債殖利率逼近年內高點U.S. Yields Re-Test Annual Peaks美國 10 年期公債殖利率單週大漲 18 個基點至 4.9669%,長債標售規模未達上限加劇供給壓力。The 10-year U.S.

產業與企業Industry & Companies

旺矽探針卡獨佔新專案MPI Secures Full Run of New Sockets受惠競爭對手品質瑕疵退出,旺矽取得輝達Vera CPU關鍵探針卡訂單,月針數朝 850 萬針擴充。After a key rival stumbled on quality, MPI won exclusive pro…

全新光電子營收黃金交叉Visual Photonics Optoelectronics Crosses Inflection8 月光電子營收比重拉升至 46.1%,800G與 1.6T高速傳輸磊晶片出貨翻倍。Optoelectronics hit 46.1% of August revenue at Visual Photon…

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
測試介面霸權重組TEST INTERFACE HEGEMONY

關鍵對手品質瑕疵退出,旺矽壟斷次世代算力探針卡份額Rival Yield Failure Leaves MPI With Near-Monopoly on Next-Gen Probe Cards

台系同業良率失誤打破雙供應商制衡,旺矽 2027 年產能直指 850 萬針;當高階晶圓測試成為先進製程擴產的實體限制,漲價能力正發生長期單向轉移。A quality lapse by a domestic competitor broke the dual-sourcing balance, clearing the path for MPI to target 8.5 million monthly pins by 2027 as wafer test bottlenecks hand suppliers unilateral pricing power.

2026-09-14科技Technology半導體Semiconductors
閱讀 →Read →
總經與結構分化MACRO & STRUCTURAL DIVERGENCE

電子出口單月暴增 58%,台灣雙軌經濟直面升息與通膨黏性Tech Shipments Surge 58%, Trapping Taiwan in a Two-Speed Economy

AI外貿狂飆掩蓋了終端消費疲態,台灣前 8 月出口額衝上歷史新高;然而美國長債殖利率迫近 5%大關,正在對內部高本益比族群執行隱性估值壓縮。AI exports masked consumer weakness to push eight-month outbound shipments to records, even as U.S. 10-year yields near 5% to squeeze high-multiple valuations.

2026-09-14總經與市場Markets總經與利率Macro & Rates
閱讀 →Read →
光互聯硬體躍遷OPTICAL INTERCONNECT TRANSITION

光電子營收比重逼近 5 成,全新迎來磊晶結構的黃金交叉Optoelectronics Approaches 50% of Sales as Visual Photonics Hits Inflection Point

AI資料中心 1.6T光模組需求爆發,全新 8 月光電子營收佔比急拉至 46.1%;透過客供料模式化解磷化銦斷料隱憂,獲利體質跨入高毛利擴張期。Surging 1.6T module demand drove optoelectronics to 46.1% of August revenue at Visual Photonics, where customer-consigned materials insulated margins from InP wafer shortages.

2026-09-14科技Technology光通訊與 CPOOptical & CPO
閱讀 →Read →
評等調升譜系RATING UPGRADE CYCLE

重電設備訂單滿載至 2029 年,分析師共識全面轉向物理缺電端Heavy Electrical Backlogs Stretched to 2029 Shift Analysts Toward Hard Bottlenecks

士電在手訂單衝破 600 億元,東元獲機構調升評等至增加持股;研究機構的選股邏輯從模型算法全面撤退,轉向不可替代的實體電力與變壓資產。Shihlin Electric backlogs topped NT$60.0 billion and TECO drew broker upgrades as equity researchers abandoned model-centric logic for irreplaceable grid hardware.

2026-09-14評等Ratings半導體Semiconductors
閱讀 →Read →
跨洋產業鏈震盪TRANS-PACIFIC HARDWARE SHOCK

傳統網通遭算力吞噬,日本核電重啟折射全球電力荒Traditional Networking Suffers Capex Squeeze as Japan Restarts Nuclear Reactors

訊舟等終端設備商在AI排擠效應下陷入虧損,日本電力大廠因重啟 16GW核能資產獲買盤青睞;全球資本開支正展開殘酷的存量掠奪。Edge equipment makers like Edimax slipped into losses under AI budget diversion, while Japanese utilities rallied on 16GW in reactor restarts amid global power constraints.

2026-09-14海外Global半導體Semiconductors
閱讀 →Read →
籌碼與地緣夾擊POSITIONING & GEOPOLITICAL PINCH

8 萬 5,000 口空單與 10 月選戰碰撞,法人資金撤向被動與高股息堡壘85,000-Contract Short Overhang Collides With U.S. Midterms, Forcing Run to High Dividends

外資期貨淨空單居高不下疊加美國期中選舉政治懸崖,機構資金轉向高股息ETF與歷史新高金融股建立避險壁壘。Persistent foreign index futures shorts and looming political cliffs in Washington pushed institutional capital toward high-yield ETFs and record-setting bank shares.

2026-09-14風險Risk台股盤面與籌碼Taiwan Market & Flows
閱讀 →Read →