AHI Journal

2026 年 9 月 16 日 星期三Wednesday, September 16, 2026登入Log In訂閱Subscribe
評等動向與共識分歧Rating Trajectories & Consensus Fractures

台積電與奇鋐獲利預估分歧 賣方共識在 2027 年出現巨大落差Earnings Estimates Diverge for TSMC and CCI as Sell-Side Consensus Fractures for 2027

台積電 2027 年獲利預估相差近 2 成,環球晶更達 1.4 倍;市場對資本支出轉化節奏出現認知斷層。Brokerage estimates for TSMC's 2027 earnings show a gap of nearly 20%, while GlobalWafers shows a 1.4-fold spread, revealing sharp analytical divides over the pace of capex monetization.
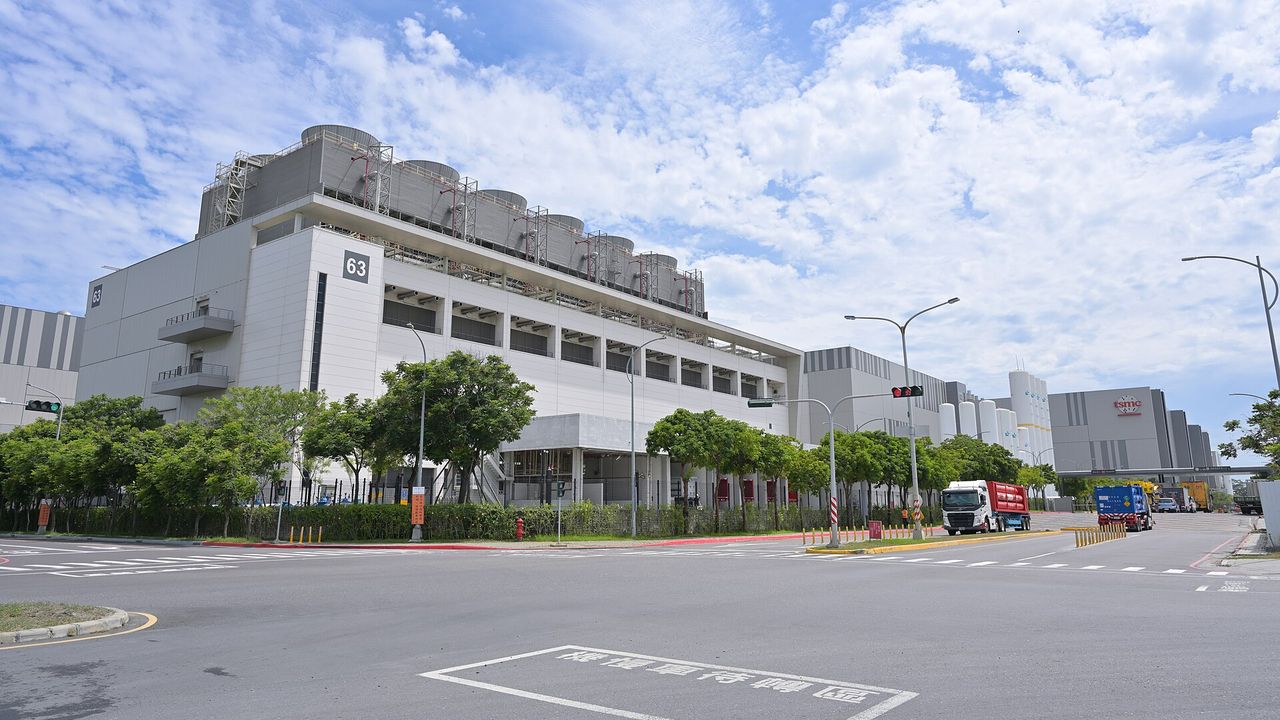
台積電南科十八廠
圖:Photo: 4300streetcar 授權:License: CC BY 4.0 來源:Source: Wikimedia Commons
2026 年 9 月 16 日 星期三Wednesday, September 16, 2026評等RatingsAI 伺服器AI Servers免費版Free Edition
下一個可驗證時點Next checkpoint10/10(六)2330 台積電 9 月營收(10 日前申報)
到時候看What to check9 月營收年增率是否高於前 3 個月平均(前 3 個月平均年增 +47.5%);月增率有沒有延續,累計年增率的方向。

賣方研究機構在表面上維持對先進半導體與人工智慧供應鏈的一致看多,但最新統計顯示,拉長至 2027 年的獲利預估已出現罕見的共識裂縫。台積電 2027 年預估每股純益區間落在 135.22 元至 155.09 元,高低差距達 14.7%;矽晶圓龍頭環球晶的高低預估差距更暴增至 145.6%。這種離散度的非正常擴大,說明市場對超大型雲端服務商資本支出能否順利變現、新製程產能放量節奏與定價能力,存在截然不同的底層假設。在評價已被推升的當下,這場認知斷層正演變為中長期資金布局的最大隱憂。Sell-side research desks maintain an outwardly unified bullish stance on the advanced semiconductor and AI supply chains, yet fresh data reveals a rare fracture in consensus profit forecasts looking out to 2027. Forward 2027 EPS estimates for TSMC span NT$135.22 to NT$155.09—a 14.7% spread between the high and low marks—while the gap for silicon wafer leader GlobalWafers has blown out to an astonishing 145.6%. This abnormal widening of dispersion indicates that the market holds sharply divergent baseline assumptions regarding whether hyperscale cloud capex can be successfully monetized, as well as the pace of next-gen capacity ramps and pricing power. With valuations already stretched, this cognitive rift is turning into the single biggest structural overhang for mid- to long-term institutional capital.

先進製程定價與擴產節奏認知斷層Cognitive Rifts in Advanced Node Pricing and Capacity Ramps

台積電做為晶圓代工核心,其預估分歧直接反映了分析圈對 2 奈米技術節點商業化節奏的認知衝突。部分機構認為客戶對高階算力的剛性需求,將允許台積電維持強勁的定價溢價能力,驅動 2027 年獲利站上高標;然而較為謹慎的觀點則質疑,終端雲端客戶在巨額資本開支後面臨投資回報率壓力,擴產進度與折舊攤提可能侵蝕利潤率。這種分歧進一步向上游晶圓材料傳導,環球晶 2027 年每股純益預估出現 32.53 元至 79.89 元的極端差距,意味著產業鏈最上游的投片回升節奏,在分析模型中早已脫離單一線性的復甦路徑。As the core foundry linchpin, TSMC's divergent forecasts directly reflect analytical clashes over the commercialization trajectory of the 2nm process node. One camp argues that insatiable customer demand for premium computing power will preserve TSMC's robust pricing premium, propelling 2027 earnings to the top end of projections. More cautious observers, however, question whether cloud end-customers—facing mounting ROI pressures following massive capital expenditures—will see capacity utilization and depreciation charges erode operating margins. This skepticism travels upstream into raw wafer materials, where GlobalWafers' 2027 EPS estimates range from an extreme low of NT$32.53 to a high of NT$79.89, underscoring that analytical models have completely abandoned a linear recovery path for upstream wafer starts.

機構對環球晶 2027 年獲利預估裂縫機構對環球晶 2027 年獲利預估裂縫Breakdown數字取自本文Figures quoted from this article04080 元環球晶 2027 預估高標環球晶 2027 預估高標79.89 元79.89 元環球晶 2027 預估中標環球晶 2027 預估中標60 元60 元環球晶 2027 預估低標環球晶 2027 預估低標32.53 元32.53 元機構對環球晶 2027 年獲利預估裂縫機構對環球晶 2027 年獲利預估裂縫Breakdown數字取自本文Figures quoted from this article04080 元環球晶 2027…環球晶 2027 預估高標環球晶 2027…79.89 元79.89 元環球晶 2027…環球晶 2027 預估中標環球晶 2027…60 元60 元環球晶 2027…環球晶 2027 預估低標環球晶 2027…32.53 元32.53 元
圖對應:凸顯賣方對矽晶圓復甦力道認知的巨大差異讀法:這幾個數字取自本文、同一個單位放在同一把尺上比較,不是本刊面板另算的行情或營收。

關鍵散熱架構滲透率面臨模型分流Thermal Architecture Penetration Faces Divergent Modeling

硬體關鍵零組件的預估落差同樣印證了長期預期的失錨。散熱指標廠奇鋐在 2026 年的預估每股純益落在 101 元至 106.21 元,機構間差距僅 5.2%,顯示短期營運能見度極高;但進入 2027 年後,預估區間驟然拉大到 152.29 元至 180.02 元,離散度擴張超過 3 倍。落差的核心在於對下一代水冷架構普及速度的評估分歧,特別是針對特定應用晶片的客製化雙面散熱與伺服器整機櫃方案,不同分析模型給出的滲透率假設極為分歧。一旦關鍵客戶轉向自研架構或修改散熱規格,現有供應商的獲利預估便將面臨重新洗牌的風險。Forecast disparities across critical hardware components further demonstrate how long-term expectations have become unanchored. For benchmark thermal supplier AVC, consensus 2026 EPS estimates sit tightly between NT$101 and NT$106.21—a mere 5.2% variance that reflects exceptional near-term visibility. By 2027, however, the estimate band widens sharply to NT$152.29 to NT$180.02, expanding the dispersion more than threefold. At the heart of this divergence lies disagreement over the adoption velocity of next-generation liquid-cooling architectures, particularly customized dual-sided thermal modules for ASICs and full-rack server deployments. Should key clients pivot to proprietary architectures or overhaul thermal specifications, existing suppliers' earnings projections face severe reshuffling risks.

成熟製程與消費電子呈現保守收斂Mature Nodes and Consumer Electronics Converge on Conservatism

與人工智慧硬體端的劇烈發散相比,成熟製程與消費性電子領域的預估曲線卻呈現出高度一致的保守收斂。晶圓代工廠聯電在 2026 年的預估每股純益收斂於 6 元至 7.86 元區間,機構間的預期差距極為有限;射頻功率放大器代工廠宏捷科更因關鍵零組件價格飆漲壓抑終端手機出貨,遭到分析機構調降評等。市場對非人工智慧領域的成長疲弱、成本轉嫁困難已建立明確共識。這種成熟製程的收斂低迷與先進製程的高位分歧形成鮮明對照,突顯出整體半導體產業動能過度集中於單一領域,讓預期裂縫的潛在衝擊更加擴大。In stark contrast to the wild divergence in AI hardware, forecast curves for mature nodes and consumer electronics exhibit highly aligned, conservative convergence. For foundry peer UMC, 2026 EPS forecasts are tightly clustered between NT$6 and NT$7.86 with minimal institutional disagreement. RF power amplifier foundry AWSC has faced rating downgrades as surging upstream component prices dampen downstream smartphone shipments. Consensus is firmly established around sluggish non-AI growth and poor cost pass-through. This subdued, tight consensus in mature nodes contrasts sharply with the elevated volatility in advanced-process projections, spotlighting how semiconductor industry momentum is dangerously concentrated in a single vertical and amplifying the vulnerability of the broader market to expectation shocks.

本刊判斷,當前的獲利離散現象預告著市場正進入估值修正的敏感期,任何技術放緩或資本支出放緩的信號,都可能引發高標預估組的集體下修。接下來的關鍵焦點,在於晶圓龍頭即將釋出的中長期先進封裝與新製程資本支出指引方向。指引的擴張或收縮,將直接決定市場共識究竟是向上錨定還是向下落軌。AHI Journal assesses that this earnings dispersion signals the market is entering a sensitive phase of valuation reassessment, where any hint of a technological slowdown or capex deceleration could trigger sweeping downgrades from the optimistic camp. The immediate focal point rests on upcoming medium- and long-term capital expenditure guidance for advanced packaging and next-generation nodes from leading foundries. Whether that capex envelope expands or contracts will dictate whether consensus earnings anchor higher or derail downward.

訂閱版詳列各機構對指標股的EPS估值分布表、差異成因拆解與關鍵否證條件。The subscriber edition provides an institutional EPS forecast matrix for bellwether names, a breakdown of driver variances, and key falsification criteria.
閱讀訂閱版Read the subscriber edition

本刊結論:Our verdict: 立場:中性,針對市場對 2027 年先進製程獲利與資本支出轉化節奏之共識;信心:中,因 2027 年遠期獲利預估離散度顯著擴大,多空假設嚴重分歧;否證:若台積電於 10 月法說會給出明確指引使賣方對 2027 年EPS預估差距收斂至 5%以內,則本刊判斷市場認知存在斷層為錯誤。

接下來看什麼What to watch next

  1. 台積電資本支出指引:於 10 月法說會若整體資本支出指引超過 650 億美元,則高標預估組成立;若整體指引低於 600 億美元,則成立市場集體下修壓力,未達此區間則不成立。
  2. 奇鋐獲利共識落差:2027 年 7 家機構預估EPS高低差距是否維持在 18.2%(落在 152.29 元至 180.02 元區間),若差距維持或擴大則分歧成立,若收斂至 2026 年的 5.2%水準則不成立。

風險燈號Risk Dashboard

總經政策Macro Policy
美債 10 年期殖利率升破 5%且油價破百,市場對聯準會升息定價超過 9 成。10-year Treasury yields topped 5% alongside $100-plus crude, driving market pricing for a Fed hike above 90%.
流動性結構Liquidity Structure
外資期貨淨空單高懸 8.3 萬口,集中市場成交值連續 10 日低於 5 日均量。Foreign futures net short positions sit at 83,000 contracts; cash equity turnover trailed its 5-day average for 10 straight sessions.
產業敘事Industry Narrative
AI模型放緩雜音與伺服器交期長短料錯配,成本轉嫁壓力向組裝端傳導。Chatter around slowing AI model gains and component mismatch in server builds are shifting cost pressures onto assemblers.
時間季節性Seasonality
時序進入 9 月歷史負報酬高風險窗口,全球超級央行週與美股四巫日集中到來。September opens a historically weak seasonal window, coinciding with central bank decisions and Triple Witching volatility.

要聞速覽What’s News看完整內容 →full story →

市場Markets

外資期貨空單維持高檔Foreign Futures Short Positions Remain Elevated9 月 15 日外資台指期淨空單續留 83,223 口,現貨單日賣超達 626.99 億元,壓抑台指結算走勢。Foreign institutional investors maintained 83,223 net short …

美債殖利率升破 5%關卡U.S. 10-Year Yield Breaches 5% Threshold原油價格突破 105 美元大關,帶動市場押注聯準會升息的機率飆破 9 成,美債基準 10 年期殖利率亦於交易時段摸高至 5.012%。Crude oil breached $105 per barrel, pushing market-implied o…

三大法人擴大調節現貨Institutions Accelerate Cash Equity Selling三大法人於集中市場單日擴大賣超 791.25 億元,加權指數收在 45,511.49 點測試季線防守區。The three major institutional groups offloaded a net NT$79.1…

產業與企業Industry & Companies

台積電擴建先進封裝產能TSMC Expands Advanced Packaging Capacity台積電 2 奈米產能預計明年達每月 10 萬片,CoWoS月產能年底估達 14.5 萬片,明年續衝 17.5 萬片。TSMC projects 2-nanometer capacity will reach 100,000 wafers…

NOR快閃記憶體報價大漲NOR Flash Contract Prices Surge256Mb以上高容量NOR Flash受AI伺服器拉貨帶動,下半年合約報價漲幅預估達 90%至 110%。Driven by AI server demand, contract prices for high-density…

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
電源缺料干擾POWER SUPPLY BOTTLENECK

MOSFET全線缺料壓抑伺服器電源放量 台達電第 3 季獲利遭機構下修Widespread MOSFET Shortages Stifle Server Power Shipments; Brokerages Cut Delta Electronics Q3 Earnings Forecasts

台達電受制於金氧半場效電晶體缺料使第 3 季預估營收降至 1,960.8 億元,機構相繼調降獲利預期。市場此前過度定價AI機櫃即刻變現節奏,忽略了上游成熟功率元件供應短缺對出貨動能的實質壓抑。Constrained by shortages of metal-oxide-semiconductor field-effect transistors, Delta Electronics saw its third-quarter revenue forecast lowered to NT$196.1 billion as brokerages downgraded earnings estimates. Markets previously priced in premature AI rack monetization while overlooking how mature-node power component bottlenecks could curb shipment momentum.

2026-09-16產業Industry電源與功率元件Power & Discretes
閱讀 →Read →
總經與市場結構Macro & Market Structure

原油破百美債殖利率升破 5% 全球央行面臨升息定價考驗Oil Tops $100 as 10-Year Treasury Yield Crosses 5%, Testing Central Bank Rate Hike Pricing

中東地緣衝突推升通膨黏性,美債 10 年期破 5%引發金融情勢收緊,美日台央行決策成焦點。Middle East geopolitical friction is fueling sticky inflation, while 10-year Treasury yields pushing past 5% tighten financial conditions, putting rate decisions from the Fed, BOJ, and Taiwan's central bank into sharp focus.

2026-09-16總經與市場Markets貴金屬與原物料Precious Metals & Commodities
閱讀 →Read →
AI供應鏈與產業變化AI Supply Chain & Industry Shifts

AI高壓架構與缺料推升零組件 載板與功率元件迎漲價循環High-Voltage AI Architectures and Component Shortages Fuel Price-Hike Cycle in Substrates and Power Silicon

伺服器單機功耗暴增帶動元件價值拉升,載板交期拉長至 70 週,供應鏈上游議價權全面走強。Surging per-server power consumption is boosting bill-of-materials values, pushing substrate lead times to 70 weeks and consolidating pricing power among upstream component suppliers.

2026-09-16科技Technology電源與功率元件Power & Discretes
閱讀 →Read →
海外連動與傳導Cross-Border Linkages

日經東證走勢背道而馳 升息預期推升金融股並壓抑軟銀Nikkei and Topix Diverge as Rate-Hike Bets Lift Japanese Lenders and Squeeze SoftBank

日本央行升息預期引發資產大搬風,銀行股勁揚帶動東證創高,科技權值股拖累日經回檔。Anticipation of Bank of Japan rate increases triggered a capital rotation, driving bank shares to lift the Topix to record highs while heavyweight tech stocks dragged down the Nikkei.

2026-09-16海外Global綜合General
閱讀 →Read →
風險與時間軸Risks & Horizons

超級央行週疊加荷姆茲危機 9 月系統性風險窗口全面開啟Super Central Bank Week Collides With Hormuz Crisis to Open Broad September Risk Window

荷姆茲海峽封鎖推升能源通膨,美日台央行決議集中出爐,台股歷史最弱月份面臨多重共振。Blockades in the Strait of Hormuz are stoking energy inflation just as the Fed, BOJ, and Taiwan central bank prepare policy decisions, exposing Taiwan equities to multiple headwinds during their historically weakest month.

2026-09-16風險Risk總經與利率Macro & Rates
閱讀 →Read →
本刊觀點Editor's View

短料瓶頸疊加折現率暴衝,共識撕裂的硬著陸考驗Valuation Deflation and Margin Cleanse Under High-Rate Repricing

市場態:立場:供應鏈長短料扭曲獲利時程且折現率衝擊未完全反映;信心:中偏高;否證:上游元件交期大幅縮短或能源引發的升息預期全面消退。Market State: Stance: Bearish on high-multiple growth plays lacking cash flow support. Conviction: Moderate, as hardware supply chain order books remain intact. Falsification: Foreign futures net short positions fall below 50,000 contracts and the 10-year U.S. Treasury yield retreats below 4.80%.

2026-09-16本刊觀點Editor's View綜合General
閱讀 →Read →