AHI Journal

2026 年 9 月 16 日 星期三Wednesday, September 16, 2026登入Log In訂閱Subscribe
共識分歧解析CONSENSUS FAULT LINES

南亞與聯電獲利預估分歧 賣方在成熟傳產與晶圓代工撕裂Earnings Divergence Widens for Nan Ya and UMC as Analysts Clash on Legacy Tech and Foundries

南亞 2026 年EPS落差達 66.9%,聯電亦有 3 成認知斷層,長約價格轉嫁成最大爭議點。A 66.9% gap in Nan Ya's 2026 EPS forecasts and a 30% divide on UMC highlight sharp disagreement over long-term contract pricing pass-through.
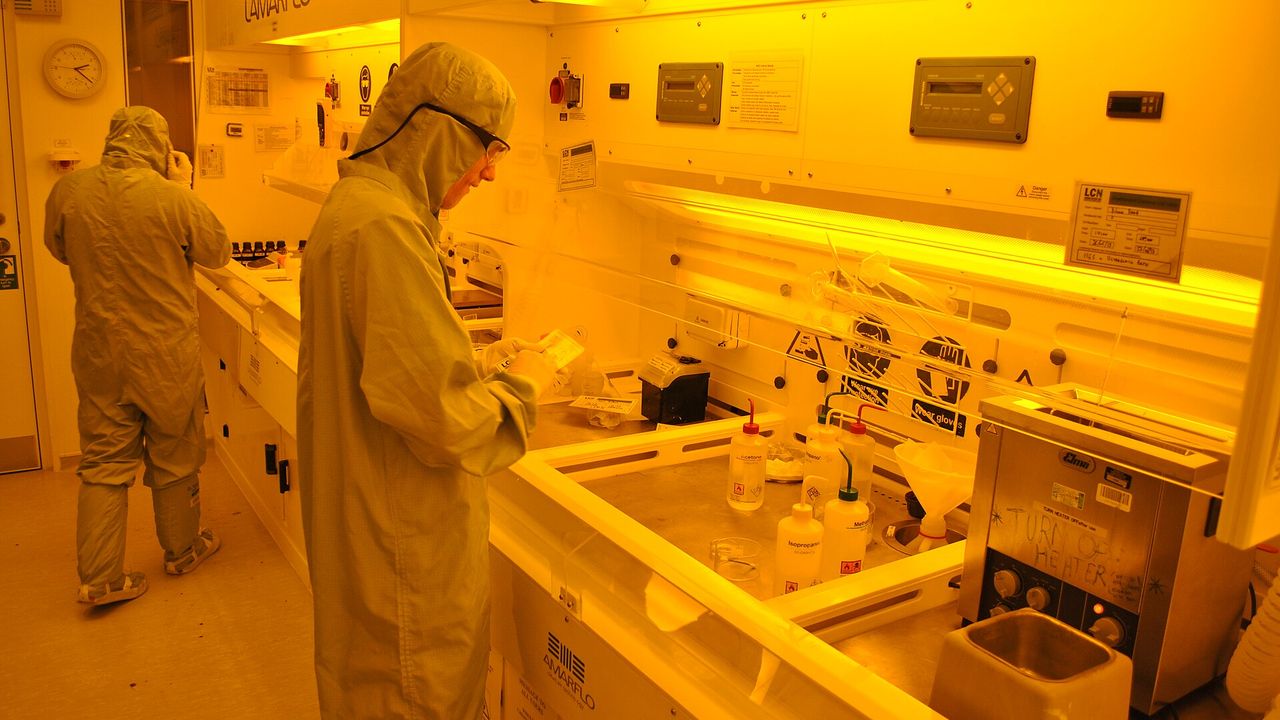
黃光微影無塵室裡的研究人員
圖:Photo: O. Usher(UCL MAPS) 授權:License: CC BY 2.0 來源:Source: Wikimedia Commons
2026 年 9 月 16 日 星期三Wednesday, September 16, 2026評等Ratings半導體Semiconductors免費版Free Edition
下一個可驗證時點Next checkpoint10/10(六)1303 南亞 9 月營收(10 日前申報)
到時候看What to check9 月營收年增率是否高於前 3 個月平均(前 3 個月平均年增 +35.9%);月增率有沒有延續,累計年增率的方向。

資本市場對成熟傳產與成熟製程晶圓代工的獲利前景出現罕見撕裂。研究機構對南亞 2026 年每股純益預估出現高達 66.9%的極端落差,聯電同年度的獲利預估差距亦超過 3 成。這場賣方共識的崩解,核心在於市場對AI外溢效應與產品漲價擴散速度的定價分歧。當資金試圖從純AI核心標的轉向二線供應鏈時,傳統業務的週期拖累與高階轉型的毛利拉動形成激烈拉鋸。這項認知落差不僅反映景氣復甦步調的不確定性,更凸顯定價權在成熟領域已成為多空對決的關鍵。Capital markets are witnessing an unusually stark fracture over the earnings outlook for mature traditional cyclicals and mature-node pure-play foundries. Wall Street research exhibits a staggering 66.9% dispersion in 2026 earnings-per-share forecasts for Nan Ya Plastics, while consensus projections for United Microelectronics Corp. (UMC) over the same fiscal year diverge by more than 30%. At the heart of this breakdown in sell-side consensus lies a fundamental valuation divide regarding the pace of AI spillover benefits and the diffusion rate of product price hikes. As capital rotates away from pure-play AI bellwethers toward second-tier supply chains, cyclical drags from legacy operations are locked in an intense tug-of-war against gross margin expansion driven by premium upgrades. This perceptual gap not only underscores deep uncertainty over the macroeconomic recovery's cadence, but also highlights that pricing power within mature operating environments has become the central fault line between bulls and bears.

新舊業務拉鋸加劇南亞預估分歧Old and New Line Struggles Deepen Nan Ya Forecast Chasm

彙整 9 家機構預估,南亞 2026 年每股純益區間橫跨 12.00 元至 20.03 元,分歧程度高居大型股前列。多空攻防核心,在於高階電子材料的增長動能能否完全覆蓋傳統石化事業的結構性虧損。南亞旗下的玻纖布、銅箔與環氧樹脂確實切入高階伺服器供應鏈,迎來材料升級帶動的報價提升;然而,傳統聚酯原料與塑膠加工業務的去化阻力依舊頑強。機構對其 2026 年營益率預測出現 11.7%至 13.54%的明顯鴻溝,顯示市場對雙軌轉型過程中獲利改善斜率的信心嚴重分化。A compilation of estimates from nine research houses reveals that Nan Ya's projected 2026 EPS spans a wide corridor between NT$12.00 and NT$20.03—among the highest degrees of analyst dispersion across mega-cap equities. The core debate centers on whether growth momentum in high-end electronic materials can fully offset structural losses across legacy petrochemical operations. Nan Ya's glass fabric, copper foil, and epoxy resin units have successfully penetrated high-end server supply chains, capturing upward price revisions fueled by material specification upgrades; nevertheless, channel destocking headwinds in commodity polyester feedstocks and plastic processing operations remain stubbornly entrenched. Institutions project a pronounced divergence in its 2026 operating margin, ranging from 11.7% to 13.54%, reflecting sharply divided institutional confidence regarding the trajectory of margin recovery amidst this dual-track transition.

賣方研究機構對南亞與聯電 2026 年EPS預估落差賣方研究機構對南亞與聯電 2026 年EPS預估落差Breakdown數字取自本文Figures quoted from this article01530 元南亞 2026 年EPS最低預估南亞 2026 年EPS最低預估12 元12 元南亞 2026 年EPS最高預估南亞 2026 年EPS最高預估20.03 元20.03 元聯電 2026 年EPS最低預估聯電 2026 年EPS最低預估6 元6 元聯電 2026 年EPS最高預估聯電 2026 年EPS最高預估7.86 元7.86 元賣方研究機構對南亞與聯電 2026 年EPS預估落差賣方研究機構對南亞與聯電 2026 年EPS預估落差Breakdown數字取自本文Figures quoted from this article01530 元南亞 2026 年E…南亞 2026 年EPS最低預估南亞 2026 年E…12 元12 元南亞 2026 年E…南亞 2026 年EPS最高預估南亞 2026 年E…20.03 元20.03 元聯電 2026 年E…聯電 2026 年EPS最低預估聯電 2026 年E…6 元6 元聯電 2026 年E…聯電 2026 年EPS最高預估聯電 2026 年E…7.86 元7.86 元
圖對應:以長條圖具體凸顯法人在成熟製程與傳產材料上的獲利預期巨大裂縫。讀法:這幾個數字取自本文、同一個單位放在同一把尺上比較,不是本刊面板另算的行情或營收。

晶圓代工定價遭遇中國產能阻力Foundry Pricing Power Encounters Chinese Capacity Wall

聯電的獲利預測同樣呈現賣方對成熟製程定價權的疑慮。6 家研究機構對其 2026 年每股純益給出 6.00 元至 7.86 元的離散區間,差幅達 31.0%,2027 年的差距更擴大至 7.00 元至 9.20 元。樂觀派認為 22 與 28 奈米製程稼動率回升,能引導代工長約價格反彈;保守派則緊盯中國競爭對手大舉開出的成熟產能,憂慮價格競爭將壓抑獲利空間。儘管聯電受惠AI外溢帶動特殊製程封測及電源IC需求,但推算至 2026 年相關營業額僅約 3 億美元,尚不足以徹底化解供過於求的陰霾。Earnings projections for UMC similarly reflect acute sell-side skepticism regarding mature-node foundry pricing power. Six research firms have issued a dispersed 2026 EPS target band ranging from NT$6.00 to NT$7.86, representing a 31.0% spread, with the projection gap widening further to NT$7.00 to NT$9.20 for 2027. The bull camp wagers that rebounding utilization across 22nm and 28nm platforms will orchestrate a recovery in long-term contract pricing. Conversely, conservative analysts point squarely at aggressive mature capacity expansions by Chinese mainland competitors, warning that price wars will severely compress margins. While UMC benefits from AI spillovers via specialized packaging and power management IC demand, projected 2026 revenues attributable to these vectors stand at merely US$300 million—far from sufficient to decisively dispel the overarching overhang of sector oversupply.

獲利轉化時程引發賣方定價分化Earnings Conversion Timelines Fracture Sell-Side Models

這種預估分歧揭示出二線受惠股在獲利轉化時間軸上的內在矛盾。不同於前期市場對先進AI供應鏈的單向樂觀,資金流向成熟傳產與代工環節時,必須面對龐大舊產能的現實牽制。無論是CCL上游材料或成熟特殊製程,廠商均難以完全脫離大宗商品市場的週期景氣。多方假設漲價循環能順利由高階向下滲透,快速修復整體獲利率;空方則主張傳統部門的供需失衡將大幅拖延毛利率回升節奏。雙方對「轉化速度」的認知落差,造成目前評價模型的巨大撕裂。This divergence in earnings projections exposes an inherent temporal friction in how second-tier beneficiaries convert top-line trends into bottom-line profits. Unlike the monolithic, one-way optimism previously showered upon advanced-node AI supply chains, capital allocations shifting into mature industrials and legacy foundries must confront the gravitational pull of massive legacy footprints. Whether producing copper-clad laminate raw materials or running mature specialty wafers, fabricators cannot cleanly decouple from broader commodity-market cycles. Bulls predicate their models on the assumption that premium price cycles will seamlessly cascade down to lower tiers, orchestrating a rapid repair of corporate-wide margins; bears argue that persistent supply-demand imbalances in legacy segments will substantially delay margin inflection. Divergent assumptions regarding this conversion velocity have resulted in a profound tear across prevailing valuation frameworks.

本刊判斷,成熟傳產與晶圓代工的評價修復已進入基本面嚴格檢驗期。接下來市場焦點將落在管理階層釋出的代工報價走勢,以及電子材料部門實質獲利率能否持續向上擴張。只有當長約轉嫁能力明確轉化為營益率改善時,多空分歧的獲利模型才可能重新靠攏。In this publication's assessment, valuation recoveries across mature industrials and legacy foundries have entered an unforgiving phase of fundamental scrutiny. Market focus will pivot squarely toward foundry contract pricing trajectories disclosed by management and whether sustained margin expansion in electronic materials segments can hold. Only when contractual pricing power translates into verifiable operating margin improvements will the currently fractured valuation models reconverge.

訂閱版提供 2 檔標的各機構獲利預估矩陣、營益率門檻拆解與法說會觀察指標。The subscriber edition provides institutional earnings estimate matrices for both tickers, operating margin threshold analyses, and earnings call surveillance indicators.

閱讀訂閱版Read the subscriber edition

本刊結論:Our verdict: 立場:偏空中階成熟製程與傳產轉型獲利共識;信心:中,南亞傳統塑化去化瓶頸及聯電面臨成熟製程價格競爭皆壓抑獲利轉化;否證:若南亞第 4 季電子材料部門營益率突破 15%,且聯電 2026 年EPS達到 7.86 元,則本判斷不成立。

接下來看什麼What to watch next

  1. 南亞第 4 季電子材料部門營益率:門檻數字為 15%,突破 15%則樂觀派獲利預估成立,低於或等於 15%則不成立。
  2. 聯電第 4 季晶圓平均出貨單價(ASP)季增率:門檻數字為 1%,若低於 1%則悲觀派 6.00 元EPS防守假設成立,達到或高於 1%則不成立。
  3. 聯電 2026 年來自人工智慧的營業額:門檻數字為 3 億美元,達標且 2026 年EPS達 7.86 元為多方假設成立,低於 3 億美元且EPS趨向 6.00 元則多方假設不成立。

風險燈號Risk Dashboard

總經政策Macro Policy
美債 10 年期殖利率升破 5.04%,布蘭特原油逼近 109 美元,FOMC升息預期壓抑估值。The 10-year Treasury yield climbed past 5.04% and Brent crude neared USD 109, as FOMC rate-hike expectations weighed on valuations.
市場流動性Market Liquidity
大盤成交量縮至 6,034 億元窒息量,外資台指期空單破 8.3 萬口,漢測IPO凍資逾 8,600 億元。Turnover dried up to NT$603.5 billion, foreign TX shorts exceeded 83,000 contracts, and Han-Test's IPO froze over NT$860.0 billion.
產業敘事Industry Narrative
研華訂單出貨比維持 1.44,伺服器高壓直流架構與邊緣AI落地明確,基本面訂單未見砍單。Advantech's book-to-bill remained at 1.44; high-voltage direct current architectures and edge AI rollouts showed no order cuts.
時間週期Time Horizon
9 月歷史季節性偏弱,期選月結算疊加四巫日與全球超級央行週,市場波動進入極端區。September seasonality remains historically soft; monthly futures settlement, Quadruple Witching, and central bank meetings heighten volatility.

要聞速覽What’s News看完整內容 →full story →

市場Markets

外資 4 日賣超逾 2,000 億Foreign Outflows Top NT$200B Over Four Days外資 9 月 15 日賣超台股 626.99 億元,4 個交易日內累計調節 2,272.67 億元,大盤成交量縮至 6,034 億元並測試季線支撐。Foreign institutional investors offloaded NT$62.7 billion in Taiwan equities on Sept.

期貨淨空單居 8 萬口高檔Futures Net Shorts Hold Near 80,000 Contracts面對合約結算與聯準會利率會議雙重考驗,外資微幅加碼 565 口台指期空頭部位,留倉總量攀至 83,223 口,避險姿態依然嚴密。Ahead of contract settlement and the Fed policy decision, fo…

日圓期貨轉為淨多單Yen Futures Swing to Net LongCFTC最新數據顯示日圓投機期貨轉為淨多單 1.08 萬口,擺脫過往淨空單 18.4 萬口的極端狀態,減緩套利平倉壓力。Latest CFTC figures show speculative yen positions flipping …

產業與企業Industry & Companies

台達電發行 15 億美元ECBDelta Electronics Issues USD 1.5B in ECBs為籌措泰國產線擴充及高壓直流電架構開發資金,台達電子旗下單位拍板籌資 15 億美元,於境外釋出可交換公司債券。Delta Electronics moved to raise USD 1.5 billion via offshor…

金控前 8 月獲利創同期新高Financial Holdings Set Record 8-Month Earnings台灣 13 家上市金控前 8 月自結累計稅後淨利達 5,789 億元,金融資產評價利益回升強化明年配息基礎。Thirteen listed Taiwanese financial holding firms posted com…

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
產業透視INDUSTRY FOCUS

矽晶圓缺口預估擴至 24% 漢測凍資 8,600 億引爆產能卡位Silicon Wafer Deficit Projected to Widen to 24%; Han-Test IPO Freezes NT$860B as Capacity Race Ignites

先進製程擴產推動全球矽晶圓供需缺口逐年擴大至 2028 年底的 24%,漢測IPO申購更凍結逾 8,600 億元資金。這項關鍵供需吃緊推翻了市場對AI投資步調放緩的悲觀論調,證實半導體上游產能不足正自晶圓延伸至測試與材料端。Advanced process expansions are projected to widen the global silicon wafer supply deficit to 24% by late 2028, while the IPO subscription for Han-Test froze over NT$860.0 billion. The acute supply crunch pushes back against market skepticism over an AI investment slowdown, confirming that semiconductor bottleneck pressures are migrating from foundries into testing and materials.

2026-09-16總經與市場Markets半導體Semiconductors
閱讀 →Read →
中國宏觀分化CHINA MACRO DIVERGENCE

中國 8 月房地產投資衰退近 2 成 高技術製造年增 5 成撐大局China's August Property Investment Drops Nearly 20% While High-Tech Manufacturing Surges 50%

固定資產投資降幅擴至 7.2%,但電子電路投資暴增 58.8%,外強內弱格局固化。Fixed-asset investment contracted 7.2%, but electronic circuit spending jumped 58.8%, cementing a deep divide between external resilience and domestic weakness.

2026-09-16總經與市場Markets綜合General
閱讀 →Read →
邊緣算力落地EDGE AI DEPLOYMENT

研華接單出貨比達 1.44 邊緣運算打破零組件缺料緊箍咒Advantech Book-to-Bill Hits 1.44 as Edge Computing Navigates Component Shortages

工業電腦受惠工廠自動化與實體AI落地,全額預付訂單推升全年營收挑戰 1,000 億元大關。Industrial PC makers are benefiting from factory automation and physical AI, with fully prepaid orders steering full-year revenue toward the NT$100.0 billion mark.

2026-09-16科技Technology綜合General
閱讀 →Read →
日圓期貨結構翻轉YEN FUTURES REVERSAL

CFTC日圓轉淨多單 1.08 萬口 軟銀能源上市抵禦套利平倉風暴CFTC Yen Turns Net Long by 10,800 Contracts; SoftBank Energy Listing Cushions Unwind Pressures

投機空單自 18 萬口歷史極端徹底清空,日股在日銀升息前夕展現抗震韌性。Speculative shorts completely cleared out from record extremes of 180,000 contracts, lending resilience to Japanese equities ahead of the Bank of Japan decision.

2026-09-16海外Global台股盤面與籌碼Taiwan Market & Flows
閱讀 →Read →
防禦型資產轉向DEFENSIVE ROTATION

金控前 8 月大賺 5789 億元 壽險OCI評價與高股息築起安全邊際Financial Holdings Post NT$578.9B in 8-Month Profit as Insurers' OCI and High Yields Build Safety Margin

資本利得推升獲利年增近 6 成,玉山金富邦金領跑,高殖利率成為震盪市避風港。Capital gains boosted profit nearly 60% year over year, led by E.Sun Financial and Fubon Financial, making high dividend yields a haven amid volatility.

2026-09-16風險Risk總經與利率Macro & Rates
閱讀 →Read →
本刊觀點Editor's View

在 8 萬口空單與 6,000 億窒息量間尋找定價錨Seeking a Valuation Anchor Between 80,000 Short Contracts and NT$600B Liquidity Drought

市場態:立場:中性對加權指數季線支撐與期貨結算震盪;信心:中,受制於外資 4 日賣超逾 2,000 億與 8.3 萬口期貨空單;否證:加權指數收盤跌破 44,500 點季線且量能持續低於 5,500 億元。Market State: Stance: Neutral on TAIEX quarterly moving average support and futures settlement swings; Confidence: Medium, constrained by foreign institutional investors selling over NT$200B in four sessions and 83,000 futures short contracts; Falsification: TAIEX closes below the 44,500-point quarterly line alongside turnover persisting under NT$550.0 billion.

2026-09-16本刊觀點Editor's View台股盤面與籌碼Taiwan Market & Flows
閱讀 →Read →