AHI Journal

2026 年 8 月 24 日 星期一Monday, August 24, 2026登入Log In訂閱Subscribe
缺料通膨的下一站Shortage Inflation Moves Downstream

當龍頭也要漲價:記憶體的帳單開始往終端移動When the Market Leader Raises Prices: Memory Costs Land on the End Customer

AI 伺服器明年起漲 15%。這不是一家公司的定價決定,是缺料通膨第一次走完「零組件→整機→客戶」的全程。AI server prices are slated to rise 15% next year. This is no single firm's pricing decision—it marks the first time shortage inflation has completed the full journey from component to rack to buyer.
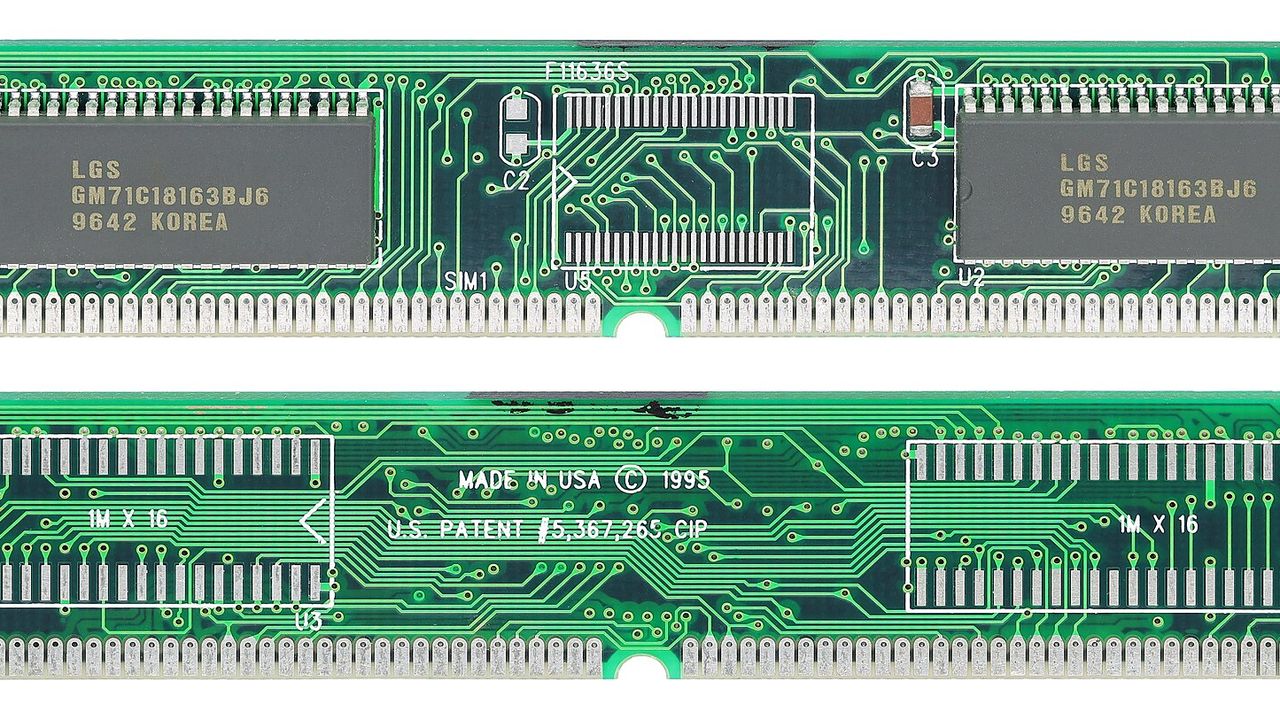
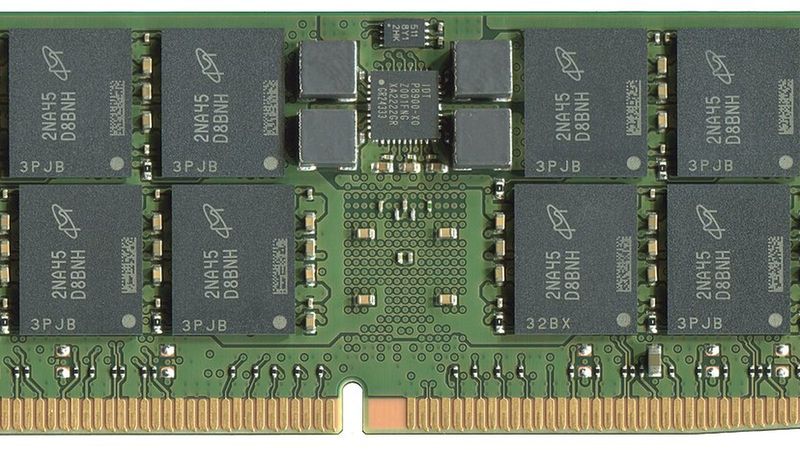
memory(記憶體模組實體正反面)
圖:Photo: Mister rf 授權:License: CC BY-SA 4.0 來源:Source: Wikimedia Commons
第 3 期Issue No. 32026 年 8 月 24 日 星期一Monday, August 24, 2026免費版Free Edition

人工智慧加速器龍頭傳出將自明年起調漲伺服器售價 15%,直面記憶體成本暴漲的壓力。這項調整最關鍵的意涵,在於缺料引發的成本推升,正式走完從上游材料、核心零組件到整機終端採購的完整傳導鏈。過去 1 季,高頻寬記憶體與伺服器記憶體的報價狂飆,先侵蝕零組件廠的利潤與營運資金,如今壓力由龍頭廠商直接向大型雲端服務商開刀。這不再只是單一硬體廠商的定價策略,而是整個AI硬體基礎建設成本結構全面上移的標誌性轉折。人工智慧加速器龍頭傳出將自明年起調漲伺服器售價 15%,直面記憶體成本暴漲的壓力。這項調整最關鍵的意涵,在於缺料引發的成本推升,正式走完從上游材料、核心零組件到整機終端採購的完整傳導鏈。過去 1 季,高頻寬記憶體與伺服器記憶體的報價狂飆,先侵蝕零組件廠的利潤與營運資金,如今壓力由龍頭廠商直接向大型雲端服務商開刀。這不再只是單一硬體廠商的定價策略,而是整個AI硬體基礎建設成本結構全面上移的標誌性轉折。

轉嫁鏈走完全程考驗雲端業者支出轉嫁鏈走完全程考驗雲端業者支出

將整機售價調高 15%的決策,表面上穩固了加速器龍頭的毛利率,實質上卻把成本壓力推向資本支出龐大的第一線雲端服務商。儘管主要科技巨頭已提前與記憶體大廠簽訂長期供應合約,享有一定比例的價格保護屏障,但隨著算力擴建規模持續膨脹,超出長約配額的追加採購量,必須全額承受現貨市場的昂貴代價。在高頻寬記憶體產能吃緊的局面預計延續至 2027 年的背景下,終端雲端業者的採購成本走高已成定局。目前各大巨頭並未縮減資本支出,但在每單位算力建置成本跳升之後,採購動能能否持續無視回報率地無上限擴張,將是供應鏈下一個必須面對的考驗。將整機售價調高 15%的決策,表面上穩固了加速器龍頭的毛利率,實質上卻把成本壓力推向資本支出龐大的第一線雲端服務商。儘管主要科技巨頭已提前與記憶體大廠簽訂長期供應合約,享有一定比例的價格保護屏障,但隨著算力擴建規模持續膨脹,超出長約配額的追加採購量,必須全額承受現貨市場的昂貴代價。在高頻寬記憶體產能吃緊的局面預計延續至 2027 年的背景下,終端雲端業者的採購成本走高已成定局。目前各大巨頭並未縮減資本支出,但在每單位算力建置成本跳升之後,採購動能能否持續無視回報率地無上限擴張,將是供應鏈下一個必須面對的考驗。

代工模式轉向寄售化解毛利稀釋代工模式轉向寄售化解毛利稀釋

面對關鍵零組件價格飆漲,台灣伺服器代工廠採取了防禦性的財務工程應對。為了避免高單價零組件直接計入銷貨成本而大幅稀釋整體毛利率,代工業者已主動與客戶協商,將部分專案由原本的買賣斷模式切換為寄售模式。在此模式下,昂貴的處理器與記憶體不進入代工廠自身的進銷存帳目,僅認列組裝與系統加工的附加價值。這項營運模式的轉換,本質上是資產負債表與營收結構的重整,而非底層獲利能力的實質惡化。這意味著觀察硬體組裝族群時,傳統的毛利率指標將逐漸失去跨期比較的參考價值,市場分析的核心焦點必須轉向營業利益率與絕對營業利益金額。面對關鍵零組件價格飆漲,台灣伺服器代工廠採取了防禦性的財務工程應對。為了避免高單價零組件直接計入銷貨成本而大幅稀釋整體毛利率,代工業者已主動與客戶協商,將部分專案由原本的買賣斷模式切換為寄售模式。在此模式下,昂貴的處理器與記憶體不進入代工廠自身的進銷存帳目,僅認列組裝與系統加工的附加價值。這項營運模式的轉換,本質上是資產負債表與營收結構的重整,而非底層獲利能力的實質惡化。這意味著觀察硬體組裝族群時,傳統的毛利率指標將逐漸失去跨期比較的參考價值,市場分析的核心焦點必須轉向營業利益率與絕對營業利益金額。

矽晶圓調漲點燃材料端供給約束矽晶圓調漲點燃材料端供給約束

這場成本推升浪載並未停留在記憶體領域,上游基礎材料端也出現連鎖反應。時隔 3 年多,矽晶圓產業近期傳出全面調漲報價,涵蓋 6 吋、8 吋至 12 吋晶圓,調幅約在 1 成水準,且不論現貨或長約皆出現一致性的價格上行趨勢。若加上先前已經率先展開漲勢的玻纖布與高階銅箔基板,材料端的調價已經在 3 個高度獨立的供應環節同時確立。這波擴散清楚揭示當前通膨並非來自各領域終端需求的同步暴增,而是源自先進製程與關鍵產能的供給剛性約束。當上游材料大廠依仗緊俏產能重啟定價權,整個半導體中游製造體系的製造成本勢必將面臨層層墊高的全新常態。這場成本推升浪載並未停留在記憶體領域,上游基礎材料端也出現連鎖反應。時隔 3 年多,矽晶圓產業近期傳出全面調漲報價,涵蓋 6 吋、8 吋至 12 吋晶圓,調幅約在 1 成水準,且不論現貨或長約皆出現一致性的價格上行趨勢。若加上先前已經率先展開漲勢的玻纖布與高階銅箔基板,材料端的調價已經在 3 個高度獨立的供應環節同時確立。這波擴散清楚揭示當前通膨並非來自各領域終端需求的同步暴增,而是源自先進製程與關鍵產能的供給剛性約束。當上游材料大廠依仗緊俏產能重啟定價權,整個半導體中游製造體系的製造成本勢必將面臨層層墊高的全新常態。

本刊的判斷是,由供給約束驅動的漲價潮本質上是高度分化的雙刃劍。握有稀缺產能與關鍵技術專利的源頭供應商將享受利潤擴張,而夾在中間、缺乏議價權的下游組裝與中小型系統廠將承擔利潤壓縮的代價。接下來的觀察重心,在於終端雲端巨頭在面臨算力硬體全面漲價時,是否開始調整伺服器拉貨節奏,以及零組件業者能否將上游材料的漲幅完整推給下游客戶。本刊的判斷是,由供給約束驅動的漲價潮本質上是高度分化的雙刃劍。握有稀缺產能與關鍵技術專利的源頭供應商將享受利潤擴張,而夾在中間、缺乏議價權的下游組裝與中小型系統廠將承擔利潤壓縮的代價。接下來的觀察重心,在於終端雲端巨頭在面臨算力硬體全面漲價時,是否開始調整伺服器拉貨節奏,以及零組件業者能否將上游材料的漲幅完整推給下游客戶。

訂閱版另有完整供應鏈受惠與受害族群深入剖析,以及代工廠營運模式轉變後的獲利防禦力評估。The subscriber edition features an exhaustive mapping of supply-chain winners and losers alongside a stress test of ODM defensive earnings power under revised commercial terms.

閱讀訂閱版Read the subscriber edition

完整分析見深度專題〈Full analysis in the feature: 漲價 15% 與寄售模式:記憶體通膨轉嫁走完全程〉 →

風險燈號Risk Dashboard

CSP資本支出與設備投資CSP Capex and Equipment Buildout
第一線業者仍積極加碼,伺服器機櫃出貨目標未下修Tier-one hyperscalers continue expanding investments; server rack deployment targets remain intact
記憶體通膨傳導Memory Inflation Transmission
龍頭調漲伺服器售價 15%,成本壓力進入終端Market leader hikes server prices 15%, shifting cost burdens onto enterprise buyers
聯準會與通膨Federal Reserve and Inflation
長天期殖利率高位震盪,本週央行年會與核心PCE為裁決點Long-term yields range-bound near highs; Jackson Hole and core PCE serve as arbitration points
外資期貨淨空單Foreign Net Short Futures
82,594 口未隨現貨買超回補,屬對沖式買盤82,594 short contracts left open despite spot buying, indicating institutional hedging
地緣政治與油價Geopolitics and Crude
制裁議題未解,油價維持高檔Sanctions remain unresolved, keeping crude prices elevated
材料供給缺口Raw Material Deficits
矽晶圓、玻纖布、銅箔基板同時吃緊,下游轉嫁能力待驗證Silicon wafers, glass cloth, and CCL face simultaneous squeezes; downstream pass-through power remains unproven
當沖與籌碼溫度Day Trading and Market Temperature
週線收黑、量縮,強勢族群集中在航運與記憶體Weekly candle closes lower on lighter turnover; leadership narrows to shipping and memory

要聞速覽What’s News看完整內容 →full story →

市場Markets

運價連 4 週反彈但評等仍是中立Freight Rates Extend Rebound to Four Weeks but Stance Remains Neutral8 月 21 日上海出口貨櫃運價指數 3,409.63 點、週增 1.62%,美東線 9,700 美元、美西線 6,765 美元,歐洲線則週減 3.5%。The Shanghai Containerized Freight Index rose 1.62% week-on-week to 3,409.63 on Aug.

台股週線跌 586 點TAIEX Sheds 586 Points on the Week上週五加權指數收 45,224.29 點、上漲 0.65%,但 1 週合計下跌 586 點;上市公司的市值總額同期少了 1.9 兆元,降到 147.8 兆元。The Taiwan Stock Exchange Capitalization Weighted Stock Inde…

外資回頭買、期貨空單沒回補Foreign Investors Buy Spot Without Covering Short Futures上週五外資現貨買超 283.05 億元、三大法人合計買超 331.05 億元;但外資台指期淨空單仍有 82,594 口,較前 1 日再增。Foreign institutions logged a net buy of NT$28.3 billion in …

美國 8 月採購經理人指數跳升至 56US August Composite PMI Accelerates to 56服務業由 54.1 升到 56.8,優於市場預期,減緩了成長動能轉弱的疑慮;長天期公債殖利率仍高位震盪,資金轉向醫療與原物料等防禦族群。The services gauge rose from 54.1 to 56.8, topping consensus estimates and soothing growth concerns;

本週三個裁決點Three Decision Points Arrive This Week人工智慧加速器龍頭財報、全球央行年會與美國核心個人消費支出物價,將在同一週內揭曉。Earnings from the premier AI accelerator leader, the Jackson…

產業與企業Industry & Companies

本期其他文章More From This Issue

4 篇4 more
從零組件到系統整合From Components to Systems

毛利率 30.8%:貿聯轉系統整合,能見度到 2027Gross Margin Hits 30.8%: BizLink Pivots to Systems Integration with Visibility into 2027

第 2 季每股盈餘 15.28 元。真正的變化不在數字,在角色——半導體設備線束業務已從單一零件供應商升級為系統整合廠商。Second-quarter EPS reached NT$15.28. The structural shift lies in role rather than numbers: semiconductor equipment cabling has evolved from piece parts into turnkey integration.

2026-08-24個股Companies半導體Semiconductors
閱讀 →Read →
本刊觀點Editor's View

同一週要交 3 份考卷Three Exam Papers in a Single Week

市場態:武裝態——加權指數收 45,224.29 點、週跌 586 點,量縮價穩;外資現貨買超但期貨淨空單未回補,長天期殖利率與油價維持偏緊。Market State: Defensive posture—TAIEX closed at 45,224.29, down 586 points on the week amid contracting volume and stabilizing price; foreign funds net-bought spot but left short futures unhedged, while long-term yields and crude remain firm.

2026-08-24本刊觀點Editor's View貴金屬與原物料Precious Metals & Commodities
閱讀 →Read →

深度專題免費預覽Features: Free Previews

全部專題 →All features →
圖片Photo:Wikimedia Commons・PantheraLeo1359531・CC BY 4.0
15%15%伺服器漲價幅度Server Price Increase
轉嫁鏈的最後一哩The Final Mile of Cost Pass-Through

漲價 15% 與寄售模式:記憶體通膨轉嫁走完全程15% Price Hikes and Consignment Models: Memory Inflation Completes Its Pass-Through

加速器龍頭通知大客戶明年伺服器售價調高 15%;台系代工廠則把高單價料件搬出自己的帳。同一件事的兩端,決定了未來幾季怎麼讀這些公司的毛利率。A leading AI accelerator maker informed major clients of a 15% price increase on next year's servers, while Taiwanese contract manufacturers are moving high-priced components off their own books. Both sides of the same shift will redefine how investors read their gross margins over the coming quarters.

2026-08-24科技Technology記憶體Memory
閱讀 →Read →
圖片Photo:Wikimedia Commons・Wikimedia Commons contributor・CC BY 2.5
拉長至 6 個月Extended to 6 months產品交期Product Lead Times
題材看展覽,訂單看交期Trade Shows Sell the Narrative, Lead Times Tell the Truth

交期 6 個月:自動化滿載靠的是光通訊測試設備Six-Month Lead Times: Optical Testing Powers the Automation Boom

展場的主角是人形機器人,量產元年被指向 2027 年。但現在讓傳動元件廠加班滿載的,是另一條線——而交期是這條線唯一誠實的溫度計。Humanoid robots dominate trade show floors, with mass production pegged for 2027. Yet the factory lines driving suppliers to full capacity today belong to an entirely different sector—and lead times remain the only reliable thermometer.

2026-08-24科技Technology光通訊與 CPOOptical & CPO
閱讀 →Read →
圖片Photo:Wikimedia Commons・Cepheiden・CC BY-SA 3.0
6/8/12 吋皆約 1 成Around 10% across 6-, 8-, and 12-inch wafers調漲共識Price-Hike Consensus
等了 3 年的漲價A Three-Year Wait for Price Hikes

六吋到十二吋一起漲 1 成:稼動率與一場火災決定Across-the-Board 10% Hike from 6- to 12-Inch: Utilization and a Fire Tip the Balance

矽晶圓時隔 3 年多集體調漲。成因幾乎全在供給側——當一個產業的稼動率接近滿載,任何單點事故都會直接變成價格事件。Silicon wafer makers are raising prices collectively for the first time in more than three years. The catalyst is almost entirely supply-side: with industry utilization near full capacity, a single operational disruption becomes an immediate pricing event.

2026-08-24科技Technology半導體Semiconductors
閱讀 →Read →

市場快照Market Snapshot

市場快照:當期漲跌幅(僅列同口徑可比較者)當期漲跌幅(僅列同口徑可比較者)Change for the session (comparable rows only)−1%+1%0加權指數TAIEX+0.65%45,224.2945,224.29櫃買指數TPEx Index−0.69%387.27387.27費城半導體指數費城半導體指數PHLX Semiconductor I…−0.51%11,740.3711,740.37道瓊工業指數道瓊工業指數Dow Jones Industrial…+0.98%53,277.0153,277.01市場快照:當期漲跌幅(僅列同口徑可比較者)當期漲跌幅(僅列同口徑可比較者)Change for the session (comparable rows only)−1%+1%0加權指數TAIEX+0.65%45,224.2945,224.29櫃買指數TPEx Index−0.69%387.27387.27費城半導體…費城半導體指數PHLX Semico…−0.51%11,740.3711,740.37道瓊工業指數道瓊工業指數Dow Jones I…+0.98%53,277.0153,277.01
加權指數TAIEX45,224.2945,224.29+290.55(+0.65%),全週−586 點+290.55 (+0.65%), −586 points on the week
櫃買指數TPEx Index387.27387.27−0.69%,近 5 日−3.41%−0.69%, −3.41% past five sessions
費城半導體指數PHLX Semiconductor Index11,740.3711,740.37−0.51%,近 5 日−5.45%−0.51%, −5.45% past five sessions
道瓊工業指數Dow Jones Industrial Average53,277.0153,277.01+0.98%(標普+0.43%、那斯達克+0.43%)+0.98% (S&P 500 +0.43%, Nasdaq +0.43%)

兩種讀法,一份判斷Two ways to read. One judgment.

每個交易日早晨,把數十份券商研究讀成一份有觀點的報紙。免費版每個交易日更新:電子報敘事、市場快訊、每天 3 篇新聞全文與籌碼摘要。訂閱版開放全部新聞、日報與深度專題全文,以及籌碼快訊完整版與檢查點兌現表。Every trading morning, dozens of broker research notes read into one newspaper with a point of view. Free readers get the edition’s narratives, the Market Brief, 3 news articles a day in full and a flows summary; subscribers get every news article, the full daily and features, the full flows desk and the checkpoint scorecard.

免費層Free

NT$ 0
  • 免費電子報:每個交易日一期:每篇文章的長版敘事(約 1,000 字)、要聞速覽與風險燈號Free edition: one issue every trading day — a long-form narrative of each article (about 1,000 words), What’s News and the risk dashboard
  • 市場快訊:當日要聞速覽全文、市場快照與漲跌圖Market Brief: the day’s What’s News in full, the market snapshot and a movers chart
  • 每天 3 篇新聞全文:免費電子報 1 篇、政治新聞 1 篇、台股標的快訊 1 篇;其餘篇目看得到標題與導言3 news articles a day in full: the free edition, 1 politics and 1 Taiwan stock briefs; headlines and summaries for the rest
  • 標的快訊數據看板:營收速報、今日公布營收、公司速覽Stock data boards: revenue flash, today’s revenue releases and company snapshots
  • 籌碼快訊摘要:三大法人、投信投本比、族群買賣超排名(前 10 名)Flows summary: institutional, investment-trust and sector net-buying rankings (top 10)
  • 導讀與存檔:深度專題導讀、個股頁(走勢與月營收)、週回顧Briefings and archive: feature briefings, stock pages (price and monthly revenue) and the weekly review
看免費版See the free edition

訂閱層Subscriber

NT$ 99/月・每天不到 4 元NT$ 99 / month · under NT$4 a day

免費層全部內容,另加:Everything in Free, plus:

  • 日報全文:頭條與 5 篇專題、本刊觀點與市場態判定、評等動向板、行事曆、檢查點The full daily: the lead and five features, Editor’s View with the market-state call, ratings board, calendar and checkpoints
  • 深度專題全文:數據表、時間序列與附錄Features in full: data tables, time series and appendices
  • 全部新聞整合報導:政治、總經、科技、台股標的快訊每一篇全文,附本刊觀點與接下來看什麼Every news article in full: politics, macro, technology and Taiwan stock briefs, each with our view and what to watch next
  • 籌碼快訊完整版:贏家分點買盤與優先順序、成本與連續買超、分點檔案與搜尋、優質大戶分點、ETF 買賣超與申購贖回、每日籌碼重點整理The full flows desk: winning-branch buying with a priority order, cost and buying streaks, branch profiles and search, notable large-trader branches, ETF flows and creations/redemptions, and a daily flows digest
  • 每週檢查點兌現表:本刊寫下的檢查點逐條對帳Weekly checkpoint scorecard: every checkpoint we wrote, reconciled line by line
  • 帳號:同一瀏覽器登入一次即可,閱讀時自動延長登入、免重複收信;同時最多 3 台裝置,可用 Email 登入碼或 Passkey(指紋/臉部辨識)登入Account: sign in once per browser and stay signed in as you keep reading, with no repeat emails; up to 3 devices at a time, using an emailed code or a passkey (fingerprint or face)
立即訂閱Subscribe now已訂閱?登入Already a subscriber? Log in

以電子郵件建立訂閱,開通後每月續期;可隨時於帳戶頁終止,終止後不再收費。Subscribe with your email. It renews each month, and you can end it any time from your account page.付款前會請你勾選同意Before payment you will be asked to agree to the 使用條款terms of use and the 免責聲明與資料授權說明disclaimer and data licence.

本刊為研究整理與觀點分享,非投資建議;作者非持牌投資顧問;價格基準日為 2026-08-21。This publication is research synthesis and commentary, not investment advice; the author is not a licensed investment adviser. Prices as of 2026-08-24.