AHI Journal
華邦電以 11.2 億美元收購英飛凌業務 全球NOR市佔躍升 34%Winbond to Buy Infineon Unit for $1.12B, Pushing Global NOR Share to 34%
透過吸收海外車用驗證與高階技術,華邦電將編碼型快閃記憶體版圖擴大至全球第一。By integrating automotive qualifications and premium tech, Winbond will scale its NOR flash presence to become the world's largest supplier.
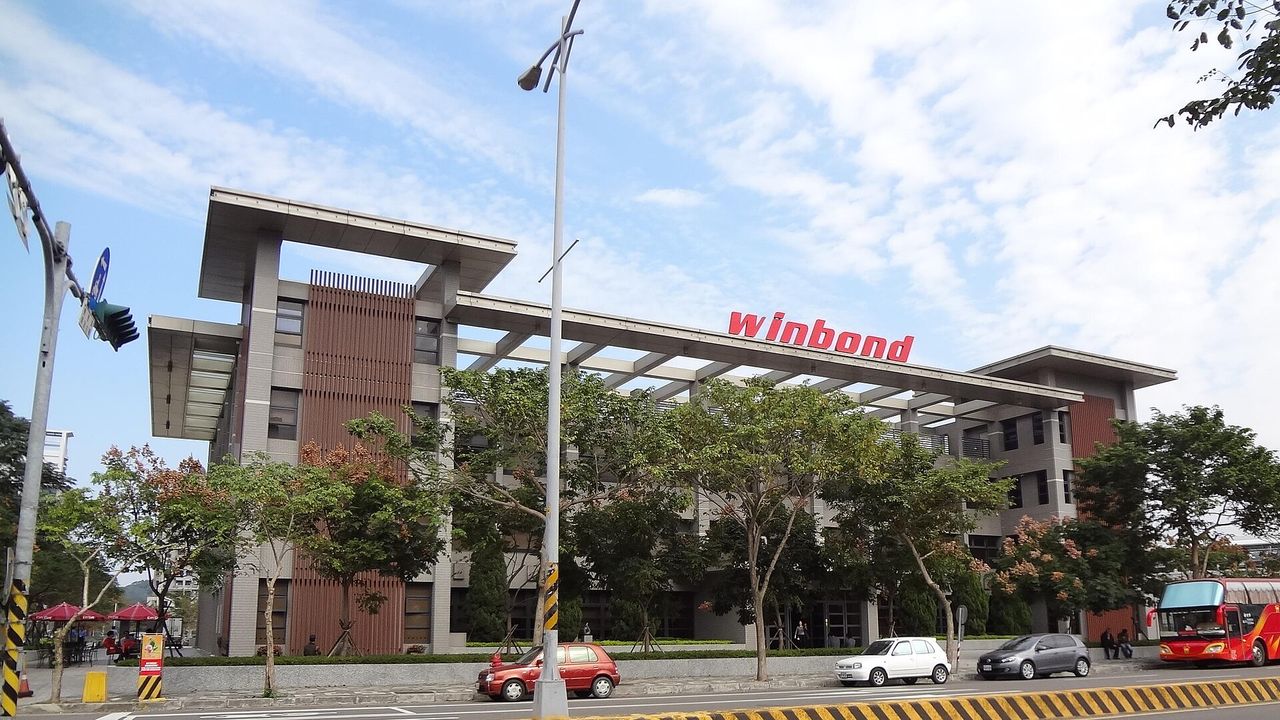
華邦電子斥資 11.2 億美元收購英飛凌旗下的NOR快閃記憶體與鐵電隨機存取記憶體(F-RAM)業務,為全球記憶體產業投下震撼彈。這筆預計於 2027 年下半年完成交割的併購案,將使華邦電在全球NOR Flash的市佔率從 23%躍升至 34%以上,一舉確立全球第一的龍頭寶座。這項交易發生的關鍵時刻,正值AI伺服器架構與車用電子對高容量韌體儲存需求全面爆發的轉折點。透過直接接收國際一線車廠客戶與高階非揮發性記憶體專利,華邦電不僅重塑了編碼型記憶體的定價話語權,更在全球半導體地緣政治與供應鏈重組中,建立了競爭對手難以跨越的規模壁壘。Winbond Electronics has sent shockwaves through the global memory industry with an agreement to acquire Infineon Technologies' NOR Flash and ferroelectric RAM (F-RAM) business for $1.12 billion. Scheduled to close in the second half of 2027, the buyout will elevate Winbond's global NOR Flash market share from 23% to more than 34%, firmly crowning it the undisputed global market leader. The transaction arrives at a pivotal juncture, coincided by an explosive expansion in demand for high-capacity firmware storage driven by AI server architectures and automotive electronics. By directly absorbing top-tier international automaker client relationships and advanced non-volatile memory patents, Winbond not only reshapes its pricing leverage in code storage memory but also erects formidable scale barriers that rivals will struggle to overcome amidst semiconductor supply chain realignments.
跨越認證高牆奪取高階定價權Bypassing Certification Hurdles for High-End Pricing Clout
高容量編碼型快閃記憶體的供需缺口,是這場收購的核心驅動力。隨著人工智慧伺服器運算節點升級與車載電子普及,市場對 256Mb以上高階NOR Flash需求出現爆發式增長,推動合約報價走揚。然而汽車領域的驗證流程向來嚴苛,新進業者往往需歷經數年審查才能切入供應鏈。英飛凌該業務承襲自過去的Spansion體系,具備極為完整的歐美車廠客戶與專利。華邦電藉由收購直接取得現成認證與F-RAM技術,省下至少 3 年的冗長驗證期,在供需緊繃的關鍵週期精準卡位,掌控了高階市場的供應與議價主導權。The widening supply-demand imbalance in high-density code storage flash memory serves as the core catalyst for this buyout. As computing nodes in AI servers undergo generational upgrades and automotive electronics proliferate, market demand for high-end NOR Flash above 256Mb has surged, driving contract prices higher. Yet the automotive qualification cycle is notoriously grueling, often requiring prospective entrants to undergo years of rigorous vetting before breaking into the supply chain. Infineon's unit—originating from the Spansion heritage—comes equipped with an extensive roster of European and American automotive clients alongside an established patent portfolio. By acquiring these turnkey certifications and F-RAM technologies, Winbond effectively bypasses at least three years of tedious qualification procedures, staking an immediate claim in an increasingly tight supply cycle while seizing control over premium supply and pricing negotiations.
先進封裝與高階記憶體雙軌並進Twin Engines in Advanced Packaging and Specialty Memory
除了在既有快閃記憶體版圖大舉擴張,華邦電自身的產品結構也在經歷深度轉型。市場對該公司未來 2 年的獲利成長給予高度關注,其背後支撐不僅來自NOR Flash市佔率擴大帶來的規模經濟,更在於AI先進封裝領域的新布局。華邦電近年積極開發客製化超高頻寬記憶體CUBE,並投入先進封裝不可或缺的矽電容技術,目前相關產能已接近滿載。這些高附加價值產品與即將併入的業務形成技術互補,構建出兼具韌體儲存與高速傳輸的產品矩陣,使華邦電得以擺脫傳統記憶體的週期循環,建立起穩定的毛利防線。Beyond aggressively expanding its footprint in code storage flash, Winbond is actively transforming its broader product portfolio. High market expectations for the company's earnings trajectory over the next two years stem not only from the economies of scale unlocked by its expanded NOR Flash market share, but also from its strategic inroads into advanced packaging for AI. Winbond has been aggressively developing its proprietary CUBE (Customized Ultra-High Bandwidth Elements) architecture and investing heavily in silicon capacitors, an indispensable component for advanced packaging, with related capacity now running near full utilization. These high-value-added offerings form a natural technological complement with the acquired assets, creating a balanced product suite spanning firmware storage and high-speed data transmission that helps insulate Winbond from conventional memory cyclicality and fortifies gross margins.
巨額現金支出與整合過渡期考驗Balance Sheet Strains and Long-Horizon Execution Risks
儘管戰略藍圖宏大,這樁跨國交易帶來的財務負擔與營運整合挑戰同樣不容忽視。高達 11.2 億美元、折合新台幣約 356 億元的純現金收購代價,勢必大幅拉升華邦電的淨負債比率,對其短期的資產負債表健康度構成壓力。更具體的是,此併購案距離 2027 年下半年正式交割仍有相當長的過渡期,在此之前英飛凌相關業務的營收與獲利完全無法併入財報。華邦電必須在此期間妥善處理跨國研發團隊的文化融合,並協調海外晶圓代工外包合約的延續性。一旦市場週期在交割前出現劇烈波動,高額的融資成本與管理摩擦將成為最直接的獲利阻力。Despite the compelling strategic narrative, the substantial financial burden and operational friction that accompany this cross-border deal cannot be overlooked. The all-cash consideration of $1.12 billion—roughly NT$35.6 billion—is set to sharply inflate Winbond's net debt ratio, weighing on the health of its balance sheet in the near term. Compounding this challenge is the extended runway before the anticipated close in the second half of 2027, during which none of the revenue or profit from the acquired Infineon operations can be consolidated into Winbond's financial statements. In the interim, management must navigate the cultural integration of overseas R&D teams and secure the continuity of external foundry outsourcing agreements. Should the memory cycle experience sharp volatility before closing, high borrowing costs and integration frictions could translate into direct earnings headwinds.
華邦電藉由收購坐上全球編碼型記憶體王座,確立了長線戰略高地。然而在實質交割完成前,公司獲利能力仍取決於高容量記憶體報價的續航力,以及歐美監管機構審查進度。投資人接下來應重點關注跨國代工供應鏈的銜接狀況與車用訂單穩定度,而非過早將未交割的資產貢獻計入營運常態。Through this transaction, Winbond ascends to the throne of the global code storage memory market, securing an enviable long-term strategic vantage point. Yet until the acquisition reaches formal closing, the company's bottom-line performance will remain tethered to the pricing trajectory of high-density memory and the pace of regulatory clearances across Western jurisdictions. Going forward, investors should focus on the seamless continuity of the cross-border foundry supply chain and the durability of automotive order books, rather than prematurely factoring in earnings contributions from unclosed assets.
提供全球NOR市佔變動拆解、2026 至 2027 年獲利模型預估,以及監管交割與報價檢查點。Delivers a detailed breakdown of shifting global NOR market share, earnings model projections spanning 2026 to 2027, and key regulatory closing and contract-pricing milestones.