AHI Journal

2026 年 9 月 17 日 星期四Thursday, September 17, 2026登入Log In訂閱Subscribe
全球貨幣政策分歧GLOBAL MONETARY DIVERGENCE

聯準會全票升息一碼 點陣圖上修確立長期高利率結構Fed Votes Unanimously to Hike 25 Bps; Higher Dot Plot Solidifies 'Higher for Longer'

美國 8 月零售銷售強勁與進口物價上漲推升核心通膨壓力,聯準會展現對抗 2 次通膨的強硬決心。Strong August U.S. retail sales and rising import prices fueled core inflation pressures, reinforcing the central bank's resolve against secondary inflation.
centralbank(日本央行建築實景照片)
圖:Photo: Syced 授權:License: CC0 來源:Source: Wikimedia Commons
2026 年 9 月 17 日 星期四Thursday, September 17, 2026總經與市場Markets總經與利率Macro & Rates免費版Free Edition
下一個可驗證時點Next checkpoint10/10(六)2605 新興 9 月營收(10 日前申報)
到時候看What to check9 月營收年增率是否高於前 3 個月平均(前 3 個月平均年增 +34.5%);月增率有沒有延續,累計年增率的方向。

聯準會 9 月 16 日無異議拍板升息 0.25 個百分點,將政策目標範圍推升至 3.75%至 4.00%,並同步調升 2026 年末基準利率預估中值至 4.1%。這項決議徹底終結了市場此前對於年底啟動預防性降息的單方面樂觀預期,宣告資產定價必須重構。央行用行動證明,相較於金融市場承受的短期震盪,遏阻 2 次通膨蔓延具有絕對優先權。全球投資人正面對一個融資成本長期維持高檔的新常態,過去 10 年依賴廉價流動性支撐的估值模型正加速失效,資金環境的轉向正迫使所有資產重估風險溢酬。The Federal Reserve voted unanimously on Sept. 16 to raise its benchmark policy rate by a quarter percentage point to a range of 3.75% to 4.00%, while lifting its median projection for the terminal rate at the end of 2026 to 4.1%. The decision decisively dismantled overly optimistic market expectations for preemptive rate cuts by year-end, signaling that asset valuations must be recalibrated. Through its actions, the central bank underscored that snuffing out a potential second wave of inflation takes absolute precedence over short-term volatility in financial markets. Global investors now face a structural reality where capital costs remain elevated for longer, accelerating the obsolescence of valuation frameworks built on a decade of ultra-cheap liquidity and forcing a market-wide repricing of risk premiums.

內需消費與輸入通膨催生升息決策Resilient Consumption and Import Costs Spur the Hike

推動本次重啟升息的根源,在於美國實體經濟展現超乎預期的抗壓韌性,以及海外價格壓力的重燃。美國 8 月零售銷售月增率繳出 1.2%的強勁表現,大幅超越市場原先預估的 0.8%,顯示家庭消費動能在借貸成本攀升下仍未顯著冷卻。與此同時,8 月進口物價指數月增 0.7%、年增率進一步攀升至 7.0%,反映出外部輸入型通膨壓力全面回升。強勁的實體需求與升溫的進口成本形成共振效應,迫使貨幣當局必須透過預防性緊縮,阻斷通膨預期心理擴散至更廣泛的服務性項目之中。The catalyst behind the resumption of rate hikes lies in the surprising resilience of the U.S. real economy alongside a resurgence in external price pressures. U.S. retail sales for August surged 1.2% month-over-month, handily topping market forecasts of 0.8% and demonstrating that household spending appetite has not cooled despite mounting borrowing costs. Simultaneously, the August Import Price Index climbed 0.7% sequentially, pushing the year-over-year rate to 7.0% and signaling a broad-based rebound in imported inflation. The confluence of robust domestic consumption and rising import costs forced policymakers to execute a preemptive tightening move, aiming to thwart inflation expectations from becoming entrenched across the broader services sector.

美國 10 年期公債殖利率 走勢圖5.094.74.35.01%05-1206-0507-0107-2708-1909-14美國 10 年期公債殖利率 走勢圖5.094.74.35.01%05-1206-2408-0509-16
美國 10 年期公債殖利率(%) 近 90 個交易日・05-12 → 09-18圖對應:展示美國長天期公債殖利率在聯準會升息後的攀升走勢。讀法:這段期間 +0.55 個百分點(4.46% → 5.01%)。全球資產的折現率基準;升代表折現率上行,對高評價成長股最敏感。

實質經濟走強拉長限制性利率週期Economic Momentum Stretches the Restrictive Cycle

聯準會最新經濟展望揭示更為漫長的緊縮路徑,政策制定者實質推遲了物價回歸常態的時程。官方將 2026 年與 2027 年實質經濟擴張速度分別調升至 2.3%與 2.4%,失業率預期則維持在 4.1%的歷史相對低檔;然而,核心PCE通膨重返 2.0%目標的預期時點,已被正式延後至 2029 年。這意味著官方承認通膨的結構性黏性超乎預期,高利率環境不再是短暫的過渡手段,而將轉化為長期的制度性約束,企業融資負擔與各類信用擴張動能,都將在未來數年持續承受實質緊縮的壓力。The Fed's updated Summary of Economic Projections delineates a prolonged restrictive path, effectively pushing back the timeline for price stability. Officials upgraded real GDP growth projections to 2.3% for 2026 and 2.4% for 2027, while holding the unemployment rate expectation near historic lows at 4.1%. However, the target horizon for core PCE inflation to ease back to 2.0% was officially deferred to 2029. This adjustment constitutes an explicit acknowledgment that structural inflation is proving stickier than anticipated. High interest rates are no longer merely a temporary transition, but an enduring institutional constraint set to exert sustained pressure on corporate financing and credit expansion for years to come.

資本市場分歧突顯產業定價權優勢Wall Street Divergence Spotlights Pricing Power

決策出爐後,美股內部出現極為顯著的結構性分歧,反映出不同產業在資本成本上升時的承受落差。高度依賴債務槓桿與傳統信用的道瓊工業指數單日重挫 631 點,跌幅達到 1.21%,承受估值壓縮的沉重衝擊;相較之下,費城半導體指數卻逆勢收紅 0.63%。同一場升息會議引發了截然相反的資本流向,舊經濟板塊面臨融資成本墊高的嚴酷考驗,而坐擁定價權、實質現金流與強勁成長前景的高階科技硬體產業,則被避險資金視為抵禦利率高壓與貨幣實質購買力流失的關鍵避風港。Following the policy announcement, U.S. equities witnessed an acute structural divergence, highlighting the stark gap across industries in absorbing higher capital costs. The Dow Jones Industrial Average, heavily exposed to leveraged balance sheets and traditional credit, sank 631 points, or 1.21%, bearing the brunt of valuation contraction. By contrast, the Philadelphia Semiconductor Index bucked the trend to finish up 0.63%. The same rate decision spurred diametrically opposed capital allocations: while old-economy sectors faced a severe reckoning from elevated debt-servicing costs, premium technology hardware leaders—armed with durable pricing power, resilient cash generation, and robust growth prospects—were seized upon by defensive capital as primary shelters against policy headwinds and currency debasement.

本刊判斷,全球流動性收縮已進入持久戰階段。接下來應密切聚焦核心通膨指標的降溫斜率,以及長天期公債殖利率在高檔盤整的持續時間。若借貸成本維持高壓,全球新興市場的匯率防線與高槓桿企業的再融資壓力將首當其衝。資金將持續向具備實質自由現金流的資產集中,市場洗牌格局正不可逆地展開。AHI Journal assesses that the contraction in global liquidity has entered a protracted phase of attrition. Moving forward, attention should zero in on the cooling trajectory of core inflation metrics and how long benchmark Treasury yields hover near cycle highs. If borrowing costs remain elevated, emerging-market currencies and refinancing pipelines for highly leveraged corporates will face direct stress. Capital will continue to coalesce around assets generating tangible free cash flow, setting in motion an irreversible shakeout across global markets.

詳解點陣圖利率路徑序列、美股分化定價模型,以及核心PCE與美債殖利率升級指標門檻。Features a granular breakdown of dot-plot interest-rate trajectories, cross-asset equity dispersion models, and quantitative threshold triggers for core PCE and Treasury yields.
閱讀訂閱版Read the subscriber edition

本刊結論:Our verdict: 立場:偏空高利率環境下的融資與信用擴張;信心:高,聯準會全票升息且將核心PCE達標推遲至 2029 年;否證:若 2026 年末基準利率預估中值調降至 4.1%以下,則本判斷不成立。

接下來看什麼What to watch next

  1. 美國 9 月核心PCE年增率:以 3.5%為門檻。10 月下旬公布之數據若高於 3.5%,則貨幣緊縮升級條件成立;若等於或低於 3.5%,則不成立。
  2. 10 年期美債殖利率:以 5.0%為門檻。若持續維持在 5.0%以上超過 30 個交易日,則新興市場匯率貶值壓力成立;若未能連續 30 個交易日維持在 5.0%以上,則不成立。

風險燈號Risk Dashboard

總經政策Macro Policy
聯準會全票升息 1 碼且點陣圖暗示年內續升,美債殖利率破 5%壓抑資產估值。Unanimous 25-bps Fed hike and higher dot plot point to further tightening; yields above 5% compress equity multiples.
市場流動性Market Liquidity
外資台指期淨空單自高檔降至 7.6 萬口,現貨賣超縮減,但當沖比重逼近 40%。Foreign futures net shorts retreated from peaks to 76,000 contracts and spot selling slowed, but day trading near 40% heightens volatility.
產業敘事Industry Narrative
先進製程耗材、ABF載板與伺服器功率元件需求強勁,訂單能見度延伸至 2027 年。Demand for advanced packaging consumables, ABF substrates, and server power components remains strong, with visibility extending to 2027.
時間季節性Seasonality
9 月歷史負報酬窗口期尚未結束,季底法人作帳與央行會議密集期市場震盪加劇。September's historical negative-return window persists amid quarter-end institutional rebalancing and central bank rate decisions.

要聞速覽What’s News看完整內容 →full story →

市場Markets

外資期貨空單大減 6872 口Foreign Futures Net Shorts Fall by 6,872 Contracts9 月 16 日外資在期貨市場減持空單 6,872 口,淨空單降至 76,351 口,現貨賣超縮小至 179.8 億元,顯示籌碼面極端避險壓力出現邊際緩解。Foreign institutional investors covered 6,872 contracts in index futures on Sept.

聯邦基金利率調升至 4%Fed Lifts Funds Rate to 4%美國聯準會全體官員一致同意升息 25 個基點,基準借貸成本區間來到 3.75%至 4.00%;Federal Reserve officials voted unanimously to raise the ben…

美國 10 年期債息攀至 5.02%10-Year Treasury Yield Hovers at 5.02%受 8 月零售銷售月增 1.2%與進口物價上漲推動,美債 10 年期殖利率維持在 5.02%,高利率持續推升科技股折現率負擔。Propelled by a 1.2% monthly rise in August retail sales and climbing import prices, the U.S.

產業與企業Industry & Companies

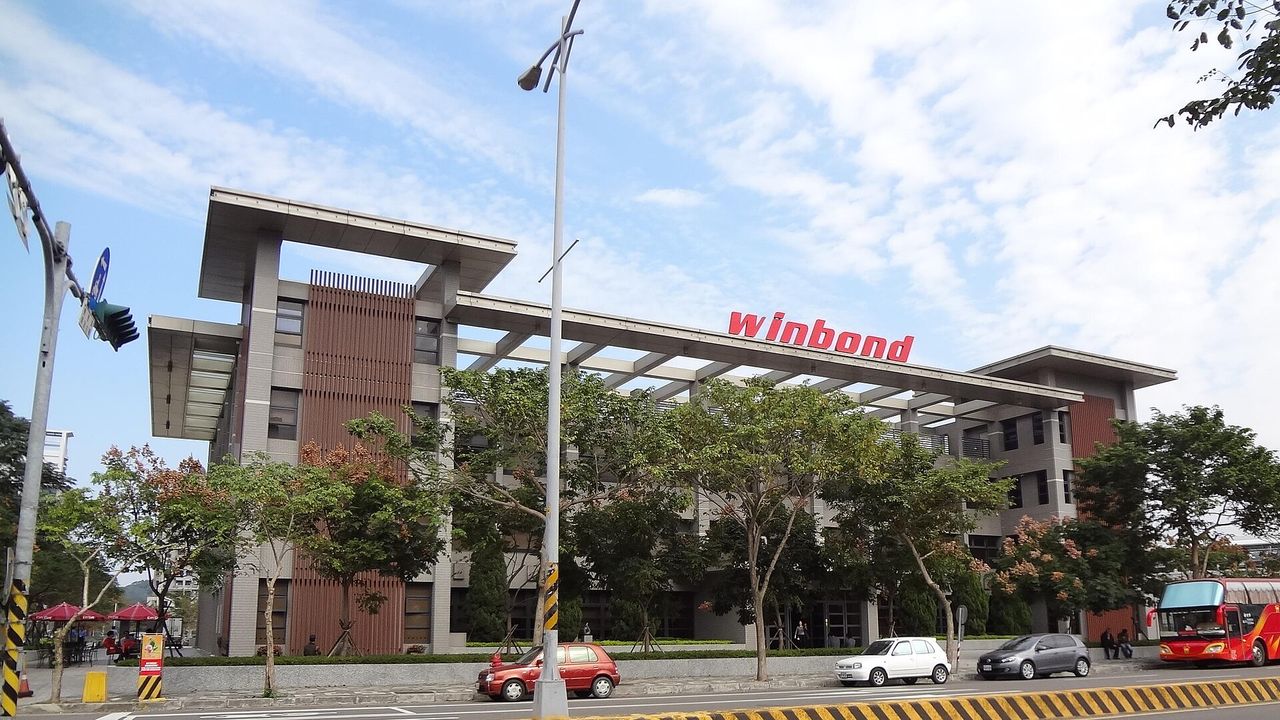
華邦電併購英飛凌記憶體事業Winbond Acquires Infineon Memory Unit華邦電斥資 11.2 億美元收購英飛凌NOR Flash業務,合併後市佔率將升至 34%,有助掌握車用與AI伺服器編碼快閃記憶體定價權。Winbond agreed to buy Infineon's NOR Flash business for $1.1…

欣興高階ABF產能擴增 3 成Unimicron Expands High-End ABF Capacity 30%欣興因應AI伺服器載板供不應求,規劃 2027 年ABF產能擴增 30%至 40%,外資研究預估高階報價漲幅擴大將帶動毛利率站上 35%。Addressing tight AI server substrate supplies, Unimicron pla…

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
算力擴張現實COMPUTE EXPANSION REALITY

3 大雲端巨頭半數資產未上線 基礎建設受制於電網交付延宕Half of Big Cloud Assets Offline as Grid Delays Bottleneck Infrastructure

Meta與Google在 2026 年上半年未上線資產比例達 50%,甲骨文亦逾 40%。市場持續預期雲端資本支出維持高成長,卻忽視了電網交付遞延正在拉長硬體沉澱週期。Meta and Google saw up to 50% of capital assets remain offline in the first half of 2026, with Oracle exceeding 40%. While markets bank on sustained high capex growth, delayed grid connections are stretching hardware gestation cycles.

2026-09-17總經與市場Markets科技巨頭與美股Big Tech & U.S. Equities
閱讀 →Read →
記憶體產業併購整合MEMORY M&A CONSOLIDATION

華邦電以 11.2 億美元收購英飛凌業務 全球NOR市佔躍升 34%Winbond to Buy Infineon Unit for $1.12B, Pushing Global NOR Share to 34%

透過吸收海外車用驗證與高階技術,華邦電將編碼型快閃記憶體版圖擴大至全球第一。By integrating automotive qualifications and premium tech, Winbond will scale its NOR flash presence to become the world's largest supplier.

2026-09-17科技Technology記憶體Memory
閱讀 →Read →
載板供需與報價重估S一家研究機構TRATE PRICING DYNAMICS

欣興高階ABF報價漲幅擴大 法人集體上修 2027 年獲利逾 7 成Unimicron High-End ABF Price Hikes Expand; Analysts Lift 2027 Net Over 70%

AI晶片面積放大與晶背供電帶動載板消耗,欣興產能吃緊推動賣方上修獲利預期。Expanding AI die sizes and backside power delivery drive substrate layer counts, straining Unimicron capacity and spurring broad sell-side upgrades.

2026-09-17評等RatingsPCB 與載板PCB & Substrates
閱讀 →Read →
半導體材料與地緣重組SEMICONDUCTOR MATERIALS & GEOPOLITICS

中砂擴產鑽石碟搶進A16 製程 先進製程CMP道數增加 4 成Kinik Expands Diamond Disk Capacity for A16 Node as CMP Steps Surge 40%

台積電埃米級節點推升化學機械平坦化耗材用量,本土材料商打破海外寡占並加速擴產。TSMC's angstrom-era nodes require heavier CMP consumable usage, allowing domestic material vendors to break foreign oligopolies through capacity expansion.

2026-09-17海外Global半導體Semiconductors
閱讀 →Read →
實體基建與能源約束PHYSICAL INFRASTRUCTURE & POWER

AI伺服器功耗升級推升高壓元件 強茂與廣閎科掌握轉單優勢AI Power Spike Drives High-Voltage Demand; Panjit and Semi-Engine Secure Spillovers

歐美IDM產能聚焦高壓碳化矽引發中低壓轉單,台廠在伺服器散熱與電源架構升級中受惠。Western IDMs shifting lines toward high-voltage SiC are triggering mid- and low-voltage order spillovers to Taiwanese power discrete suppliers amid rack architecture upgrades.

2026-09-17風險Risk電源與功率元件Power & Discretes
閱讀 →Read →
本刊觀點Editor's View

電網堵塞與貨幣緊縮下的資本盲區Valuation Tug-of-War: Peak Yields vs. Fundamental Resilience

市場態:立場:看空供應鏈遠期資本支出指引;信心:中偏高;否證:雲端巨頭於財報季確認未通電機房全面加速併網且維持資本開支。Market State: Stance: Moderately bullish on semiconductor and server supply chains with pricing power; Confidence: Medium, tempered by 10-year Treasury yields topping 5% and persistent foreign spot selling; Invalidation: Foreign Taifex net shorts rebounding to 85,000 contracts and TAIEX breaking below its quarterly moving average at 44,700 points.

2026-09-17本刊觀點Editor's View綜合General
閱讀 →Read →