AHI Journal
電網堵塞與貨幣緊縮下的資本盲區Valuation Tug-of-War: Peak Yields vs. Fundamental Resilience
市場態:立場:看空供應鏈遠期資本支出指引;信心:中偏高;否證:雲端巨頭於財報季確認未通電機房全面加速併網且維持資本開支。Market State: Stance: Moderately bullish on semiconductor and server supply chains with pricing power; Confidence: Medium, tempered by 10-year Treasury yields topping 5% and persistent foreign spot selling; Invalidation: Foreign Taifex net shorts rebounding to 85,000 contracts and TAIEX breaking below its quarterly moving average at 44,700 points.
美聯準會全票通過升息 1 碼,將聯邦基金利率推向 3.75%至 4.00%區間,年內政策利率路徑同步上修。在 10 年期美債殖利率突破 5.02%的無風險資產引力下,外資對台股現貨展開連續 5 個交易日的調節。然而,期貨市場在結算日出現罕見轉折,單日大幅回補 6,872 口空單,迫使淨空單降至 76,351 口,帶動加權指數逆勢勁揚 337 點。這場資金撤退與本土基本面接力護盤的拉鋸,正考驗市場對高利率週期的承受極限。The Federal Reserve unanimously approved a quarter-point rate hike, lifting the federal funds target rate to a range of 3.75% to 4.00% while revising upward its policy trajectory for the remainder of the year. Lured by risk-free assets as the 10-year U.S. Treasury yield pierced 5.02%, foreign institutional investors trimmed their Taiwan cash equity holdings for a fifth consecutive session. Yet the futures market staged a dramatic reversal on contract settlement day, with funds aggressively covering 6,872 short contracts in a single session. That trimmed net short positions to 76,351 contracts and propelled the benchmark Taiex up 337 points against prevailing headwinds. This tug-of-war—between global capital flight and domestic fundamental support—is testing the market's pain threshold in an era of prolonged higher interest rates.
資本成本重構抑制資產評價Rising Cost of Capital Compresses Equity Valuations
無風險利率高懸直接墊高了權益資產的折現因子。10 年期美債殖利率站上 5.02%,疊加新台幣匯率在 31.888 附近持續承壓,使外資在台股現貨市場難以立即重啟大額買超,單日調節金額雖收斂逾 7 成,但仍達 179.80 億元。外資期貨空單自超過 8.3 萬口的極端水位迅速退守,本質上屬於結算日前的空頭部位平倉與避險平倉,並非對市場轉向全面翻多。全球央行維持高利率更長時間的既定基調,已在實質上封閉了整體大盤本益比全面擴張的空間。Elevated risk-free rates are directly driving up the discount factors applied to equity assets. With the 10-year Treasury yield establishing a foothold above 5.02% and the New Taiwan dollar languishing under persistent pressure near 31.888 against the greenback, foreign investors face structural hurdles in resuming meaningful net buying in the cash market. Although daily net outflows narrowed by more than 70%, foreign selling still reached NT$17.98 billion. The swift pullback in foreign futures short positions from extreme levels of over 83,000 contracts represents routine pre-settlement short covering and hedge unwinding, rather than an outright bullish pivot. The prevailing central-bank consensus to keep rates higher for longer has effectively capped broad-market price-to-earnings multiple expansion.
先進製程訂單延伸抵禦總體逆風Advanced-Node Order Backlogs Cushion Macro Headwinds
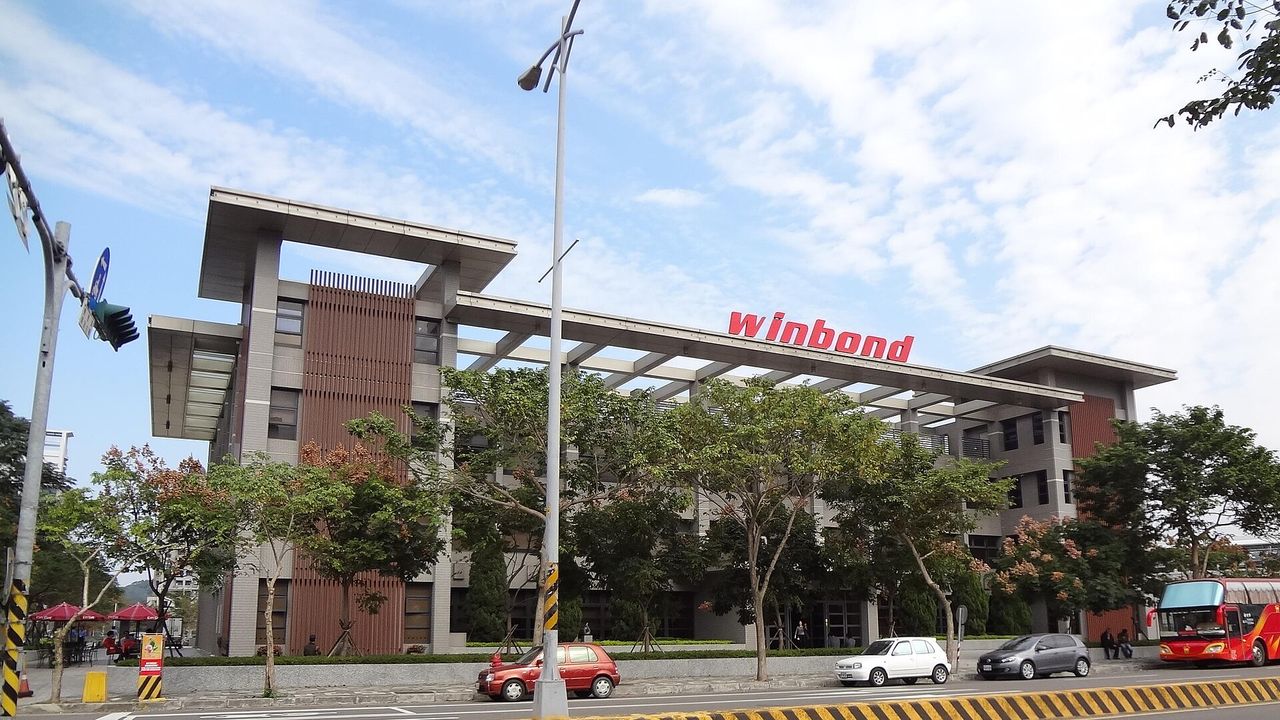
支撐指數在緊縮週期中反撲的核心動力,來自關鍵硬體產業清晰的實體訂單。半導體先進製程、高階伺服器及特種功率元件等供應鏈,受惠於結構性運算升級,部分訂單能見度已延伸至 2027 年。權值龍頭台積電以 27 分鐘完成除息填息,驗證了長線資金對龍頭營運韌性的高度定價;華邦電斥資 11.2 億美元逆勢進行跨國併購,亦展現龍頭供應商充沛的自由現金流與市占擴張意圖。這些微觀企業獲利預期的逆勢上修,構築了指數抗跌的護城河。The primary impetus fueling the market's counter-rally amid tightening conditions lies in clear physical order visibility across critical hardware sectors. Benefiting from structural computing upgrades, supply chains spanning advanced semiconductor nodes, high-end server racks, and specialty power components boast order books stretching as far as 2027. Bellwether TSMC took a mere 27 minutes to close its ex-dividend gap, confirming institutional confidence in its cash-generation resilience. Meanwhile, Winbond's aggressive US$1.12 billion cross-border acquisition underscores the ample free cash flow and market-share ambitions of tier-one vendors. These upward revisions in micro-level corporate earnings estimates have erected a sturdy moat against broader macro vulnerabilities.
當沖熱度偏高蘊藏 2 次傳導風險Elevated Day-Trading Ratios Signal Secondary Pass-Through Risks
儘管空單回補給予盤面喘息機會,市場微觀結構卻顯露不安信號。當沖交易佔大盤成交比重已逼近 40%高水位,反映內資與散戶籌碼多以日內價差為主要策略,持股信心不足使流動性呈現脆弱性。與此同時,國際原油價格若持續盤踞在每桶 105 美元上方,輸入性通膨將迫使能源及原料成本二階傳導至終端製造業,進一步壓縮中小型零組件廠的毛利率空間。在籌碼偏向浮躁的環境下,大盤任何非預期的外生震盪都可能放大指數波動幅度。While the short-covering rally provided breathing room, the market's internal microstructure reveals underlying fragility. Day trading has climbed toward 40% of total market turnover, suggesting that domestic capital and retail accounts are largely pursuing intraday price spreads rather than taking conviction-led long positions. Concurrently, should international crude oil remain entrenched above US$105 per barrel, imported inflation risks triggering secondary cost pass-throughs into energy and raw materials for downstream manufacturing. That would squeeze gross margins across small- and mid-cap component makers. In an environment characterized by flighty capital, unexpected exogenous shocks could trigger amplified index volatility.
本刊判斷,台股短線跌勢已獲期貨空單回補抑制,但由評價收縮轉向動能行情的關鍵,仍取決於外資現貨賣盤是否全面竭盡並轉為實質買超,以及成交量能能否維持溫和擴張。接下來應持續觀察美元指數走勢與新台幣匯率能否止貶回穩,若資金撤離壓力緩解,具技術領先與實質毛利防禦力的產業龍頭,將優先迎來評價修復。AHI Journal concludes that the short-term slide in Taiwan equities has been arrested by futures short covering, but any transition from valuation compression to sustained upside momentum hinges on two variables: the complete exhaustion of foreign cash selling in favor of genuine net accumulation, and a measured expansion in trading volume. Investors should closely monitor the U.S. Dollar Index and gauge whether the New Taiwan dollar can halt its depreciation. Once liquidity-drain pressures abate, industry-leading tech firms backed by deep technological moats and margin defensibility will be the prime beneficiaries of valuation recovery.
完整提供跨資產定價拉鋸圖表、輸入型通膨二階傳導路徑,以及跌破關鍵均線之全面否證條件。Provides cross-asset valuation tug-of-war diagnostics, imported second-order inflation transmission channels, and structural invalidation parameters on critical moving averages.