AHI Journal
欣興高階ABF報價漲幅擴大 法人集體上修 2027 年獲利逾 7 成Unimicron High-End ABF Price Hikes Expand; Analysts Lift 2027 Net Over 70%
AI晶片面積放大與晶背供電帶動載板消耗,欣興產能吃緊推動賣方上修獲利預期。Expanding AI die sizes and backside power delivery drive substrate layer counts, straining Unimicron capacity and spurring broad sell-side upgrades.
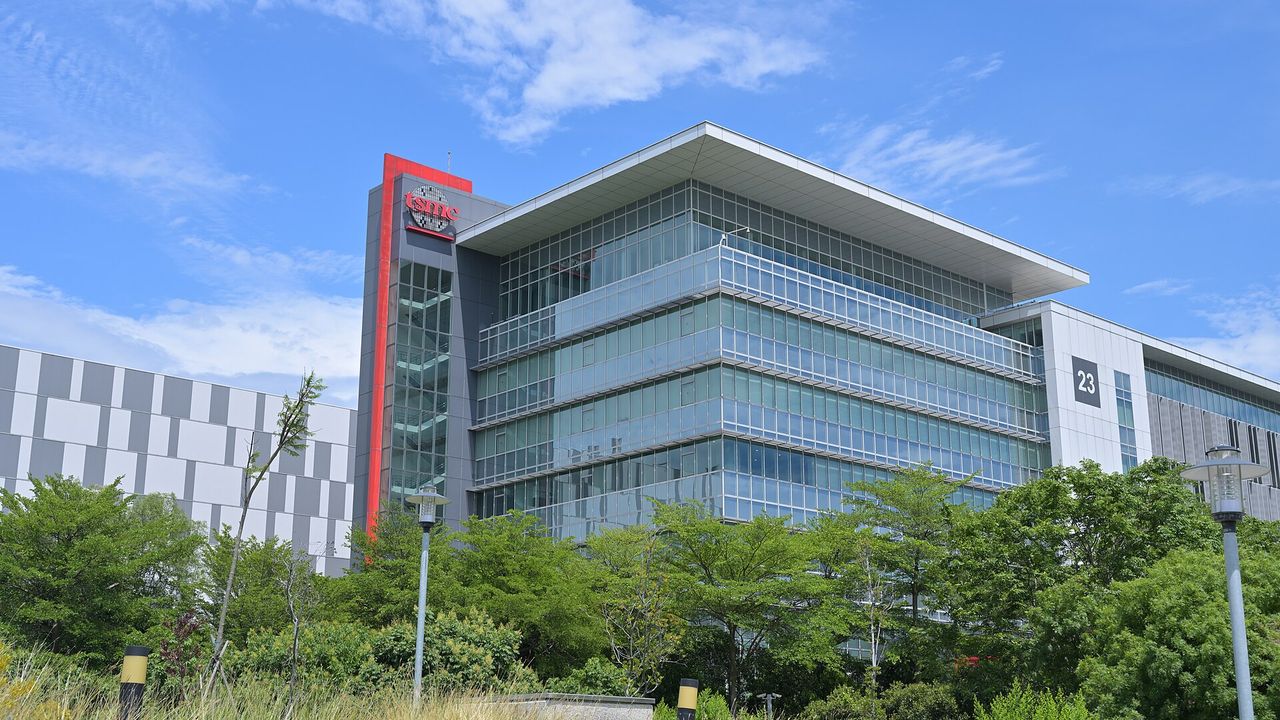
高階載板市場的供需天平正在加速傾斜。多家研究機構近期相繼上修載板龍頭欣興的財務模型,主因第 3 季高階ABF載板報價漲幅優於原先預期約 10 個百分點。這項定價信號意味著載板產業的復甦已脫離單純產能利用率回溫的初級階段,正式跨入具備結構性定價紅利的全新週期。隨著次世代AI晶片對大尺寸與高層數載板的物理消耗倍增,供應鏈產能吃緊的態勢不僅延續至下一個年度,更促使法人機構將這家載板大廠 2027 年的獲利預估下限顯著拉抬,引發市場對其長期成長爆發力的重新定價。The supply-demand balance in the high-end IC substrate market is tipping rapidly. Multiple research institutions have recently upgraded their financial models for industry leader Unimicron, primarily because third-quarter contract price hikes for high-end ABF substrates beat initial expectations by roughly 10 percentage points. This pricing signal indicates that the substrate sector's recovery has moved beyond a rudimentary rebound in capacity utilization into a structural pricing cycle. As next-generation AI processors double the physical consumption of large-area, high-layer-count substrates, capacity constraints will extend into next year. Consequently, institutional analysts have meaningfully raised the lower bound of their 2027 earnings forecasts, triggering a broad market repricing of Unimicron's long-term growth potential.
次世代晶片規格擴大物理消耗Next-Gen Chip Specs Drive Exponential Physical Consumption
這一輪獲利預期集體上調的核心驅動力,來自先進封裝技術帶來的物理規格變革。次世代AI晶片面積持續放大,加上晶背供電等前瞻技術導入,使得每顆處理器所需的載板層數與面積呈現倍數級增長,徹底打破了過去消費性電子週期的消耗模型。目前研究機構對欣興 2026 年每股純益的主流共識已落在 23.57 元至 24.62 元之間,而針對 2027 年的預估值,最樂觀的機構甚至上調至 40.23 元至 53.65 元區間。這項數字隱含著獲利年增率可能高達 7 成至 1.2 倍,反映出高端供應鏈極度寡占下的定價優勢。The core catalyst behind this wave of earnings upgrades stems from the physical specification overhaul ushered in by advanced packaging. Next-generation AI chips feature continuously expanding die sizes and the integration of cutting-edge technologies like backside power delivery, causing the required substrate layer count and surface area per processor to multiply. This shift has dismantled the consumption patterns seen in past consumer electronics cycles. Institutional consensus for Unimicron's 2026 earnings per share now clusters between NT$23.57 and NT$24.62, while the most bullish estimates for 2027 have been lifted to a range of NT$40.23 to NT$53.65. These figures imply an annual profit growth rate of 70% to 120%, underscoring the supplier's formidable pricing power within a tightly consolidated, high-end oligopoly.
擴產效益助攻毛利結構轉變Capacity Expansion Catalyzes Gross Margin Transformation
產能釋放與產品組合改善,正推動整體獲利結構產生質變。欣興第 2 季營收達到 428.9 億元,毛利率逆勢攀升至 24.8%的新高水平,印證高階產品比重拉升的實質效益。市場共識預估其 2026 年營收將逼近 1,926 億元,年增率超過 46%,毛利率維持在 24.3%至 26.4%區間。隨著光復廠高階產能預計提前開出,2027 年全年營收更被推升至突破 3,116 億元的規模,屆時毛利率有望進一步衝上 35.0%的高峰。產能規模擴張不再伴隨削價競爭,而是直接轉化為高階產能的營運槓桿。New capacity online and an improved product mix are reshaping Unimicron's underlying earnings quality. Second-quarter revenue reached NT$42.89 billion, while gross margin rose against headwinds to a record 24.8%, validating the margin accretive impact of a richer high-end product mix. Consensus projections now model 2026 revenue approaching NT$192.6 billion—up more than 46% year-over-year—with gross margins holding between 24.3% and 26.4%. With advanced capacity at the Guangfu fab slated to come online ahead of schedule, 2027 revenue is projected to top NT$311.6 billion, pushing gross margins toward a peak of 35.0%. Scale expansion is no longer triggering price competition; instead, it is translating directly into operational leverage on premium production lines.
長約鎖定產能化解擴產風險Long-Term Contracts Derisk Heavy Capital Outlays
市場對擴產步伐的疑慮並未完全消散,焦點落在法規監管與海外新廠初期的學習成本。先前中壢廠區面臨的調查程序,以及泰國新廠投產初期的良率磨合,均曾引發折舊壓力壓抑獲利的擔憂。然而,來自全球AI晶片大廠與雲端服務業者的客製化需求,已顯著改變了資本支出的回收風險。國際客戶為了確保未來運算晶片的供貨無虞,已透過長期預約協議將 2027 年的高階產能全數鎖定。這類不可撤銷的實質綁約機制,確保了新廠運轉時的產能利用率維持高檔,將固定資產折舊的衝擊降至最低。Market concerns regarding the pace of capacity expansion have not vanished entirely, focusing on regulatory scrutiny and initial learning curves at overseas facilities. Prior regulatory reviews at the Zhongli site and initial yield ramps at the new Thailand plant had raised worries that rising depreciation expenses might weigh on near-term profitability. However, customized demand from leading global AI chip designers and cloud service providers has reshaped the risk profile of these capital outlays. To secure computing chip allocations, hyperscale clients have locked up virtually all of Unimicron's 2027 high-end capacity through long-term advance agreements. These irrevocable commitments ensure elevated utilization rates once the new lines ramp, cushioning the impact of fixed-asset depreciation.
欣興已邁入由技術規格升級驅動的定價週期,長期基本面具備強烈擴張動能。投資人後續應密切觀察第 3 季財報中的毛利率走勢,以確認載板漲價效應是否順利向下傳導;同時,新廠先進設備進駐後的良率攀爬速度,將是檢視 2027 年獲利爆發力能否完全兌現的核心指標。Unimicron has firmly entered a pricing cycle anchored in technical upgrades, underpinning sustained fundamental momentum over the long haul. Investors should closely track gross margin trajectory in the upcoming third-quarter report to verify that substrate price increases are feeding smoothly into the bottom line. Meanwhile, the speed of yield-rate maturation following advanced equipment installation will be the critical benchmark for whether the projected 2027 earnings explosion fully materializes.
收錄 5 大機構EPS預估分歧表、新廠良率與折舊爬坡數據,以及第 3 季財報毛利率驗證門檻。Includes our five-institution EPS divergence matrix, greenfield yield and depreciation ramp schedules, and gross margin validation thresholds for the third-quarter print.