AHI Journal
AI伺服器功耗升級推升高壓元件 強茂與廣閎科掌握轉單優勢AI Power Spike Drives High-Voltage Demand; Panjit and Semi-Engine Secure Spillovers
歐美IDM產能聚焦高壓碳化矽引發中低壓轉單,台廠在伺服器散熱與電源架構升級中受惠。Western IDMs shifting lines toward high-voltage SiC are triggering mid- and low-voltage order spillovers to Taiwanese power discrete suppliers amid rack architecture upgrades.
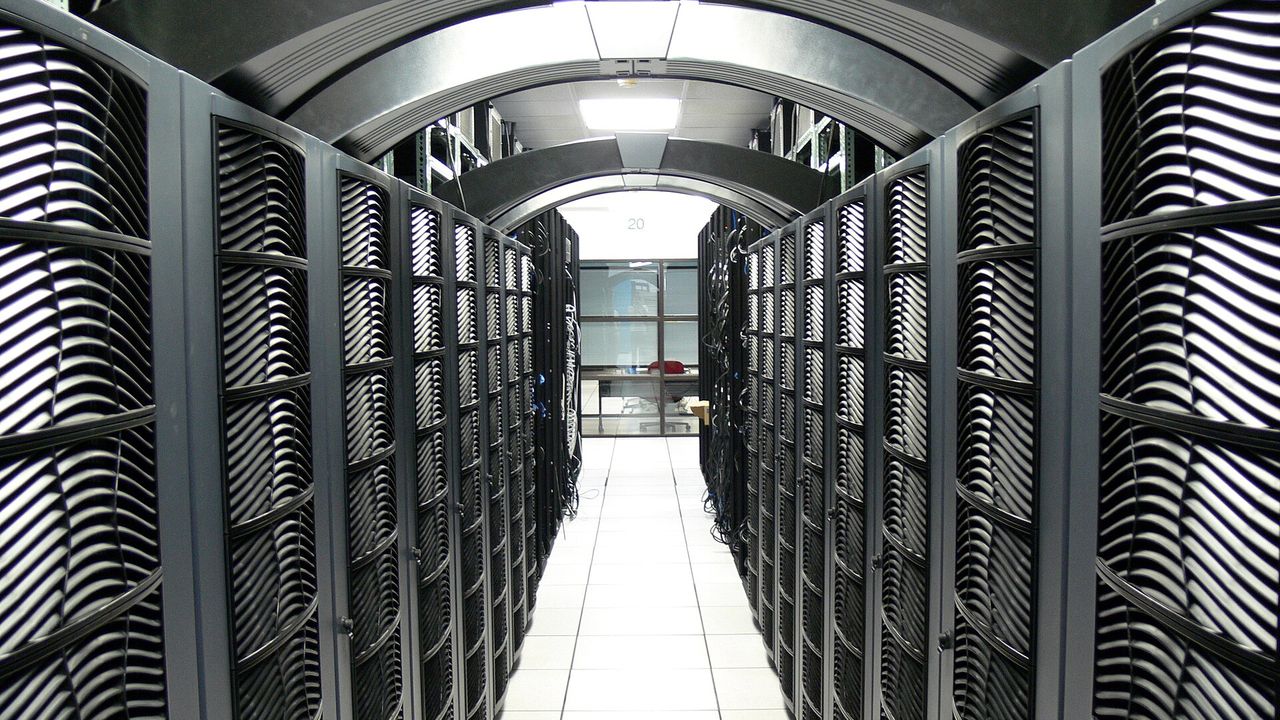
全球人工智慧運算架構升級正掀起一場被低估的硬體電源革命。隨著算力密度飆升,伺服器供電系統加速轉向 48V直流架構,散熱機制亦由傳統氣冷全面跨入液冷時代,推動高功率無刷直流馬達與散熱驅動元件需求翻倍噴發。與此同時,歐美整合元件製造大廠正將戰略資源與產能全數鎖定於超高壓碳化矽領域,無意間在中低壓伺服器元件市場留出供給缺口。這項產業板塊位移,直接讓具備垂直整合能力的台灣功率元件供應商接管全球訂單。強茂與廣閎科等業者的伺服器營收在單季內繳出翻倍以上的成長動能,印證了這波架構變革不僅是規格更新,更是一場供應鏈重分配的深層轉折。The architectural overhaul of global artificial intelligence hardware is triggering an underappreciated revolution in power delivery. Surging compute densities are accelerating server system transitions to 48V direct-current architectures, while thermal management is shifting from legacy air cooling to liquid systems, driving demand for high-power brushless DC (BLDC) motors and thermal driver components. At the same time, European and American integrated device manufacturers (IDMs) are concentrating their strategic capex and wafer allocations on ultra-high-voltage silicon carbide, unintentionally vacating supply in mid-to-low-voltage server components. This structural realignment has allowed vertically integrated Taiwanese power component suppliers to capture global share, with server-driven revenues at Panjit and Champion Microelectronic more than doubling in a single quarter.
液冷散熱驅動架構全面改寫規格Liquid-Cooling Architecture Overhauls Component Specifications
伺服器由傳統風冷邁入水冷機櫃的技術跨越,直接重塑了功率元件的配置邏輯。單台水冷機櫃內部必須配置數十組高可靠度的液冷幫浦與散熱風扇,驅動這些機構運作的 48V無刷直流馬達晶片,其用量相較傳統伺服器呈現倍數級暴增。這類馬達控制晶片不僅需要承受極高的電壓波動,更對散熱效率與連續運作的穩定度有著極其嚴格的工業標準。以廣閎科為例,該公司第 2 季伺服器相關營收繳出季增 138%的爆發性成績,單季每股純益更一舉攻上 2.21 元歷史新高,充分驗證了高階水冷系統對散熱晶片拉貨動能的剛性支撐,也反映出高單價利基型元件在整體營收結構中所扮演的關鍵推手。The technical leap from standard air cooling to liquid-cooled server racks is fundamentally rewriting component design criteria. A single liquid-cooled rack requires dozens of ultra-reliable liquid pumps and radiator fans, driving a multi-fold surge in the consumption of 48V BLDC motor control chips relative to legacy architectures. These motor controllers must not only withstand steep voltage transients, but also satisfy rigorous industrial reliability standards for thermal dissipation and uninterrupted operation. Champion Microelectronic underscored this trend in the second quarter, posting a 138% quarter-over-quarter leap in server-related revenue while earnings per share reached a record NT$2.21. This performance validates the inelastic demand for thermal chips generated by advanced liquid cooling, cementing high-ASP niche silicon as a key revenue driver.
歐美轉單與地緣整合擴大市佔版圖Western Reallocations and Regional Consolidation Expand Market Share
歐美半導體龍頭將晶圓製造量能大舉調往車用與工業級高壓碳化矽元件,為中低壓市場製造出結構性供需斷層。與此同時,歐美一線雲端服務業者對非中資供應鏈的審查標準更趨嚴苛,使兼具前段晶圓製造與後段封裝測試垂直整合能力的台廠迅速脫穎而出。強茂憑藉自主製程實力避開了供應鏈去化阻礙,成功切入全球主流伺服器代工體系。法人預期強茂 2026 年每股純益中位數將達 5.03 元、2027 年挑戰 6.95 元;廣閎科 2026 年每股純益預估達 8.69 元、2027 年更上看 11.13 元。這項預測反映市場對台廠在伺服器電源核心料件市場擴大份額、確立長期獲利能力的高度預期。As Western semiconductor bellwethers redirect wafer runs to automotive and industrial high-voltage silicon carbide, a structural supply gap has emerged in mid-to-low-voltage segments. Concurrently, tier-one Western cloud service providers are tightening provenance audits on their hardware ecosystems, allowing vertically integrated Taiwanese suppliers—with captive front-end wafer fabrication and back-end assembly and test—to stand out. Panjit leveraged internal manufacturing capabilities to navigate supply chain cleanups and break into mainstream global server ODM platforms. Analysts project Panjit's median 2026 earnings per share will hit NT$5.03 before challenging NT$6.95 in 2027, while Champion Microelectronic is forecast to deliver EPS of NT$8.69 in 2026 and reach NT$11.13 in 2027, reflecting confidence in market-share gains and structural profitability.
晶圓代工漲價與消費電子拖累毛利Foundry Price Hikes and Consumer Electronics Drags Weigh on Margins
儘管伺服器業務成長動能強勁,投資架構中仍存在上游製造成本攀升與終端需求分化的潛在變數。若八吋晶圓代工產能持續吃緊引發代工價格調漲,將直接墊高功率元件的生產成本,侵蝕產品附加價值的擴張空間。另一方面,消費性電子市場的復甦力道仍顯遲緩,台系業者旗下非伺服器產品線佔比依舊可觀,一旦標準型產品遭遇價格競爭與產能利用率下滑,整體獲利率的提升幅度恐將不如預期順暢。伺服器高毛利產品的營收貢獻能否在未來數季迅速擴張,並有效對沖成熟製程代工成本的漲價壓力,將是檢驗台廠獲利體質是否能真正脫胎換骨的關鍵核心。Despite robust server momentum, the investment thesis faces headwinds from higher upstream wafer costs and diverging end-market demand. Sustained tightness across eight-inch foundry capacity could trigger foundry price hikes, inflating production costs for discrete power components and narrowing margins. Furthermore, the recovery across consumer electronics remains sluggish, and Taiwanese power chipmakers retain meaningful exposure to non-server categories. If commoditized product lines face price erosion and declining factory utilization, blended margin expansion could stall. The pacing at which high-margin server products scale to offset mature-node foundry cost inflation will determine whether Taiwanese suppliers can permanently elevate their baseline profitability.
本刊判斷,功率半導體板塊的投資焦點已從全面性景氣復甦,轉向高規格伺服器電源與散熱領域的利基競爭。接下來應密切觀察伺服器應用佔整體營收比重的推進速度,以及在面對上游晶圓代工成本變動下,各家業者毛利率能否維持逐季擴張態勢,確認此波拉貨是長期架構升級而非短線庫存回補。The investment narrative for power semiconductors has pivoted from a cyclical tide to niche execution in high-spec server power and thermal management. Investors must track the pace at which server applications expand as a share of total revenue, alongside each supplier's capacity to defend gross margins against volatile upstream foundry pricing, confirming that current demand reflects permanent architectural upgrades rather than transitory channel restocking.
含括水冷散熱功率元件用量明細表、機構EPS預估區間,以及第 4 季伺服器營收月增檢查條件。Contains our granular BOM component map for liquid-cooling power silicon, institutional EPS forecast corridors, and fourth-quarter server revenue sequential tracking metrics.