AHI Journal
日銀升息一碼但內部現兩票反對 日圓走貶至 156 緩解套利平倉壓力BOJ Hikes 25 Basis Points Amid Two Dissenting Votes as Yen Weakens to 156, Easing Unwind Pressures
日本央行將基準利率上調至 1.25%,植田和男釋出溫和訊號使美日利差未加速收斂,跨國流動性獲得喘息空間The Bank of Japan lifts its benchmark rate to 1.25% as Kazuo Ueda issues dovish signals, pausing US-Japan yield convergence and providing breathing room for cross-border liquidity.
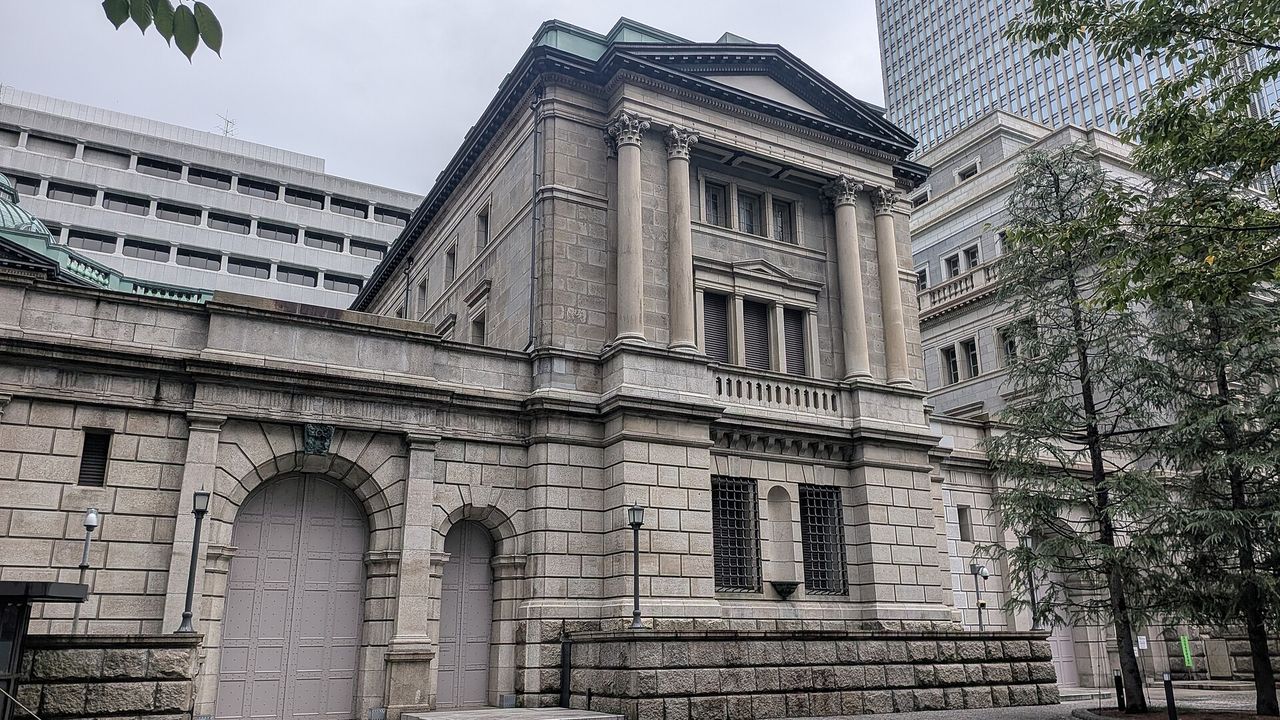
日本央行於 9 月 18 日決議將基準利率上調一碼至 1.25%,然而審議委員內部出現兩票反對,釋出緊縮節奏可能放緩的強烈訊號。這項符合預期但非全票通過的政策落地後,日圓兌美元不升反貶至 156.88,迅速緩解了全球金融市場對跨國套利交易恐慌性平倉的焦慮。在歐美公債殖利率持續高踞的背景下,日圓融資成本並未快速逼近海外資產收益率,讓先前緊繃的國際跨國流動性獲得關鍵喘息空間,也使全球風險性資產在升息決策公布後得以維持反彈動能。The Bank of Japan resolved on September 18 to hike its benchmark policy rate by a quarter-point to 1.25%, but two dissenting votes within its policy board signaled that the pace of monetary tightening could decelerate markedly. Following this expected yet non-unanimous outcome, the yen weakened against the greenback to 156.88 rather than appreciating, rapidly diffusing market panic over a catastrophic unwind of cross-border carry trades. With European and U.S. benchmark sovereign yields holding at multi-year highs, yen funding costs have stopped short of rapidly converging with overseas asset yields, offering global liquidity a vital reprieve and keeping risk assets firmly on their post-decision rebound track.
補貼壓抑物價促使決策分歧Utility Subsidies Subdue Inflation, Deepening Policy Board Dissent
日本央行決策出現歧見的根源在於國內通膨動能並未失控。官方重啟能源補貼政策直接壓低物價,8 月份電力支出與汽油成本分別年減 2.4%及 2.6%,帶動扣除生鮮食品後的核心通膨年增率下滑至 1.9%,不僅低於市場原先預估,更跌破央行的中長期警戒水準。與此同時,服務業通膨僅維持在 1.2%,租金漲幅亦停留在 0.5%的溫和區間。在內需薪資成長尚未完全轉化為全面性價格推力的現實下,審議委員以 7 比 2 的投票結構傳遞出明確訊號:央行無意以過於躁進的連續升息步伐打擊脆弱的經濟復甦。The fissure within the BOJ policy board stems from the fact that domestic inflationary momentum is hardly overheating. The reinstatement of government energy subsidies exerted direct downward pressure on headline prices: August electricity outlays and gasoline expenses dropped 2.4% and 2.6% year-on-year, respectively, dragging core consumer inflation excluding fresh food down to an annualized 1.9%—below market forecasts and slipping beneath the central bank's medium-to-long-term warning threshold. Meanwhile, services inflation hovered at a modest 1.2% and rent inflation remained subdued at 0.5%. With domestic wage growth yet to translate into broad-based demand-pull price pressures, the 7-to-2 vote split delivered a clear message: the central bank has little appetite to derail a fragile economic recovery with overly aggressive consecutive rate hikes.
跨國利差支撐全球流動性框架Cross-Border Yield Spreads Underpin Global Liquidity Architecture
日圓政策方向與歐美貨幣政策週期的錯位,是當前全球資本配置的核心支柱。美聯儲將聯邦基金利率定在 3.75%至 4.00%區間,美國 10 年期公債殖利率緊咬 5.0%上下,德國 10 年期公債殖利率也達到 3.52%,導致美日之間的實質利差依然寬達 350 個基點以上。外匯市場因此選擇淡化央行總裁在會後記者會上保留的緊縮口徑,轉而確認利差環境短期內無法快速逆轉。日圓匯率未如原先空方預期般升向 140 關卡,使長期借入日圓轉向海外高收益標的的槓桿資金免於被迫斬倉,成為支撐美股與台股科技股迅速修復的底層流動性。The fundamental mismatch between Japan's policy normalization trajectory and Western monetary cycles remains the central anchor of global capital allocation. With the Federal Reserve holding the federal funds target rate between 3.75% and 4.00%, the U.S. 10-year Treasury yield pinned around 5.0%, and Germany's 10-year Bund at 3.52%, the real yield differential between the U.S. and Japan remains comfortably wider than 350 basis points. Foreign exchange desks consequently chose to look past the BOJ governor's hawkish post-meeting rhetoric, seizing instead on the reality that this yield gap cannot swiftly evaporate. The yen's failure to rally toward the 140 mark spared leveraged capital borrowing in yen to fund high-yielding foreign assets from forced liquidations, providing the foundational liquidity supporting recoveries in U.S. and Taiwanese tech equities.
輸入型通膨或成下一波緊縮變數Imported Price Shocks Loom as Catalysts for Secondary Tightening
這場流動性喘息期並非沒有期限,其潛在變數主要來自外部輸入型通膨的 2 次回流。國際原油現貨價格高居每桶 100 美元之上,加上地緣政治局勢持續干擾關鍵航運通道,日本高度依賴進口的能源與原物料結構正面臨成本反彈壓力。一旦第 4 季進口物價顯著回升,即使國內實體消費依舊謹慎,日本央行仍可能被迫在年底例會前重啟升息程序。屆時日圓匯率的抗跌能力將受到實質考驗,若海外經濟體殖利率同時出現再定價,利差迅速壓縮所引發的資金回流日本本土壓力將再次浮上檯面,壓抑全球新興市場的資金水位。Yet this liquidity window carries an expiration date, with the primary wildcard being the resurgence of imported cost-push inflation. With international spot crude hovering above US$100 a barrel and ongoing geopolitical tensions choking key maritime trade routes, Japan's heavy reliance on imported energy and raw materials leaves it vulnerable to a rebound in input costs. Should fourth-quarter import prices rebound sharply, the BOJ could find its hand forced into resuming rate hikes before its year-end gathering, even if domestic consumption remains cautious. In that scenario, the yen's resilience will face a true stress test; a simultaneous repricing of overseas sovereign yields that swiftly narrows the rate spread would revive repatriation pressures toward the Japanese home market, draining global emerging-market liquidity.
本刊判斷,日圓短線貶值為全球市場買下流動性保險,但套利交易的結構性重整僅是延後而非解除。接下來應密切觀察日本生產者物價是否將上游能源成本轉嫁至終端消費,這將直接左右央行年底前是否二度緊縮;同時須追蹤美債長天期殖利率的走勢,確認跨國資金池能否持續承受利差變動帶來的再平衡衝擊。AHI Journal views the yen's short-term retreat as providing an essential liquidity backstop for global markets, though the structural restructuring of carry trades has merely been deferred rather than dismantled. Investors should closely monitor whether Japanese producer prices pass upstream energy burdens through to retail shelves—a shift that will dictate whether the BOJ tightens again before year-end—while tracking long-dated U.S. Treasury yields to gauge whether cross-border capital pools can absorb subsequent spread-rebalancing shocks.
完整報告拆解日銀投票結構、美歐日公債利差序列,並給出PPI通膨臨界值與匯率翻轉的檢查門檻。The complete report dissects the BOJ's voting distribution and U.S.-Europe-Japan sovereign yield spreads, while defining PPI inflation inflection points and exchange-rate reversal thresholds.