AHI Journal
長約防禦與高估值透支的拉鋸The Tug-of-War Between Long-Term Contract Defense and Stretched Valuations
市場態:立場:中性對加權指數挑戰 47500 點之延續性;信心:中,記憶體獲利下限確立但利率與融資水位緊繃;否證:外資期貨淨空單降至 5 萬口以下且全市場融資餘額連續 1 週減少。Market State: Stance: Neutral on the Taiex's ability to sustain gains above 47,500; Confidence: Medium, as memory floors firm while interest rates and margin debt remain stretched; Falsification: Foreign futures net shorts dropping below 50,000 contracts alongside a week of falling market margin debt.
當前加權指數在叩關高檔之際,盤面正呈現極端的分化拉鋸。一端是以記憶體為首的電子零組件,受惠於原廠產能轉移至先進規格所引發的實體斷層,營造出由合約保護與高毛利支撐的實質防禦力;另一端則是散熱與伺服器機構等族群,股價已大幅預支未來數年的產能放量,評價模式脫離了短期基本面軌道。這種定價機制的撕裂,在美國長天期公債殖利率緊繃與市場融資餘額累積至歷史高檔的背景下展開,意味著資本市場正對樂觀情境給予過度慷慨的容錯空間,任何供應鏈的微小震盪都將演變為結構性的估值重估。As Taiwan's benchmark Taiex tests elevated historical highs, the market is fracturing into an extreme tug-of-war. On one end, electronic components—led by memory makers—are benefiting from a physical supply vacuum triggered by chipmakers redirecting capacity toward advanced specifications, forging genuine downside defense underpinned by contract protections and extraordinary gross margins. On the other, segments such as thermal management and server chassis have run up sharply, pricing in capacity ramp-ups years into the future and divorcing multiples from near-term fundamental reality. This bifurcation is unfolding against a backdrop of taut long-term U.S. Treasury yields and local margin debt perched near record levels, suggesting equity markets are affording optimistic scenarios far too generous a margin for error—leaving valuations vulnerable to structural repricing at the slightest supply-chain hiccup.
產能斷層推升毛利 標準品構築防禦Capacity Void Widens Margins as Commodity Tech Anchors Portfolios
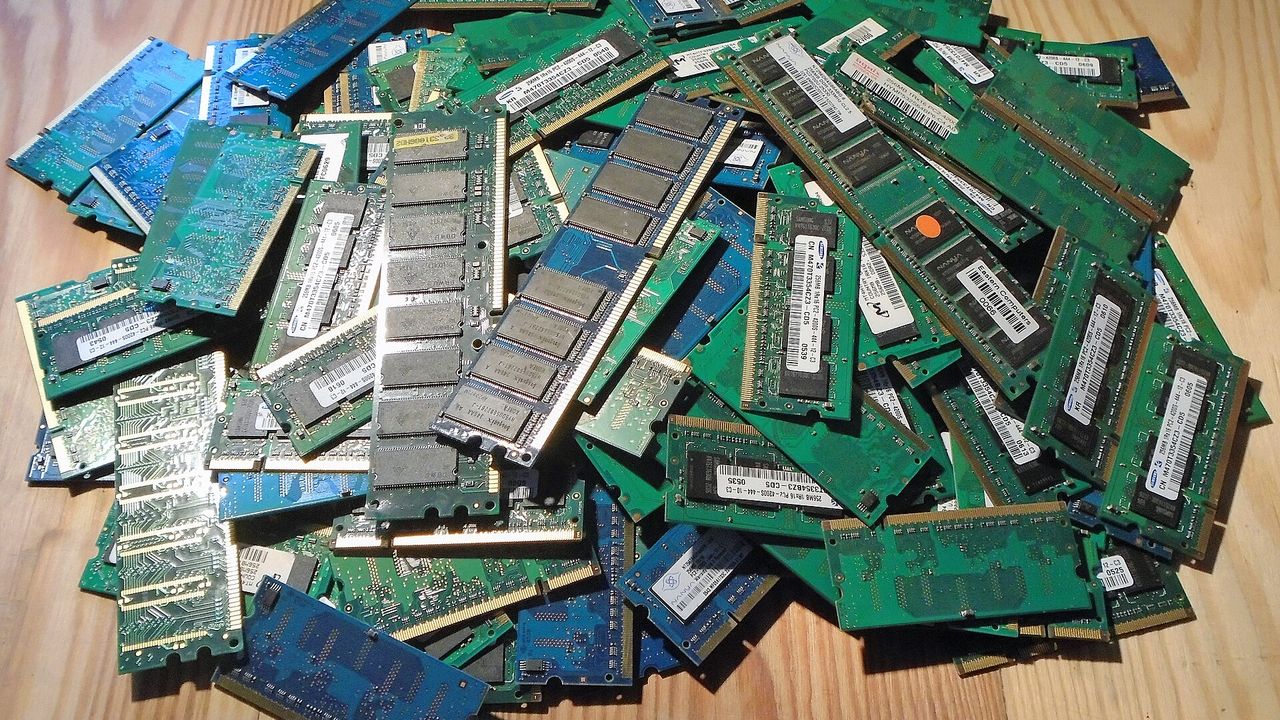
記憶體與被動元件近期的強勢定價,並非單純由終端消費復甦所帶動,而是供給端結構性轉變的結果。全球上游原廠將主要產能抽調轉向高階人工智慧規格,直接導致傳統標準品市場出現顯著的供給斷層。南亞科等製造廠因而具備強大的議價能力,將產品毛利率推升至 80%的歷史異常高位。這類建立在長約保護與實體缺貨之上的利潤,具備真實的會計帳面支撐,為股價提供了堅實的下檔緩衝。當上游原廠在短期內無意大幅擴充標準品產能時,這類防禦型組件便能在震盪格局中,扮演穩定整體獲利底線的錨定角色。The recent pricing strength in memory and passive components is not simply a creature of end-market consumer recovery, but rather the consequence of structural supply-side shifts. Global tier-one manufacturers have aggressively diverted frontline capacity toward high-end AI specifications, directly opening a pronounced supply fissure across legacy, standard-spec markets. Fabricators such as Nanya Technology have thus secured formidable bargaining power, pushing gross margins to an exceptional 80%. Backed by long-term volume contracts and genuine physical shortages, these profits provide tangible book-value support and a solid cushion against market volatility. With primary suppliers showing little appetite to expand standard-spec output over the near term, these defensive component plays are serving as ballast to anchor baseline earnings across the broader tech complex.
預支遠期產能放量 硬體估值難容瑕疵Stretched Hardware Multiples Leave No Room for Execution Flaws
相較於記憶體族群擁有實體缺貨支撐,散熱模組與連接器等伺服器零組件,則面臨完全不同的定價挑戰。市場資金已將目光投向 2027 年之後的產能放量階段,推動評價倍數進入歷史極端區間。機構法人對該族群 2027 年的每股盈餘預估落差高達 30%至 90%,顯示市場對未來的成長路徑存在嚴重的分歧與過度押注。目前的定價基礎建立在客戶訂單無延遲、零組件良率無瑕疵的完美假設之上。在硬體規格快速迭代的環境中,一旦量產時程遭遇瓶頸或產線良率出現波動,極高估值將迅速面臨均值回歸的猛烈修正。Unlike the memory sector's bedrock of physical shortages, server hardware plays such as thermal modules and connectors confront a far more precarious valuation dynamic. Speculative flows have already looked past the near term to price in volume scale-outs slated for 2027 and beyond, catapulting multiples into historically extreme territory. Consensus institutional EPS projections for these names in 2027 diverge by a staggering 30% to 90%, underscoring deep disagreements and aggressive bets on distant trajectories. Current market pricing hinges on flawless execution—assuming zero customer order deferrals and pristine component production yields. Amid rapid hardware architecture shifts, any mass-production bottlenecks or yield fluctuations could trigger a swift, violent mean reversion in extended multiples.
公債殖利率與融資高懸 籌碼面臨考驗Elevated Margin Debt Meets Benchmark Yields in Liquidity Test
支撐高估值體系的外部環境正在逐步收緊。市場在定價美日央行貨幣政策平靜期的同時,選擇性淡化了美國 10 年期公債殖利率仍於 5%臨界點徘徊的流動性壓力。與此同時,台灣全市場融資餘額已快速推升至 5,940 億元的緊繃水位,反映散戶與槓桿資金在指數高檔處的激進擴張。權值股在特定買盤回補下固然維持了指數的表象,但高融資與高利率形成的雙重槓桿成本,大幅削弱了市場承受利空的能力。一旦外部債券市場殖利率再度出現波動,缺乏實質獲利保護的投機部位將面臨劇烈去槓桿處置。The macro underpinnings of these lofty valuations are rapidly tightening. While equities have enjoyed a perceived lull in central bank action between the Federal Reserve and the Bank of Japan, the market has glossed over persistent liquidity friction as the U.S. 10-year Treasury yield hovers near the critical 5% threshold. Concurrently, total margin debt in Taiwan has swelled to a tense NT$594.0 billion, reflecting aggressive retail and levered positioning at the market's peak. Selective institutional short-covering in heavyweights may preserve the index's veneer of strength, but the twin pressures of high leverage and elevated financing costs leave the broader tape brittle. Should bond yields lurch higher once more, speculative pockets lacking substantive near-term cash-flow cushions will face an abrupt and painful deleveraging.
本刊維持審慎防禦的研判,指數高檔震盪中板塊分化將更加嚴峻。未來的觀察重心不在於題材面能否描繪出更遠期的願景,而在於各產業能否在緊繃的資金成本下,將接單轉化為可驗證的實體出貨與自結利潤。唯有實質盈餘能追上定價的標的,方能在均值回歸的浪潮中維持防線。We maintain a cautious, defensive stance: as the index churns at elevated levels, sector divergences will only sharpen. The focal point ahead is not whether management teams can spin more distant strategic narratives, but whether industries can convert high-flying order books into auditable shipments and reported profits against tight capital costs. Only those names whose underlying earnings can sprint to catch up with their market multiples will hold the line when the broader tide of mean reversion inevitably turns.
訂閱全文收錄全市場評價泡泡檢視矩陣、各族群籌碼脆弱度序列,以及期貨多空反轉的關鍵否證指標。The complete subscriber analysis features a comprehensive valuation-bubble diagnostic matrix, sector-level technical vulnerability rankings, and key falsification markers for an institutional futures reversal.