AHI Journal
村田停產常規料退守AI高地:被動元件掀起 3 年長週期大洗牌Murata Halts Legacy MLCC Lines to Fortify AI Stronghold, Triggering 3-Year Cycle Reshuffle
日系龍頭釋出數百億常規與車規MLCC市占,台廠迎來報價上調 3 成的漲價窗口,但組裝端正面臨零組件成本暴衝的雙向擠壓。Japanese titan frees up tens of billions in legacy and auto MLCC market share, handing Taiwanese suppliers room for 30% price hikes, while assemblers face a dual squeeze from surging component costs.
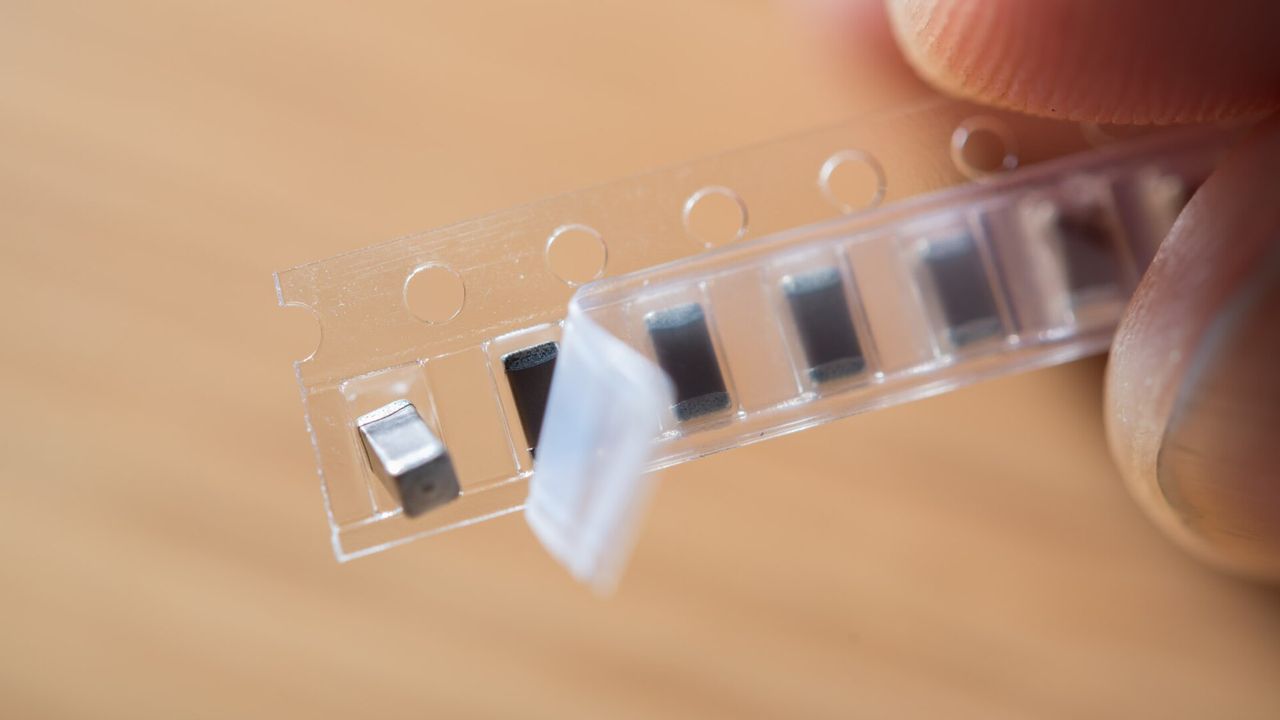
全球被動元件龍頭日本村田宣布產線調整通告,預計在數年內逐步終止常規與部分車規多層陶瓷電容供貨,將產能全數抽調轉移至高利潤的AI運算領域。這項戰略退守瞬間打破了全球電子零組件的供需平衡,讓過去被視作低階大宗物資的常規料件,一夕間躍升為各方爭奪的戰略物資。台廠信昌電已針對大尺寸特殊規格調漲 3 成報價,國巨與華新科產能利用率亦同步拉升。與此同時,金融市場在宏觀壓力下面臨劇烈震盪,但供應鏈深處正經歷一場長達數年的結構性洗牌,原本充裕的基礎電子組件正面臨產能被抽乾的嚴酷現實。Japan’s Murata Manufacturing, the world’s dominant passive component supplier, has formally notified customers that it will phase out shipments of standard and select automotive-grade multilayer ceramic capacitors (MLCCs) over the next several years, reallocating its entire production capacity toward high-margin AI computing. This strategic retreat has abruptly upended the global balance of supply and demand for electronic components, transforming basic commodity parts into hotly contested strategic assets overnight. In Taiwan, Prosperity Dielectrics (PDC) has already raised prices by 30% on large-format specialized specifications, while capacity utilization rates at Yageo and Walsin Technology have surged in tandem. Although financial markets remain rattled by macroeconomic headwinds, a deep-seated structural realignment is underway across the supply chain, as once-abundant legacy components confront an uncompromising drain on available capacity.
算力功耗飆升引發產能實質排擠Surging Compute Power Triggers Physical Capacity Crowding
這場供給失衡絕非典型的短期景氣波動,而是半導體功耗急速擴張帶來的連鎖效應。現代AI伺服器機櫃功耗動輒突破 100kW,高壓直流電氣架構對於大尺寸、耐高壓與耐高溫特性的高階被動元件產生幾何級數的消耗。國際龍頭將核心資源全面轉向超大型資料中心的高階規格,本質上是全球最頂尖的被動元件產能遭到先進算力無情吸納,進而對常規標準品造成物理性排擠。研調顯示這波高階元件供需缺口將延續數年,日系大廠騰出的龐大市占缺口,迫使全球一線硬體客戶轉向具備在地量產能力的台灣供應鏈尋求長期支援。This supply imbalance is no ordinary cyclical blip; it is a direct knock-on effect of explosive semiconductor power consumption. Modern AI server racks routinely draw more than 100 kW, and their high-voltage direct-current architectures demand an exponential increase in high-end passive components engineered for large footprints, elevated breakdown voltages, and extreme thermal resilience. By redirecting premier manufacturing lines to hyperscale data center specifications, Japanese heavyweights have effectively allowed advanced compute to siphon off the world’s elite passive component capacity, physically crowding out general-purpose standards. Industry research indicates this supply shortfall will persist for years, and the vast market share vacated by Japanese peers is compelling tier-one global hardware makers to seek long-term supply agreements with Taiwanese vendors capable of local volume manufacturing.
轉單紅利背後浮現組裝成本危機Order Inflows Conceal a Mounting Assembly Cost Crisis
供需傾斜直接化為具體的財務數字。信昌電第 2 季毛利率躍升至 28.84%,季增逾 5 個百分點,AI營收占比預計在下半年顯著拉高,更投入數十億元擴建新廠以因應訂單;國巨長線營收與獲利預期亦獲法人顯著調升。然而,零組件價格飆漲正對下游系統組裝端帶來巨大災難。被動元件與先前大漲的記憶體、載板形成成本共振,大幅推升硬體物料清單支出。5 大組裝廠單月筆電出貨量驟減逾 3 成,品牌端已無力將暴漲的零組件成本全額轉嫁給終端消費者,PC與通用伺服器市場的獲利空間正被嚴重侵蝕。The supply-demand dislocation is translating rapidly into financial gains upstream. PDC’s second-quarter gross margin leaped over five percentage points sequentially to 28.84%, with AI-related revenue expected to climb sharply in the second half as the company commits billions of New Taiwan dollars to new plant construction; sell-side analysts have also markedly upgraded long-term earnings forecasts for Yageo. Downstream system integrators, however, face a mounting crisis. Surging passive component quotes are compounding earlier spikes in memory and IC substrate costs, inflating bills of materials across the board. Monthly notebook shipments across the top five Taiwanese contract manufacturers tumbled by more than 30%, and PC brands are unable to pass these surging component costs on to end consumers, severely compressing operating margins across traditional PCs and general-purpose servers.
存量掠奪加劇供應鏈冰火兩重天Zero-Sum Reallocation Widens Supply Chain Divergence
當前台股市場投機情緒高漲,單日當沖交易比重飆破 4 成,期貨市場空單更長期維持在數萬口的高水位,反映出資本市場對宏觀流動性的深層焦慮。市場慣於將被動元件漲價視為產業全面復甦的信號,但本輪行情的底色是殘酷的存量掠奪。產業鏈內部正呈現極端分化:手握特殊材料自製技術與大尺寸產能的上游供應商,能憑藉定價優勢享有豐厚利差;缺乏話語權的終端系統代工廠,則被夾在缺料斷鏈與成本暴增的狹縫中,原本微薄的營業利益率面臨嚴苛考驗,不同環節的體質差距正被不可逆地拉大。Speculative fervor in Taiwan’s equity market remains elevated, with intraday day trading topping 40% of total turnover and futures short positions anchored at historic highs, underscoring persistent macro liquidity concerns. While markets routinely interpret passive component price hikes as a herald of broad cyclical recovery, this rally is fundamentally a zero-sum reallocation of finite capacity. The hardware ecosystem is fracturing into extremes: upstream suppliers possessing proprietary specialty materials and large-case capacity are reaping widening margins backed by formidable pricing power, while commoditized contract assemblers, hemmed in by component shortages and soaring procurement costs, face severe erosion of their razor-thin operating margins. The operational gap across tiers of the tech stack is widening irreversibly.
本刊認為,這場由頂級算力引發的被動元件轉單潮,並不是雨露均霑的週期回暖,而是零組件通膨對下游硬體生態的實質反噬。未來的關鍵不在於上游廠商接單有多熱絡,而在於伺服器與PC組裝廠能否守住利潤防線。接下來應密切觀察組裝代工端毛利率的滑落幅度,這將決定成本壓力何時會由下而上反向阻斷供應鏈的擴張。In our view, this wave of redirected passive component orders triggered by premier compute is far from a broad-based cyclical tide that lifts all boats; it represents an upstream inflationary shock that risks suffocating downstream hardware margins. The pivotal metric going forward is not the swelling order books of component makers, but whether server and PC assemblers can defend their profitability. Investors should closely monitor margin compression across contract manufacturers to gauge when downstream cost pressures will begin throttling broader supply chain expansion.
訂閱版提供台日被動元件交期追蹤、組裝廠BOM成本拆解表,以及ODM毛利率防守檢查點。The subscriber edition details Taiwan-Japan passive component lead-time trackers, assembly-side BOM cost-breakdown models, and ODM gross-margin defense thresholds.