AHI Journal

2026 年 9 月 11 日 星期五Friday, September 11, 2026登入Log In訂閱Subscribe
風險維度RISK DIMENSIONS

光纖缺料與零組件成本反噬:高階網通擴產遭遇物理供應鏈暗礁Fiber Raw Material Shortages and Surging Component Costs: High-End Optical Networking Expansions Hit Physical Reefs

光聖上半年毛利突破 6 成卻受限光纖原料配額,PCB高多層板與InP基板供應吃緊,硬體升級週期正演變為搶料戰役。FOCI's first-half gross margin topped 60% yet faces fiber material quota caps; with high-layer PCBs and InP substrates tightly constrained, hardware upgrades are turning into an allocation battle.
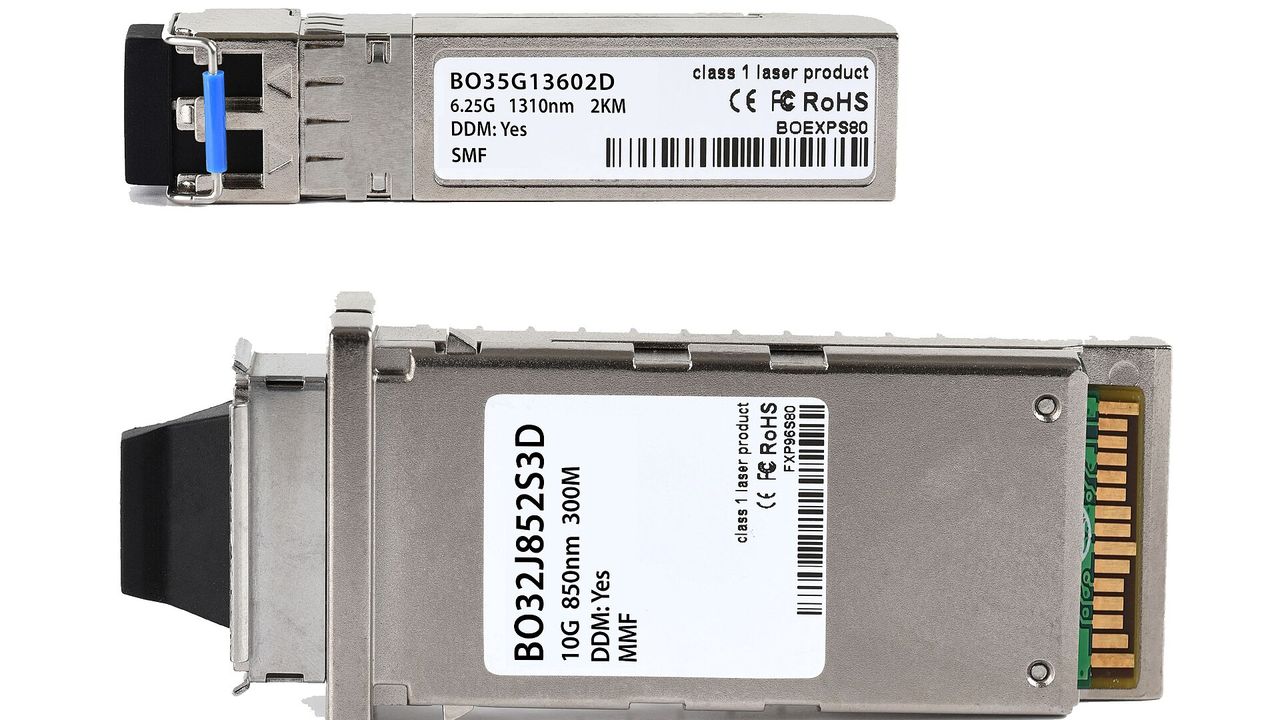
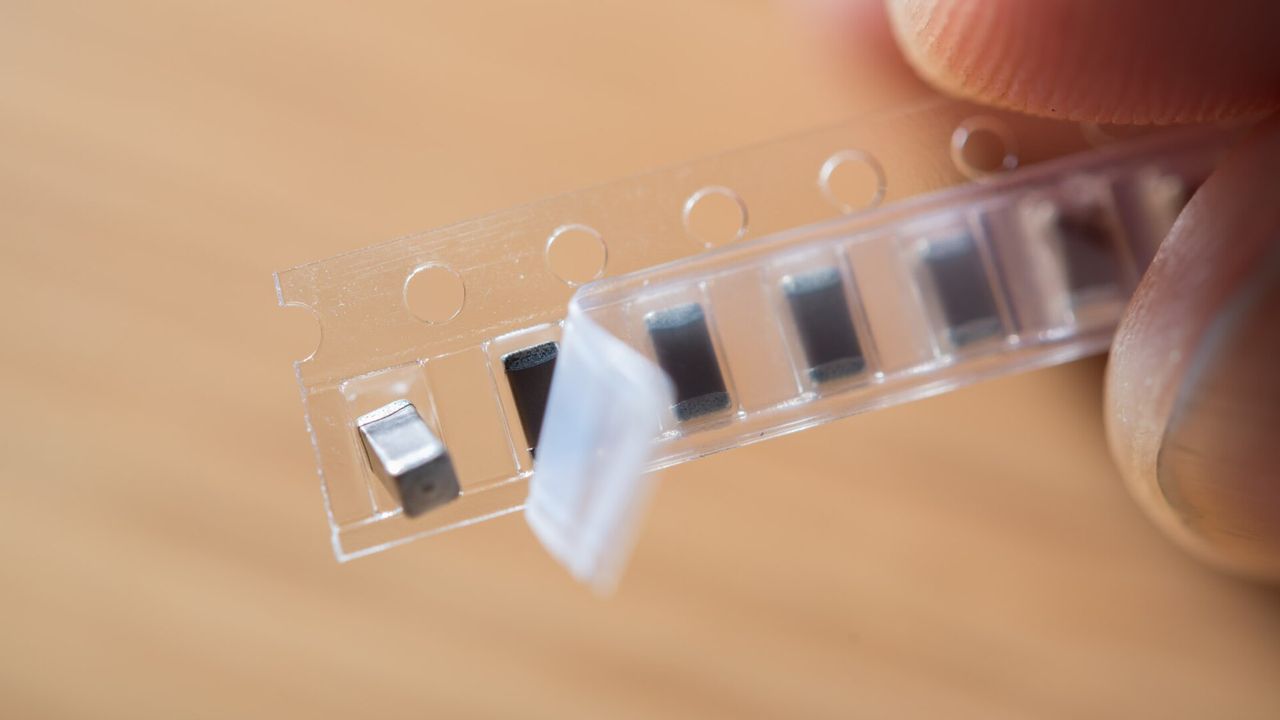
optical(光纖收發模組實物照)
圖:Photo: Martijn Boer 授權:License: Public domain 來源:Source: Wikimedia Commons
2026 年 9 月 11 日 星期五Friday, September 11, 2026風險Risk光通訊與 CPOOptical & CPO免費版Free Edition
下一個可驗證時點Next checkpoint10/10(六)6442 光聖 9 月營收(10 日前申報)
到時候看What to check9 月營收年增率是否高於前 3 個月平均(前 3 個月平均年增 +55.6%);月增率有沒有延續,累計年增率的方向。

AI資料中心對傳輸頻寬的極致追逐,正將光通訊供應鏈推向物理供給極限。市場聚焦於 800G與 1.6T高速光模組爆發,但上游基礎原料短缺已成為阻礙出貨的實體路障。指標光被動元件廠光聖第 2 季毛利率飆升至 62%,前 8 個月合併營收突破 92 億元,然而營運擴張已完全受制於高階光纖原料的取得配額。當終端訂單急速堆疊,關鍵原料產能擴充卻受限於漫長的物理週期,這場由硬體技術升級帶動的擴產狂潮,已非單純的資本支出競賽,而是演變成全球供應鏈深度失衡的搶料戰役。The AI data center boom and its insatiable thirst for network bandwidth are pushing the optical communications supply chain to its physical limits. While equity markets remain fixated on the explosive rollout of 800G and 1.6T high-speed optical transceivers, upstream raw material deficits have emerged as a tangible bottleneck hobbling finished goods shipments. Passive optical component leader Optical Communication Products Inc. (FOCI) saw its second-quarter gross margin surge to 62%, with cumulative eight-month revenue topping NT$9.2 billion; nonetheless, operational throughput is now constrained by raw material allocations for high-grade optical fibers. As downstream backlogs mount, long manufacturing lead times for upstream inputs have turned this capacity race into an intense scramble for raw materials.

高階光纖與晶圓基板受限配額Fiber Preforms and InP Wafers Bottlenecked by Allocation

這場缺料危機正迅速跨越單一環節,朝整個高階光通訊生態系擴散。高速光收發模組不可或缺的磷化銦基板,受到地緣政治審批以及原廠產能配置箝制,直接壓抑了主要磊晶廠在第 2 季的排程進度。與此同時,光纖預製棒的供應配額也成為制約光被動元件出貨的核心瓶頸。儘管高芯數光纖產品需求暴增,但由於上游特種玻璃材料擴產緩慢,業者即便掌握龐大訂單,亦只能依照分配到的原料總量進行限量生產。當硬體規格快速迭代,缺乏底層基礎材料支持的產能擴充,正在實質拉長產品交付週期。Material shortages are rippling beyond isolated links and into the broader high-speed optical ecosystem. Indium phosphide (InP) substrates, indispensable for high-speed optical transceivers, are constrained by geopolitical licensing approvals and primary fab allocations, which throttled wafer output schedules for major epi-wafer suppliers during the second quarter. Concurrently, supply quotas on fiber preforms have become the primary roadblock capping shipments of passive optical assemblies. Despite voracious demand for high-count fiber architectures, upstream expansion for specialty optical glass remains sluggish, leaving fabricators unable to run above their allotted raw material inputs. As hardware iterations accelerate, capacity buildouts unsupported by baseline input materials are extending product delivery timelines.

本文提及標的等權走勢 走勢圖111.885.8259.8392.22起點 = 10006-2607-1407-2908-1308-2809-14本文提及標的等權走勢 走勢圖111.885.8259.8392.22起點 = 10006-2607-2408-2009-16
本文提及標的等權走勢(起點 = 100) 5 檔等權・60 個交易日讀法:把本文提到、且有行情的 5 檔用相同權重合成一條線(起點 100),看的是這批標的作為一群的相對位置;個股之間的差異在下一張圖。
本篇標的近 20 日漲跌幅:收盤價 08-21 → 09-18;只列本篇提到且有行情的標的本篇標的近 20 日漲跌幅Recent Move收盤價 08-21 → 09-18;只列本篇提到且有行情的標的Close-to-close change for names covered in this piece−8%+8%01815 富喬1815 富喬+6.70%119.50119.506442 光聖6442 光聖+3.30%1575.001575.001802 台玻1802 台玻+2.10%58.8058.806584 南俊國際6584 南俊國際−2.00%576.00576.008210 勤誠8210 勤誠−4.40%902.00902.00本篇標的近 20 日漲跌幅:收盤價 08-21 → 09-18;只列本篇提到且有行情的標的本篇標的近 20 日漲跌幅Recent Move收盤價 08-21 → 09-18;只列本篇提到且有行情的標的Close-to-close change for names covered in this piece−8%+8%01815 富喬1815 富喬+6.70%119.50119.506442 光聖6442 光聖+3.30%1575.001575.001802 台玻1802 台玻+2.10%58.8058.806584 南俊國…6584 南俊國際6584 南俊國…−2.00%576.00576.008210 勤誠8210 勤誠−4.40%902.00902.00
讀法:同一段期間、同一個口徑,所以彼此可以比。右側數字是最新收盤價。新聞把這些公司寫在一起,價格未必同意——分歧本身就是一則資訊。

高多層載板原料引爆漲價連鎖High-Layer Substrates Trigger an Upstream Pricing Chain

材料瓶頸同樣在高階印刷電路板領域全面發酵。AI伺服器高多層板與高階交換器板的層數要求,動輒突破 28 層乃至 40 層以上,對低介電玻纖布與極高頻銅箔基板的需求形成幾何級數增長。台玻 8 月份合併營收 45.92 億元,表現略遜於市場預期,核心原因即是高階玻纖布的產能擴張速度,追趕不上終端拉貨的激進需求。在供需缺口急遽擴大的背景下,建滔與富喬等上游材料廠商已在醞釀新一輪報價調漲。高階材料供給的結構性僵化,使下游PCB製造商在承受交期延宕的同時,也面臨原物料成本大幅反噬的利潤擠壓。Similar bottlenecks have surfaced across advanced printed circuit boards. High-layer AI server motherboards and premium switch fabrics routinely require 28 to more than 40 layer counts, driving exponential demand for low-dielectric glass fabrics and ultra-high-frequency copper-clad laminates. Taiwan Glass reported August consolidated revenue of NT$4.592 billion, missing street expectations primarily because its capacity expansions in advanced glass fabrics could not keep pace with aggressive pull-ins. Facing widening structural supply gaps, upstream material producers including Kingboard Holdings and Fulltech Fiber Glass are preparing fresh price hikes. The structural rigidity in high-grade input supply not only saddles downstream PCB makers with extended lead times, but also erodes gross margins via raw material cost inflation.

長短料失衡導致系統組裝承壓Kitting Mismatches Pressure Downstream System Assembly

零組件短缺與成本攀升的代價,最終由終端系統整合與組裝廠概括承受。在伺服器電源端,關鍵功率元件與高容積積層陶瓷電容的缺貨,使整體交付時程出現數週落後。這類長短料問題迅速傳導至周邊機構件,勤誠與南俊國際等機殼與導軌業者,8 月份的營收達成率普遍回落至 57%至 66%區間,主因正是組裝線因零件不齊套而放緩拉貨節奏。訂單爆滿卻無法轉化為完整出貨的矛盾,不僅迫使製造商承擔龐大的在製品庫存,也使得營運資金週轉天數顯著攀升,形成嚴重的資金積壓風險。The financial toll of parts shortages and input inflation lands squarely on downstream system integrators and contract assemblers. In the server power segment, shortages of high-voltage power devices and high-capacitance multilayer ceramic capacitors (MLCCs) have pushed delivery schedules out by several weeks. These component mismatches have quickly spread to mechanical enclosures. Server chassis and slide-rail suppliers such as Chenbro Micom and Nan Juen International saw August revenue run rates fall to between 57% and 66% of internal forecasts, as finished assembly lines slowed pull-ins on incomplete kits. This inability to clear packed backlogs into billable shipments burdens manufacturers with bloated work-in-process inventory and extends working capital cash conversion cycles.

高階網通與伺服器族群當前的市場評價,高度依賴產能逐季無縫放量的樂觀預期。然而,光纖預製棒、磷化銦基板與特種高階樹脂的擴產週期長達 18 至 24 個月,並非短期資金能立即填補。後續必須緊盯高階材料交期是否持續惡化,一旦零組件齊套延宕迫使終端機櫃建置放緩,高估值架構將承受下修壓力。Current market valuations across networking hardware and server supply chains hinge on expectations of seamless, quarter-over-quarter volume acceleration. However, capacity expansion cycles for optical preforms, InP substrates, and specialty advanced resins range between 18 and 24 months, defying fast capital-fueled solutions. Going forward, investors must monitor whether lead times for specialized materials continue to widen. If kitting shortfalls ultimately stall finished rack deployments, richly valued tech multiples face downward pressure.

訂閱版梳理光纖預製棒與InP擴產週期序列、組裝廠庫存週轉率預警線,以及伺服器機櫃遞延檢查點。The subscriber edition details fiber preform and InP expansion lead-time schedules, assembler inventory turnover warning lines, and rack-level delivery delay audit points.
閱讀訂閱版Read the subscriber edition

本刊結論:Our verdict: 立場:偏空高階網通供應鏈下半年出貨與擴產指引;信心:高,因光纖預製棒、InP晶圓與特種樹脂擴產需 18 至 24 個月,長短料限制短期難解;否證:若光聖下半年營收不受原料配額限制且毛利率維持在 62%以上,則本刊判斷錯誤。

接下來看什麼What to watch next

  1. 光聖第 2 季毛利率:門檻數字為 62%,下半年若毛利率跌破 62%則偏空成立,若維持或超過 62%則不成立。
  2. 勤誠與南俊國際 8 月營收達成率:門檻區間為 57%至 66%,後續月份達成率若持續落在 66%以下則偏空成立,若回升突破 66%則不成立。
  3. 台玻 8 月營收:門檻數字為 45.92 億元,後續月份營收若持續低於 45.92 億元顯見高階玻纖布增幅不足則偏空成立,若回升超越 45.92 億元則不成立。

風險燈號Risk Dashboard

總經軸Macro
受美國 8 月份生產者物價指數(PPI)年增幅衝上 5.4%且超出預期影響,10 年期美債收益率貼近 4.96%,加上歐洲央行調升利率 25 個基點,使各界在超級央行週登場前對貨幣緊縮的焦慮急遽擴大。US August PPI jumped 5.4% year over year, topping forecasts and pushing the 10-year Treasury yield near 4.96%, while the ECB's 25-basis-point hike compounded monetary tightening anxieties heading into a heavy central-bank week.
流動性軸Liquidity
外資台指期淨空單擴大至 83,918 口極端空區,大盤當沖買賣成交金額占比雙雙突破 41.7%,融資逆勢增至 5,919 億元,籌碼面呈現極度脆弱對峙。Foreign net short positions in Taiwan Index Futures widened to an extreme 83,918 contracts, while day-trading turnover ratios breached 41.7% and margin debt rose to NT$591.9 billion, leaving technical positioning fragile.
產業敘事軸Industry Narrative
AI資料中心算力需求無虞,但物理瓶頸轉向電網通電等待期、光纖上游原料配額限制及PCB高階材料缺貨,組裝端承受長短料與成本擠壓。AI data center compute demand remains solid, but physical limits have shifted to grid interconnection queues, optical fiber raw material quotas, and high-end PCB shortages, squeezing assemblers through parts imbalances and cost hikes.
時間性軸Seasonality
時序步入台股歷史系統性負報酬之 9 月中旬,撞上下週主要央行密集決策會議及台指期月結算,高檔獲利了結與避險賣壓進入高峰期。Trading enters mid-September, historically a window of negative seasonal returns for the Taiex, colliding with major central-bank decisions and monthly futures settlement to peak profit-taking and hedging pressures.

要聞速覽What’s News看完整內容 →full story →

市場Markets

台指夜盤重挫近 800 點Taiwan Index Futures Drop Nearly 800 Points Overnight美國主要四大指數集體收黑,拖累夜盤台指期重跌 797 點,終場以 46,072 點作收。Broad declines across four major US equity indexes knocked o…

當沖成交值占比衝破 4 成Day-Trading Value Ratio Breaches 40%集中市場單日當沖買賣成交金額占比雙雙突破 41.7%,半導體與零組件占當沖比重逾 6 成。Central exchange day-trading buy and sell value ratios both …

歐洲央行升息一碼至 2.5%ECB Hikes Rates by 25 Basis Points to 2.5%歐洲央行將存款機制利率上調 25 個基點至 2.50%,主要再融資利率升至 2.65%。The European Central Bank raised its deposit facility rate b…

產業與企業Industry & Companies

村田啟動停產引爆轉單Murata Line Halts Trigger Component Order Rerouting日系被動元件龍頭村田縮減車規與常規MLCC產線,全面轉向高階AI規格。Japanese passive component leader Murata is scaling back aut…

士電在手訂單衝破 600 億Shihlin Electric Order Backlog Tops NT$60 Billion受惠台電電網強韌計畫、北美變壓器外銷與AI資料中心建置,士電在手訂單突破 600 億元。Boosted by Taipower's grid resilience project, North America…

本期其他文章More From This Issue

回本期目錄 →Back to issue index →
頭條COVER STORY

村田停產常規料退守AI高地:被動元件掀起 3 年長週期大洗牌Murata Halts Legacy MLCC Lines to Fortify AI Stronghold, Triggering 3-Year Cycle Reshuffle

日系龍頭釋出數百億常規與車規MLCC市占,台廠迎來報價上調 3 成的漲價窗口,但組裝端正面臨零組件成本暴衝的雙向擠壓。Japanese titan frees up tens of billions in legacy and auto MLCC market share, handing Taiwanese suppliers room for 30% price hikes, while assemblers face a dual squeeze from surging component costs.

2026-09-11產業Industry半導體Semiconductors
閱讀 →Read →
AI與產業鏈AI & SUPPLY CHAIN

AIDC電網供電受限催生現場發電:士電 600 億在手對決Bloom Energy暴衝AIDC Grid Delays Drive On-Site Power: Shihlin Electric's NT$60 Billion Backlog Meets Bloom Energy's Surge

資料中心通電時程拖延達數年,表後發電與高壓變壓器成為真正算力限制,重電與燃料電池大廠迎來長期資本支出訂單。Data center grid interconnects stretch over years, turning behind-the-meter power and high-voltage transformers into the true compute bottleneck, unlocking long capex dividends for heavy electrical and fuel-cell makers.

2026-09-11科技Technology綜合General
閱讀 →Read →
評等動向RATING TRENDS

賣方集體上調重電與航運:非科技權值股走出獨立獲利重估路徑Sell Side Broadly Upgrades Heavy Electrical and Shipping: Non-Tech Heavyweights Forge Independent Rerating Paths

電子高評價面臨公債殖利率壓抑,分析師目光轉向訂單直達 2028 年的變壓器廠與日租金翻倍的散裝航運龍頭。High tech valuations face headwinds from treasury yields, diverting analyst attention to transformer builders booked through 2028 and dry bulk shippers with doubling daily charter rates.

2026-09-11評等Ratings航運Shipping
閱讀 →Read →
海外連動GLOBAL CROSSCURRENTS

拉美採礦熱潮引爆中國重卡出海:資源週期與二手車替代通道成形Latin American Mining Boom Sparks Chinese Heavy-Truck Exports: Resource Cycles Drive Used-Fleet Substitution

金屬礦產暴漲推動南美礦區資本開支,中國重卡憑藉性價比加速替代歐美二手車,上半年出口量年增近 7 成。Soaring metals prices lift South American mine capex, as cost-effective Chinese heavy trucks rapidly displace western used vehicles, driving first-half export volumes up nearly 70% year over year.

2026-09-11海外Global綜合General
閱讀 →Read →
本刊觀點Editor's View

實體瓶頸反噬虛擬算力:定價權移轉的脆弱平衡Maintaining Strategic Restraint Amid Liquidity Divergence and Cost Restructuring

市場態:立場:實體供應鏈瓶頸壓制中游組裝毛利,定價權倒向重電與稀缺材料端;信心:中高;否證:上游關鍵原料配額超預期釋出或雲端資本支出實質下修。Market State: Armed Stance: The Taiex holds above its 200-day moving average, but foreign net short positions in Taiwan Index Futures sit at extreme levels and day-trading ratios remain unbalanced, keeping high-valuation assets under corrective pressure.

2026-09-11本刊觀點Editor's View綜合General
閱讀 →Read →